
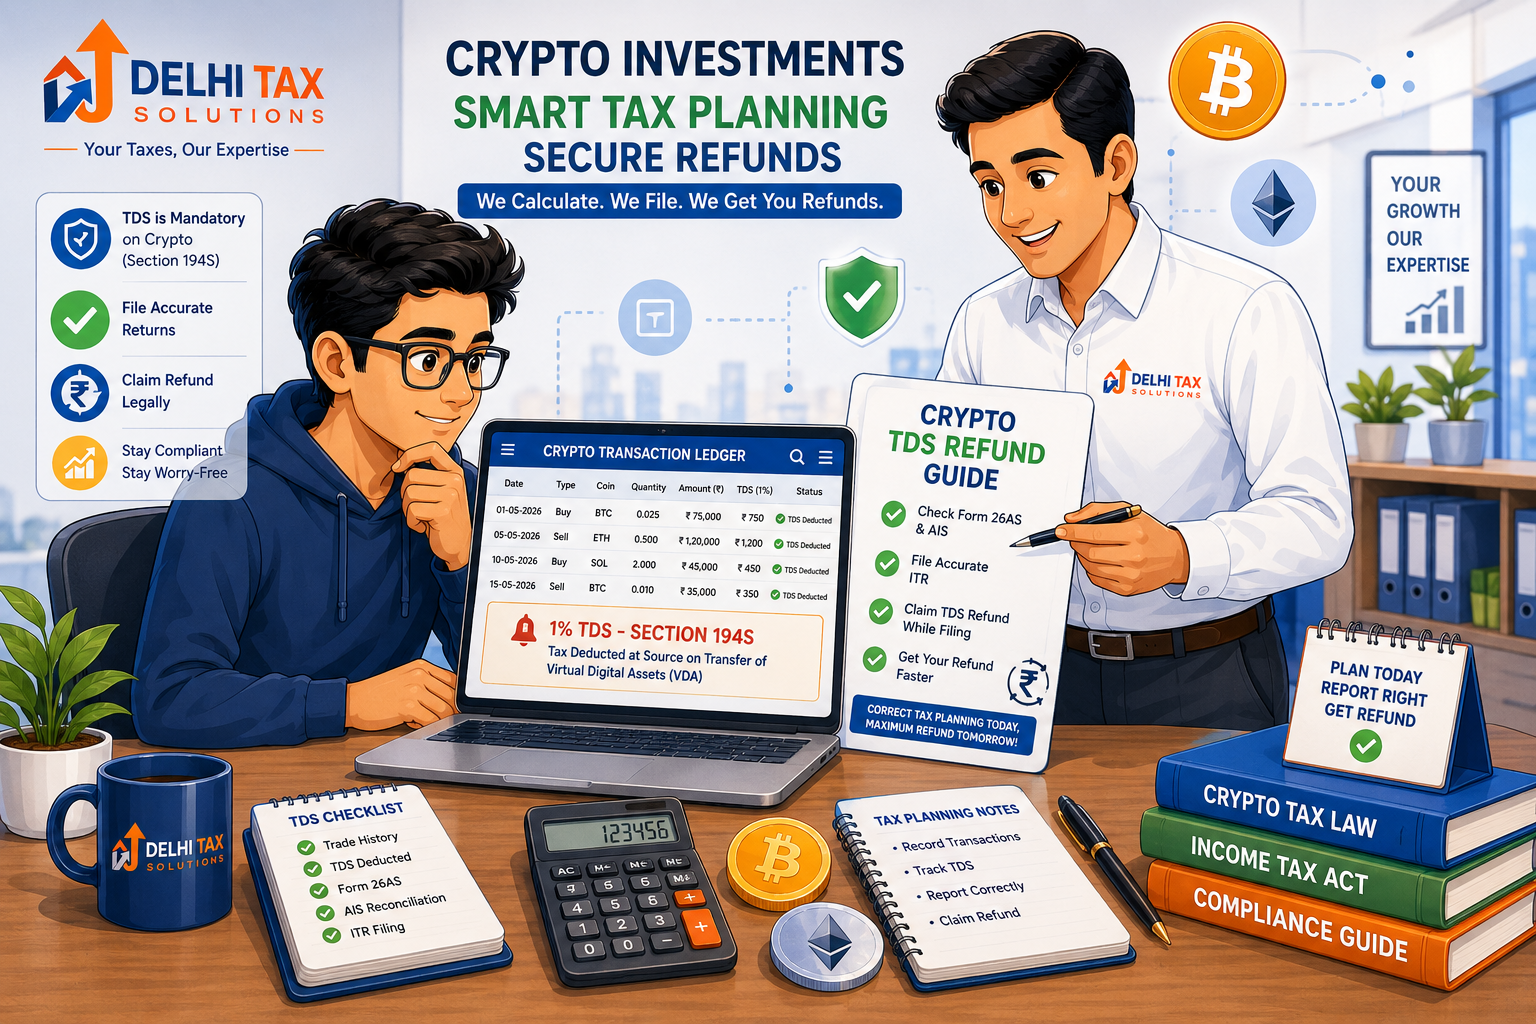
💡 Key Takeaways
- Section 194S mandates a 1% Tax Deducted at Source on all virtual digital asset transfers across platforms.
- The general crypto TDS exemption limit is ₹50,000 per financial year for specified individual categories.
- Exchanges and buyers must deduct TDS at the time of credit or payment, whichever occurs earlier.
- Excess deductions can be claimed back as tax refunds while filing annual income tax returns.
- Expert Chartered Accountant filing prevents costly scrutiny notices from revenue authorities.
Navigating the digital asset ecosystem in India requires strict adherence to evolving fiscal mandates. Since the introduction of virtual digital asset taxation, compliance has shifted from an optional choice to an absolute legal requirement for every active investor. Understanding how the tax architecture operates prevents severe statutory penalties and audit flags from revenue authorities.
The Income Tax Department enforces a rigorous deduction mechanism designed to track every digital transaction across centralized and decentralized networks. Whether you trade utility tokens, altcoins, or major cryptocurrencies, mastering the nuances of TDS on crypto transactions section 194S is critical for protecting your capital and maintaining clean financial records.
In this comprehensive guide, our chartered accountant advisory team breaks down statutory thresholds, deduction mechanics, reporting obligations, and recovery procedures. Let us examine how these rules impact your everyday portfolio management.
What Is Section 194S and How Does It Function?
Section 194S of the Income Tax Act mandates that any person responsible for paying consideration for the transfer of a Virtual Digital Asset (VDA) must deduct tax at the rate of 1%. This provision ensures complete transparency in crypto transactions by creating a digital paper trail directly monitored by the Central Board of Direct Taxes. Whenever a transfer occurs, the deductor must withhold a fraction of the transaction value before releasing the net payout to the seller.
The implementation of 1% TDS on VDA transfer applies universally across peer-to-peer trades executed through exchanges as well as direct wallet-to-wallet transfers, unless specific statutory exemptions apply. Crypto exchanges operating in India act as representative deductors, automating the withholding process during order execution. For corporate entities holding digital assets, integrating these automated deductions into accounting software is vital, often complementing structured corporate setups like GST Registration services.
Decoding Thresholds and Exemption Limits
Not every digital asset transfer triggers an immediate tax deduction. Parliament established a clear crypto TDS exemption limit to protect small-scale retail participants from excessive compliance burdens. Under the statute, the aggregate transfer value threshold is set at ₹50,000 per financial year for specified individuals and Hindu Undivided Families whose total business turnover does not exceed ₹1 crore, or ₹50 lakhs for professions.
For all other corporate bodies and high-volume traders, a lower monetary threshold of ₹10,000 per financial year applies. Once cumulative transactions cross these limits, the deductor must withhold 1% on the entire consideration amount. Proper classification of trading volume ensures smooth operations, often paired with seamless GST Registration Threshold protocols.
Comparing Tax Structures Across Asset Classes
The regulatory environment for digital assets differs substantially from conventional financial instruments like equity shares, mutual funds, or real estate. Understanding these structural divergences helps investors structure portfolios efficiently without triggering unintended tax penalties or missing statutory obligations enforced by the Income Tax Department.
| Parameter | Virtual Digital Assets (Crypto) | Listed Equities & Funds |
|---|---|---|
| Tax Deduction (TDS) | 1% under Section 194S on transfers | Applicable on specific dividends/interest |
| Flat Tax Rate | 30% flat tax without indexation | 12.5% to 20% based on holding periods |
| Loss Set-Off | Not permitted across crypto assets | Permitted across similar asset classes |
As highlighted in official advisories published by the Press Information Bureau, government regulations treat virtual assets distinctly due to their high volatility and decentralized nature. Ensuring proper verification under PAN Card Application guidelines is essential for fintech operations.
Step-by-Step Guide on How to Claim Crypto TDS Refunds
Because 1% TDS is deducted on gross transaction values rather than net taxable income, many traders face situations where total tax deducted exceeds their actual annual tax liability. Learning how to claim crypto TDS refund is essential to recover locked capital legally and efficiently during your annual income tax filing cycle.
The recovery process begins by downloading your Form 26AS and Annual Information Statement directly from the government tax portal. Ensure that figures reported by exchanges match your internal trading ledger records. When filing your Income Tax Return, report your VDA capital gains under Schedule VDA and input exact TDS credits.
⚡ In a Nutshell
Always cross-verify your exchange ledger data against Form 26AS before filing your ITR to prevent automated mismatch notices from the tax department.
Maintaining robust financial records also supports comprehensive fiscal health across all business ventures, aligning with broader strategic frameworks detailed on our Rules of Income Tax hub.
Avoiding Common Pitfalls in Digital Asset Compliance
Navigating digital asset taxation without professional guidance exposes investors to severe compliance risks. A frequent mistake is failing to account for transactions conducted on decentralized or peer-to-peer platforms where automated TDS deduction does not occur natively. In P2P trades, the buyer holds the statutory obligation to deduct 1% and deposit it with the government.
Another critical error involves attempting to offset crypto losses against gains from other crypto assets or traditional equities. Current statutory provisions strictly prohibit loss offsetting within the VDA category. Staying fully compliant requires systematic record-keeping and collaboration with experienced tax professionals.
Conclusion and Next Steps for Investors
Mastering TDS on crypto transactions section 194S is indispensable for anyone actively participating in India’s digital economy. From tracking the 1% deduction threshold to verifying Form 26AS and claiming eligible refunds through structured ITR filing, meticulous attention to detail shields your portfolio from unnecessary penalties.
Talk to a Delhi Tax Solutions expert to get your crypto tax computation and annual return filing handled with absolute professional precision. Connect with our dedicated CA advisory team today to safeguard your digital asset investments and ensure seamless regulatory compliance moving forward.
About this article: Researched using official government sources and Delhi Tax Solutions’ in-house tax advisory team. Last updated August 2026.
Frequently Asked Questions
+ Q: What is the exact monetary threshold for TDS on crypto transactions under Section 194S?
A: The statutory exemption limit for TDS under Section 194S is ₹50,000 per financial year specifically applicable to individual taxpayers and Hindu Undivided Families whose business turnover does not exceed ₹1 crore or professional gross receipts do not exceed ₹50 lakhs. For all corporate entities, partnership firms, and high-volume traders exceeding these turnover criteria, a lower threshold of ₹10,000 per financial year applies before the mandatory 1% deduction kicks in on all VDA transfers.
+ Q: How can taxpayers claim a refund if excess 1% TDS was deducted on crypto transfers?
A: To claim a refund for excess crypto TDS deducted throughout the financial year, you must verify that all deductions correctly reflect in your Form 26AS and Annual Information Statement downloadable from the official Income Tax Department portal. While filing your annual Income Tax Return, report your virtual digital asset capital gains under Schedule VDA and input the precise TDS credits. If total tax deducted exceeds your actual tax liability computed at the flat 30% rate, the Centralized Processing Center refunds the balance directly to your bank account.
+ Q: Do peer-to-peer (P2P) crypto transactions attract Section 194S TDS compliance?
A: Yes, peer-to-peer crypto transactions fully attract Section 194S TDS compliance requirements. Unlike centralized exchanges where the platform automates the deduction, in a direct P2P transfer, the buyer of the virtual digital asset is legally designated as the deductor. The buyer must withhold 1% of the consideration amount, deposit it with the Income Tax Department using the appropriate challan, and furnish Form 26Q or equivalent statements to remain fully compliant with statutory rules.
+ Q: What are the legal penalties for failing to deduct or deposit crypto TDS in India?
A: Failure to deduct or deposit TDS on VDA transfers under Section 194S attracts stringent penal consequences under the Income Tax Act. Deductors failing to withhold tax are liable to pay penal interest ranging from 1% to 1.5% per month on the defaulted amount until compliance is fulfilled. Additionally, disallowance of business expenses equivalent to 30% of the payment may apply if the deductor is a business entity, alongside potential prosecution and late filing fees for delayed quarterly statement submissions.
+ Q: How does Section 194S interact with the flat 30% tax rate on virtual digital assets?
A: Section 194S operates as an advance withholding mechanism that deducts 1% at the time of transaction, whereas Section 115BBH levies a flat 30% tax on net profits derived from VDA transfers. The 1% TDS deducted throughout the year serves as a tax credit that directly offsets your final 30% tax liability during annual ITR filing. Since VDA losses cannot be offset against gains, tracking every transaction ensures that your final tax computation matches your actual net earnings after accounting for deducted TDS credits.
