
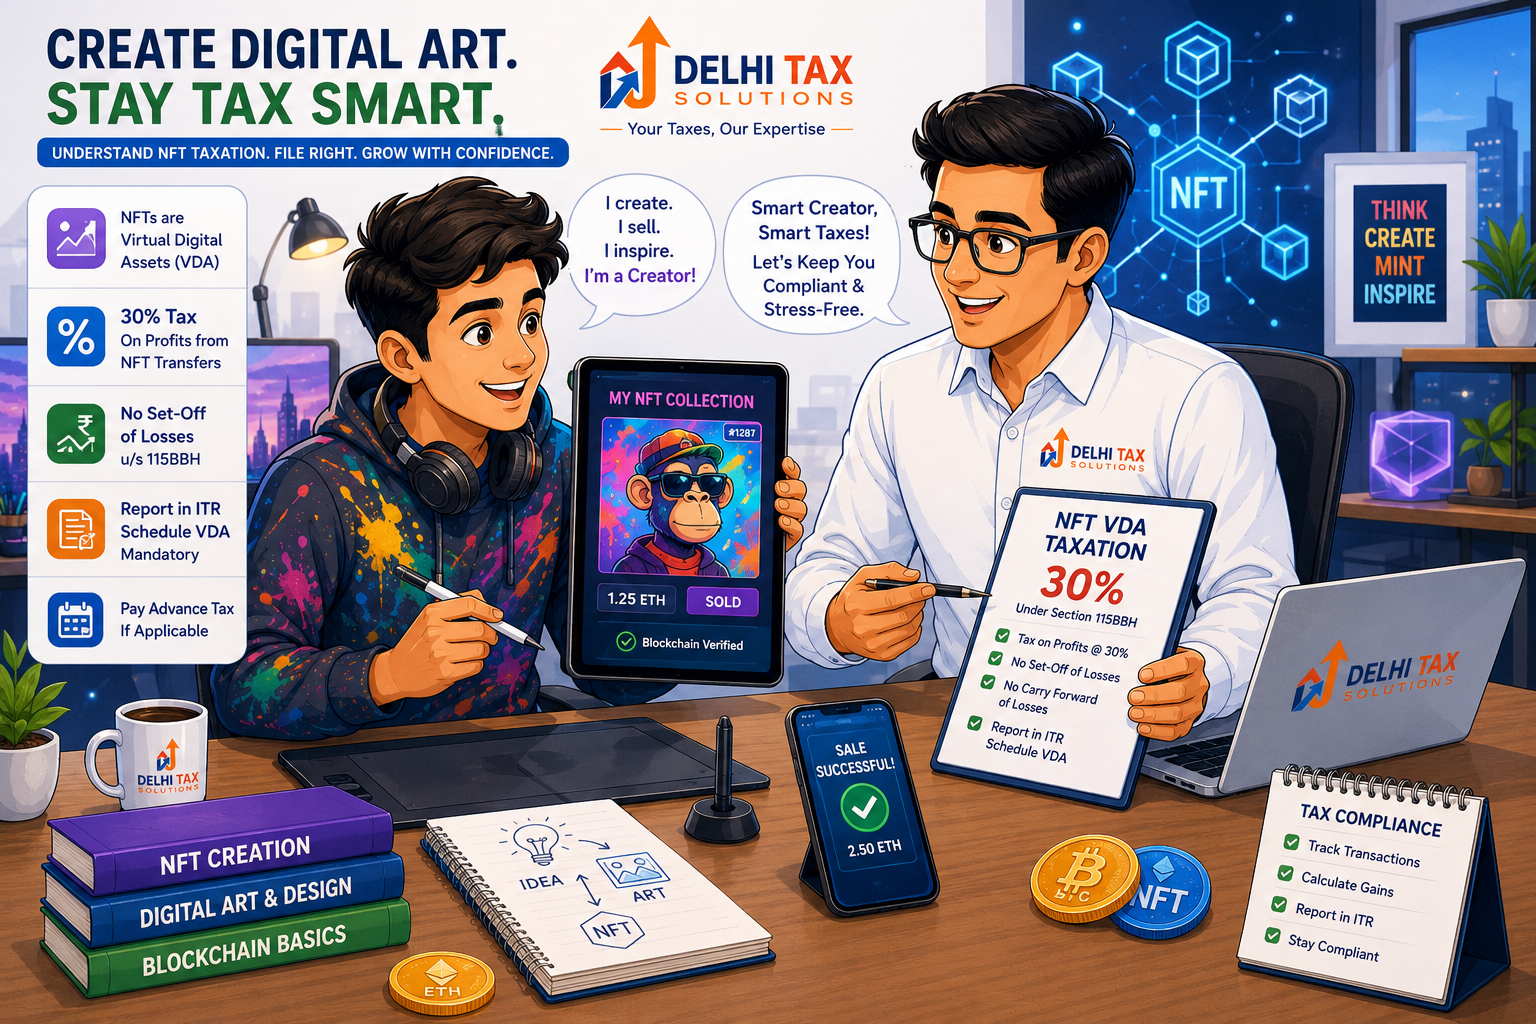
💡 Key Takeaways
- Non-Fungible Tokens are legally classified as Virtual Digital Assets under the Income Tax Act.
- Profits from selling digital collectibles attract a flat 30 percent tax rate.
- Buyers must deduct 1% TDS under Section 194S when purchasing high-value NFTs.
- Trading losses from digital assets cannot be set off against any other income streams.
- Expert Chartered Accountant filing ensures complete compliance and prevents tax scrutiny audits.
The digital creator economy in India has experienced massive growth, turning digital artwork, collectibles, and virtual real estate into high-value tradable assets. When artists and collectors start monetizing these unique tokens, tax compliance quickly becomes a top priority. Ignoring revenue reporting can lead to severe statutory penalties from tax authorities.
Understanding the nuances of NFT taxation India protects creators and investors from unexpected audit flags. The government enforces strict rules that govern every transfer, sale, and purchase of blockchain-backed assets. Whether you mint digital art or invest in marketplace tokens, knowing your fiscal obligations keeps your financial ledger clean and secure.
In this comprehensive guide, our chartered accountant advisory team breaks down asset classification, tax rates, withholding thresholds, and reporting procedures. Let us examine how these regulations impact your digital portfolio.
Are Non-Fungible Tokens Classified as Virtual Digital Assets?
Under Indian fiscal law, verifying whether an is NFT a virtual digital asset determination is straightforward. Parliament explicitly defined Non-Fungible Tokens within the scope of Virtual Digital Assets (VDAs) under Section 2(47A) of the Income Tax Act. Any information, code, number, or token generated through cryptographic means that possesses inherent utility or transferability qualifies as a VDA, regardless of whether it represents digital art, music, or virtual land.
This statutory classification means digital collectibles are subject to the same rigorous oversight as mainstream cryptocurrencies. Creators minting artwork and launching collections must maintain strict transaction records to comply with corporate structures, which often align with proper GST Registration protocols for commercial digital agencies.
What Is the Applicable Tax Rate on NFT Sales?
Calculating the tax on NFT sale transactions follows a strict statutory formula established by the central government. Any income generated from transferring a digital token is taxed at a flat rate of 30 percent under Section 115BBH. Taxpayers cannot deduct marketplace commissions, gas fees, minting costs, or internet expenses from their gross sale proceeds, with the sole exception being the actual acquisition cost.
Furthermore, trading losses incurred on one digital collectible cannot be set off against profits earned from another asset or normal business income. Ensuring accurate income calculations requires robust financial tracking, often supported by structured GST Registration Threshold guidelines for growing creative enterprises.
How Do NFT TDS Rules and Section 194S Operate?
Compliance extends beyond annual profit taxes to transaction-level withholding mechanisms. The implementation of NFT TDS rules under Section 194S mandates that any person buying a virtual digital asset must deduct 1% Tax Deducted at Source from the consideration amount. When transactions occur through organized marketplaces, the platform usually automates this deduction before crediting the seller.
An exemption limit of ₹50,000 per financial year applies to specified individuals and Hindu Undivided Families with low business turnover, while a ₹10,000 threshold applies to corporate entities. Verifying proper identity documentation via PAN Card Application processes is vital for seamless automated deductions on marketplace platforms.
Comparing Tax and Compliance Across Asset Classes
The fiscal treatment of digital collectibles diverges significantly from traditional physical art and standard financial securities. Understanding these structural divergences helps creators and collectors structure portfolios efficiently without triggering unintended penalties enforced by the Income Tax Department.
| Parameter | Non-Fungible Tokens (NFTs) | Physical Art & Real Estate |
|---|---|---|
| Tax Deduction (TDS) | 1% under Section 194S on transfers | Applicable on specific property sales only |
| Flat Tax Rate | 30% flat tax on net gains | 12.5% to 20% with indexation benefits |
| Loss Set-Off | Prohibited across all VDA categories | Permitted under capital gains rules |
As highlighted in official publications by the Press Information Bureau, government regulations treat digital assets distinctly to curb speculative leakages. Ensuring compliance aligns with broad strategic frameworks detailed on our Rules of Income Tax hub.
NAVIGATING ANNUAL ITR FILING AND VDA DISCLOSURES
Filing your annual Income Tax Return requires complete transparency regarding digital asset activities. Taxpayers must report every individual token transfer in Schedule VDA, detailing purchase dates, sale proceeds, and acquisition costs. Even though trading losses yield a net zero set-off impact, failing to disclose transactions accurately can trigger automated scrutiny notices from the Centralized Processing Center.
Cross-referencing marketplace transaction histories with Form 26AS ensures that your reported gains match government records. Maintaining detailed crypto ledger statements protects your business from unnecessary compliance audits and statutory fines.
⚡ In a Nutshell
NFTs are taxed at a flat 30% rate under Section 115BBH with 1% TDS deducted on transfers. Always disclose transactions accurately in Schedule VDA.
Conclusion and Next Steps for Digital Creators
Mastering NFT taxation India compliance is essential for any creator or investor participating in the digital economy. From tracking the flat 30% tax rate under Section 115BBH to managing 1% TDS deductions and Schedule VDA filings, meticulous attention to detail safeguards your venture from penalties.
Talk to a Delhi Tax Solutions expert to get your virtual asset tax computation and annual return filing handled with absolute professional precision. Connect with our dedicated CA advisory team today to protect your digital collections and ensure seamless regulatory compliance moving forward.
About this article: Researched using official government sources and Delhi Tax Solutions’ in-house tax advisory team. Last updated August 2026.
Frequently Asked Questions
+ Q: Are Non-Fungible Tokens (NFTs) officially classified as Virtual Digital Assets in India?
A: Yes, Non-Fungible Tokens are officially classified as Virtual Digital Assets under Section 2(47A) of the Income Tax Act. The statute encompasses any digital token, code, or cryptographic asset that is transferrable and has store of value or utility, regardless of whether it represents digital artwork, music, or virtual land. Consequently, all statutory compliance rules, tax rates, and reporting standards designed for virtual assets apply directly to NFT creators and traders across India.
+ Q: What is the applicable income tax rate on profits earned from selling an NFT in India?
A: Profits earned from the transfer of Non-Fungible Tokens are subject to a flat income tax rate of 30 percent under Section 115BBH of the Income Tax Act, plus applicable surcharges and cesses. When computing taxable gains, taxpayers are strictly prohibited from deducting expenses such as minting fees, gas costs, or marketplace commissions from the sale proceeds. Only the direct acquisition cost can be deducted, and any trading losses cannot be set off against these profits when filing returns through the Income Tax Department portal.
+ Q: Do peer-to-peer NFT transactions attract 1% TDS under Section 194S?
A: Yes, peer-to-peer NFT transactions attract 1% TDS compliance under Section 194S if the transaction value exceeds the statutory threshold limits of ₹50,000 for specified individuals or ₹10,000 for corporate entities per financial year. In direct wallet-to-wallet trades where no exchange platform mediates the sale, the buyer assumes legal responsibility for withholding 1% of the consideration and depositing it with the government using appropriate challans to ensure full regulatory adherence.
+ Q: Can losses incurred from trading NFTs be set off against other capital gains?
A: No, trading losses incurred from the transfer of Non-Fungible Tokens cannot be set off against any other income streams, including profits from stocks, mutual funds, real estate, or other virtual digital assets. The tax framework isolates VDA losses completely, meaning negative trading balances cannot reduce your tax liability or be carried forward to subsequent assessment years, requiring creators and investors to manage portfolio risks carefully.
+ Q: How should creators and investors report NFT transactions when filing their annual ITR?
A: When filing your annual Income Tax Return, you must report all digital collectible transfers within the dedicated Schedule VDA section. Taxpayers must provide transaction-level particulars including purchase dates, marketplace identifiers, sale proceeds, and acquisition costs. Disclosing these details accurately ensures that your Form 26AS matches your tax filings, preventing automated discrepancy notices and scrutiny audits from tax authorities.
