
💡 Key Takeaways
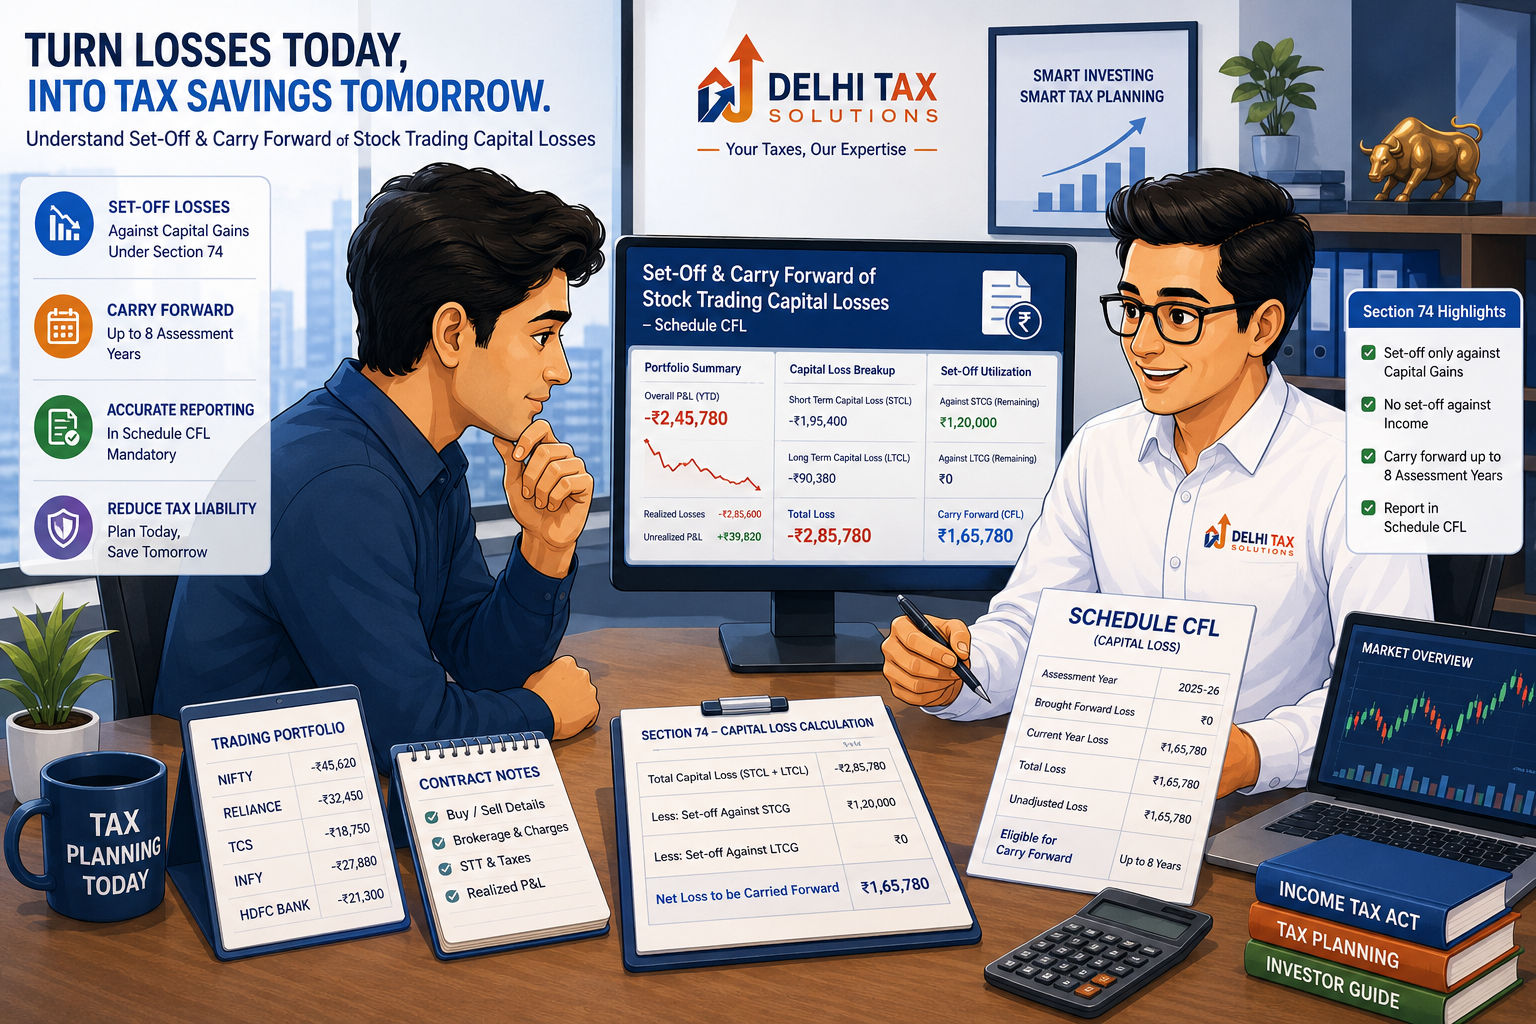
- Short-term capital losses offset both short-term and long-term capital gains effortlessly.
- Long-term capital losses can only offset long-term capital gains under tax rules.
- Unabsorbed losses require timely ITR filing to carry forward up to 8 years.
- Schedule CFL in ITR-3 mandates meticulous reporting of all trading red ink.
- Professional chartered accountant guidance prevents costly reporting errors during filing season.
Experiencing red figures in equity markets is an unavoidable reality for active investors. Mastering how to set off capital losses stock trading ensures that poor investment quarters do not result in inflated tax outlays. When market volatility strikes, knowing statutory adjustment mechanisms protects hard-earned capital.
Every trader must understand that revenue authorities permit offsetting losses against profitable trades within the same financial year. Whether you trade delivery shares or equity derivatives, proper documentation transforms trading setbacks into legitimate tax shields. Taxpayers need to track every transaction meticulously to compute accurate net gains.
In this expert advisory guide, our chartered accountant team outlines Section 74 provisions, holding period classifications, and ITR reporting schedules. Let us examine how equity loss adjustments operate across Indian financial markets.
How Do Equity Loss Set-Off Mechanisms Function in India?
When analyzing how to set off capital losses stock trading standards, investors must recognize that losses incurred on the sale of listed equity shares or equity mutual funds are categorized based on holding periods. Under Section 74 income tax act provisions, STCG loss set off rules dictate that short-term capital losses resulting from assets held for under 12 months can offset both short-term capital gains and long-term capital gains.
Ensuring proper compliance across all financial transactions safeguards personal portfolios, much like maintaining rigorous corporate records during GST Registration for commercial ventures.
What Is the Difference Between Short-Term and Long-Term Loss Adjustments?
Mastering short term vs long term loss set off requirements involves understanding strict statutory boundaries. While short-term losses offer versatile adjustment flexibility, LTCG loss set off rules restrict long-term capital losses—incurred on equity held beyond 12 months—exclusively to long-term capital gains. Investors holding valid identification credentials through a verified PAN Card Application ensure seamless tax credit mapping.
According to operational guidelines issued by the Income Tax Department, failing to segregate these holding periods correctly invites statutory interest penalties.
How Can Unabsorbed Losses Be Carried Forward for Eight Years?
Filing accurate returns requires understanding provisions that permit investors to carry forward capital loss 8 years when losses cannot be fully absorbed within the current financial year. Reporting exact figures ensures alignment with automated tax servers that cross-reference data against Rules of Income Tax compliance benchmarks. Omission of these unabsorbed figures forfeits future tax benefits.
Taxpayers can offset these carried-forward losses against future gains by strictly adhering to the return filing due date 31 july benchmark every assessment cycle.
How Do You Report Trading Losses in the ITR Schedule CFL?
Navigating capital loss ITR schedule CFL reporting means recognizing that income tax software requires precise data entry across the ITR-3 capital gains schedule. Taxpayers must explicitly report both intra-day and delivery-based losses in Schedule CFL before the electronic return validates successfully. High-volume traders facing frequent red numbers must reconcile contract notes thoroughly.
| Loss Classification | Eligible Set-Off Source | Carry Forward Limit |
|---|---|---|
| Short-Term Capital Loss | Both STCG and LTCG | 8 Assessment Years |
| Long-Term Capital Loss | Only LTCG Payouts | 8 Assessment Years |
As highlighted in fiscal reports published by the Press Information Bureau, tax administration mechanisms continue utilizing digital verification trails to monitor high-frequency trading disclosures.
What Are the Specific Rules for Intra-Day and Speculative Losses?
Evaluating intra-day trading loss set off principles reveals that speculative business losses follow completely different statutory rules compared to capital losses. Speculative losses can only be offset against speculative profits and carried forward for just 4 years. Investors must distinguish between investment delivery trades and speculative day-trading to prevent erroneous schedule grouping.
Maintaining proper compliance across commercial entities prevents regulatory bottlenecks, aligning with turnover criteria specified in official GST Registration Threshold publications.
Why Is Timely ITR Filing Mandatory for Carrying Forward Losses?
Executing equity loss set off rules 2026 mandates strict adherence to statutory filing timelines. Under the Income Tax Act, unabsorbed losses cannot be carried forward unless the taxpayer files their annual return on or before the due date specified under Section 139(1). Missing this deadline forfeits the legal right to claim loss carry-forward benefits in subsequent years.
According to advisory reviews conducted by our CA team, reconciling brokerage statements before filing deadlines ensures absolute compliance confidence.
⚡ In a Nutshell
Stock trading capital losses must be reported in Schedule CFL and filed by July 31 to carry forward unabsorbed losses for up to 8 years.
Conclusion and Next Steps for Stock Market Investors
Understanding the rules governing how to set off capital losses stock trading empowers investors to manage their equity portfolios efficiently. From monitoring Section 74 holding periods to reporting unabsorbed red ink in Schedule CFL, proactive compliance protects wealth from unnecessary tax outlays.
Talk to a Delhi Tax Solutions expert to get your capital loss ITR filing managed with professional precision. Connect with our dedicated chartered accountant advisory team today to secure your financial standing and eliminate compliance risks.
About this article: Researched using official government sources and Delhi Tax Solutions’ in-house tax advisory team. Last updated August 2026.
Frequently Asked Questions
+ Q: How can I set off capital losses from stock trading against my profits?
A: Capital losses incurred from stock trading can be set off against taxable capital gains within the same financial year under Section 74 of the Income Tax Act. Short-term capital losses can offset both short-term and long-term gains, whereas long-term capital losses can only offset long-term gains. Taxpayers must compile all brokerage contract notes and report net figures correctly via the Income Tax Department portal during annual return filing.
+ Q: Can long-term capital losses be offset against short-term capital gains?
A: No, under strict statutory rules governed by Section 74 of the Income Tax Act, long-term capital losses resulting from equity shares held for more than 12 months cannot be set off against short-term capital gains. Long-term losses are strictly restricted to offsetting long-term capital gains only. However, unabsorbed long-term losses can be carried forward for up to 8 assessment years provided the return is filed within the statutory due date.
+ Q: What is the time limit to carry forward capital losses under Section 74?
A: Unabsorbed capital losses from stock trading can be carried forward for a maximum period of 8 consecutive assessment years immediately succeeding the financial year in which the loss was incurred. To preserve this legal right, taxpayers must file their income tax returns strictly on or before the due date specified under Section 139(1). Partnering with professional chartered accountants at Delhi Tax Solutions ensures flawless compliance tracking and timely filing.
+ Q: How do I report stock trading capital losses in ITR Schedule CFL?
A: Taxpayers must report all unabsorbed short-term and long-term capital losses in Schedule CFL of ITR-3 or ITR-2 depending on their business classification. Schedule CFL acts as the master summary table where losses are declared so that tax servers can automatically track and carry them forward into subsequent assessment years. Accurate data entry prevents automated discrepancy notices and protects future tax adjustment claims.
+ Q: Is filing the income tax return by the due date mandatory to carry forward losses?
A: Yes, filing the income tax return on or before the statutory due date (typically July 31 for non-audit individual taxpayers) is absolutely mandatory under Section 80 read with Section 74. If a taxpayer files a belated return, the income tax portal legally disallows the carry forward of capital losses, resulting in the permanent loss of valuable tax relief. Timely filing safeguards your financial interests.
