
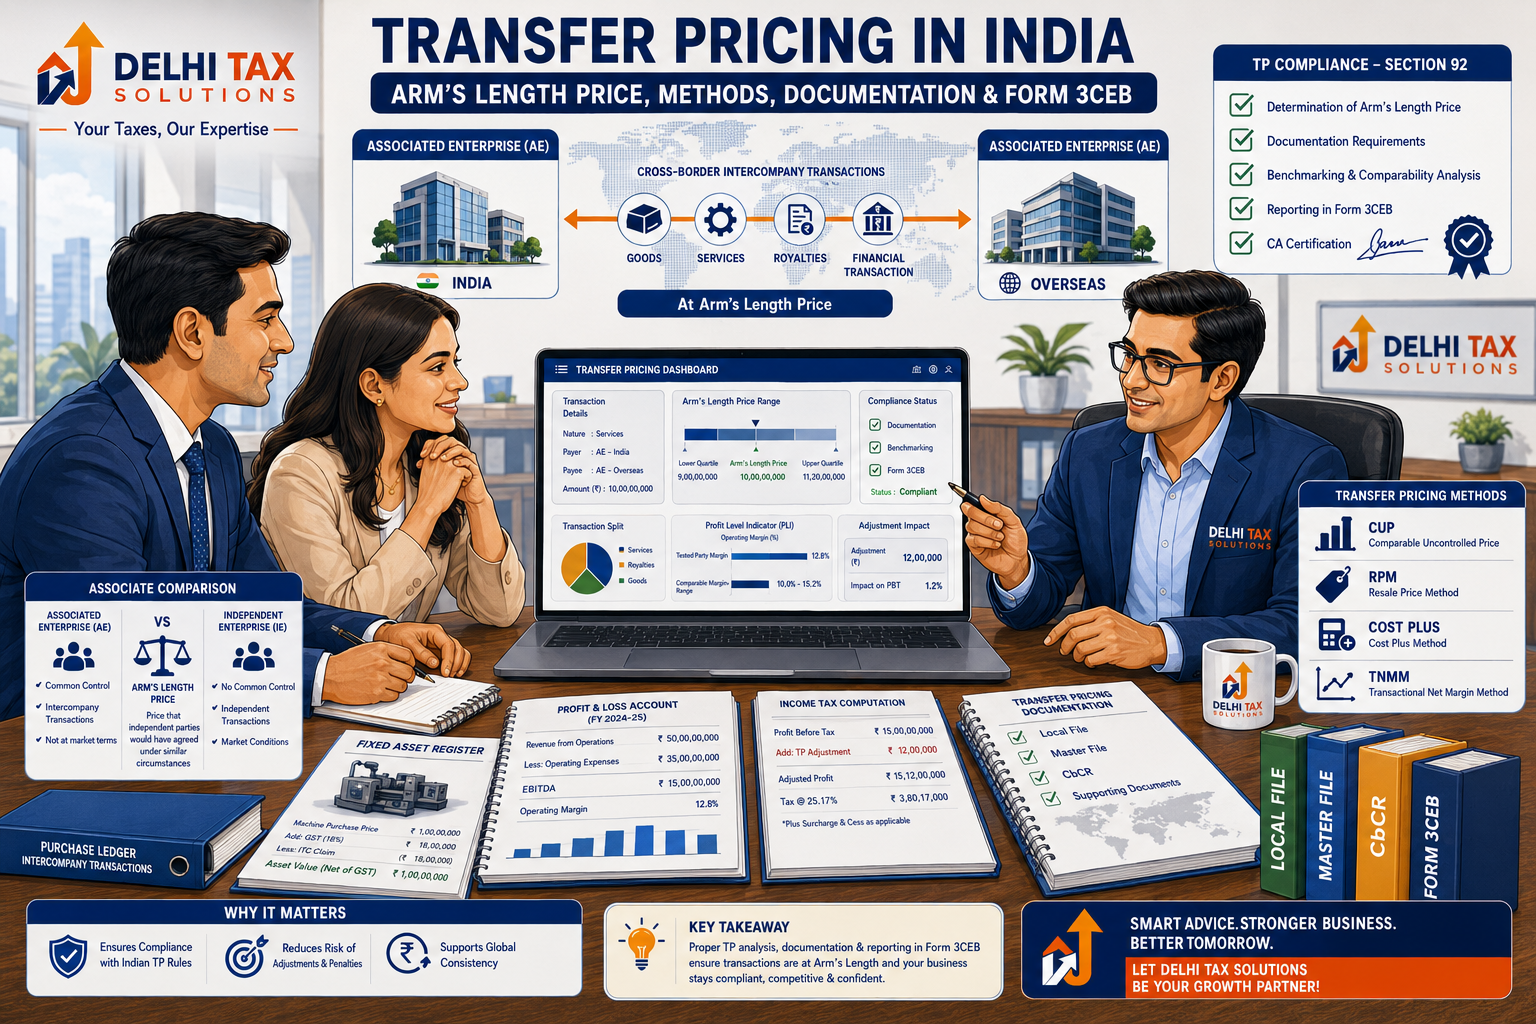
? Key Takeaways
- Transfer pricing ensures cross-border transactions between group entities follow fair market value standards.
- All international transactions must be benchmarked using recognized arm’s length pricing methods.
- Comprehensive documentation including local and master files is mandatory for eligible enterprises.
- Form 3CEB must be certified by a chartered accountant for financial reporting compliance.
- Strict statutory penalties apply for failing to maintain required transfer pricing records.
Operating a multinational enterprise requires managing complex cross-border financial flows between associated entities. Understanding transfer pricing basics India regulations is essential for foreign corporations and Indian subsidiaries seeking to prevent double taxation and aggressive tax scrutiny. When associated enterprises trade goods, services, or intellectual property across borders, tax authorities examine whether these transactions reflect true market conditions.
Navigating international taxation mandates requires careful adherence to direct tax statutes and compliance schedules. Establishing compliant corporate structures involves aligning your internal accounting policies with provisions enforced by the Income Tax Department. Business owners scaling operations across commercial centers in Delhi NCR must manage these obligations alongside standard Income Tax filings, Company Registration procedures, and TDS deductions.
This authoritative advisory guide explores statutory pricing methods, mandatory documentation rules, and audit thresholds for multinational corporations operating in India.
What is transfer pricing and why is it important in India?
Transfer pricing refers to the pricing of goods, services, intangible assets, or financial transactions between connected or related enterprises under common control. In India, Section 92 of the Income-tax Act mandates that any income arising from an international transaction between associated enterprises must be computed on the basis of the arm’s length price. Official updates published by the Press Information Bureau highlight that these regulations protect the Indian tax base from profit shifting to low-tax jurisdictions. Without strict oversight, multinational groups could manipulate internal pricing to minimize their domestic tax liabilities.
How is the arm’s length price determined for transactions?
Applying the correct arm’s length price transfer pricing methodology ensures cross-border transactions withstand regulatory scrutiny. Regulatory frameworks monitored by the Reserve Bank of India and tax statutes recognize several prescribed methods to determine fair market value. These methods evaluate transactions by comparing prices charged between unrelated parties under similar circumstances.
Comparable Uncontrolled Price method
The Comparable Uncontrolled Price (CUP) method compares the price charged for property or services in a controlled transaction to the price charged in a comparable uncontrolled transaction between independent parties.
Transactional net margin method
The Transactional Net Margin Method (TNMM) examines the net profit margin relative to an appropriate base realized by an enterprise from associated transactions.
| Pricing Method | Core Evaluation Focus | Typical Business Application |
|---|---|---|
| Comparable Uncontrolled Price (CUP) | Direct price comparison with third parties | Commodities, standardized goods, and loans |
| Resale Price Method (RPM) | Resale margin minus gross profit mark-up | Distributors buying from foreign parents |
| Cost Plus Method (CPM) | Costs incurred plus an appropriate profit mark-up | Contract manufacturing and software services |
| Transactional Net Margin Method (TNMM) | Net profit margin relative to an operating base | General service providers and assembly units |
? Quick Summary
Arm’s length pricing requires transactions between associated enterprises to mirror fair market value using one of several statutory valuation methods.
What are the transfer pricing documentation requirements?
Meeting transfer pricing documentation requirements is a legal obligation for multinational enterprises operating in India. Oversight norms administered by the Ministry of Corporate Affairs require eligible entities to maintain robust information sets detailing their international dealings. This documentation substantiates that transactions comply with arm’s length principles.
Maintaining local and master files
Multinational groups must maintain a Master File containing standardized information regarding the global business operations and a Local File detailing specific transactions of the Indian entity.
Country-by-Country reporting
Large enterprise groups with consolidated global turnover exceeding prescribed financial thresholds must also file Country-by-Country Reports (CbCR) detailing global revenue and tax allocations.
When does a transfer pricing audit apply in India?
Executing statutory compliance involves understanding when a transfer pricing audit India review becomes mandatory. According to tax advisory cases handled by our CA team at Delhi Tax Solutions, any enterprise entering into international transactions must obtain a specialized accountant report in Form 3CEB. This report must be certified by a qualified chartered accountant and filed electronically.
Filing Form 3CEB certification
Form 3CEB details all international transactions, the pricing methods applied, and the arm’s length analysis undertaken by the taxpayer during the financial year.
Reference to the Transfer Pricing Officer
During tax scrutiny, assessing officers can refer complex international transactions to a specialized Transfer Pricing Officer (TPO) for detailed investigation and potential adjustments.
Why compliance with international tax standards matters.
Maintaining strict adherence to direct tax reporting standards protects businesses from severe penalties and prolonged litigation. Our CA advisory team at Delhi Tax Solutions helps multinational corporations structure their intercompany agreements and manage annual compliance seamlessly alongside other regulatory filings like GST Registration.
Talk to a Delhi Tax Solutions expert to get your transfer pricing documentation and statutory filings managed seamlessly today.
About this article: Researched using official government sources and Delhi Tax Solutions’ in-house tax advisory team. Last updated August 2026.
This article is for general informational purposes and is not a substitute for personalised professional tax advice.
Frequently Asked Questions (FAQs)
Q: What is transfer pricing and why is it important in India?
A: Transfer pricing governs the pricing of transactions between related business entities across international borders. In India, under Section 92 of the Income-tax Act, these rules are vital because they prevent multinational corporations from artificially shifting profits to low-tax jurisdictions, ensuring that fair market tax is paid on income generated within the domestic economy.
Q: How is the arm’s length price determined under Indian tax laws?
A: The arm’s length price is determined by applying one of several statutory pricing methods recognized by the Income Tax Department, such as the Comparable Controlled Price method, Resale Price method, Cost Plus method, or Transactional Net Margin method. These methods evaluate transactions by comparing commercial terms against independent third-party dealings.
Q: What are the mandatory transfer pricing documentation requirements in India?
A: Eligible enterprises undertaking international transactions must maintain comprehensive documentation, including a Master File detailing global business structures, a Local File recording specific intercompany transactions, and financial backup. Furthermore, qualifying multinational groups must also submit Country-by-Country Reports to satisfy regulatory transparency standards.
Q: When is a transfer pricing audit required for multinational enterprises?
A: A specialized transfer pricing audit review is triggered whenever an enterprise engages in international transactions with associated entities during a financial year. Taxpayers must furnish an accountant report in Form 3CEB, certified by a qualified chartered accountant, detailing all cross-border dealings alongside their annual income tax returns.
Q: What are the penalties for non-compliance with transfer pricing regulations?
A: Failing to maintain required documentation or neglecting to furnish the accountant report in Form 3CEB attracts heavy statutory penalties under the Income-tax Act. Specifically, non-reporting of international transactions or failure to keep prescribed records can lead to fines amounting to 2% of the value of international transactions.
