
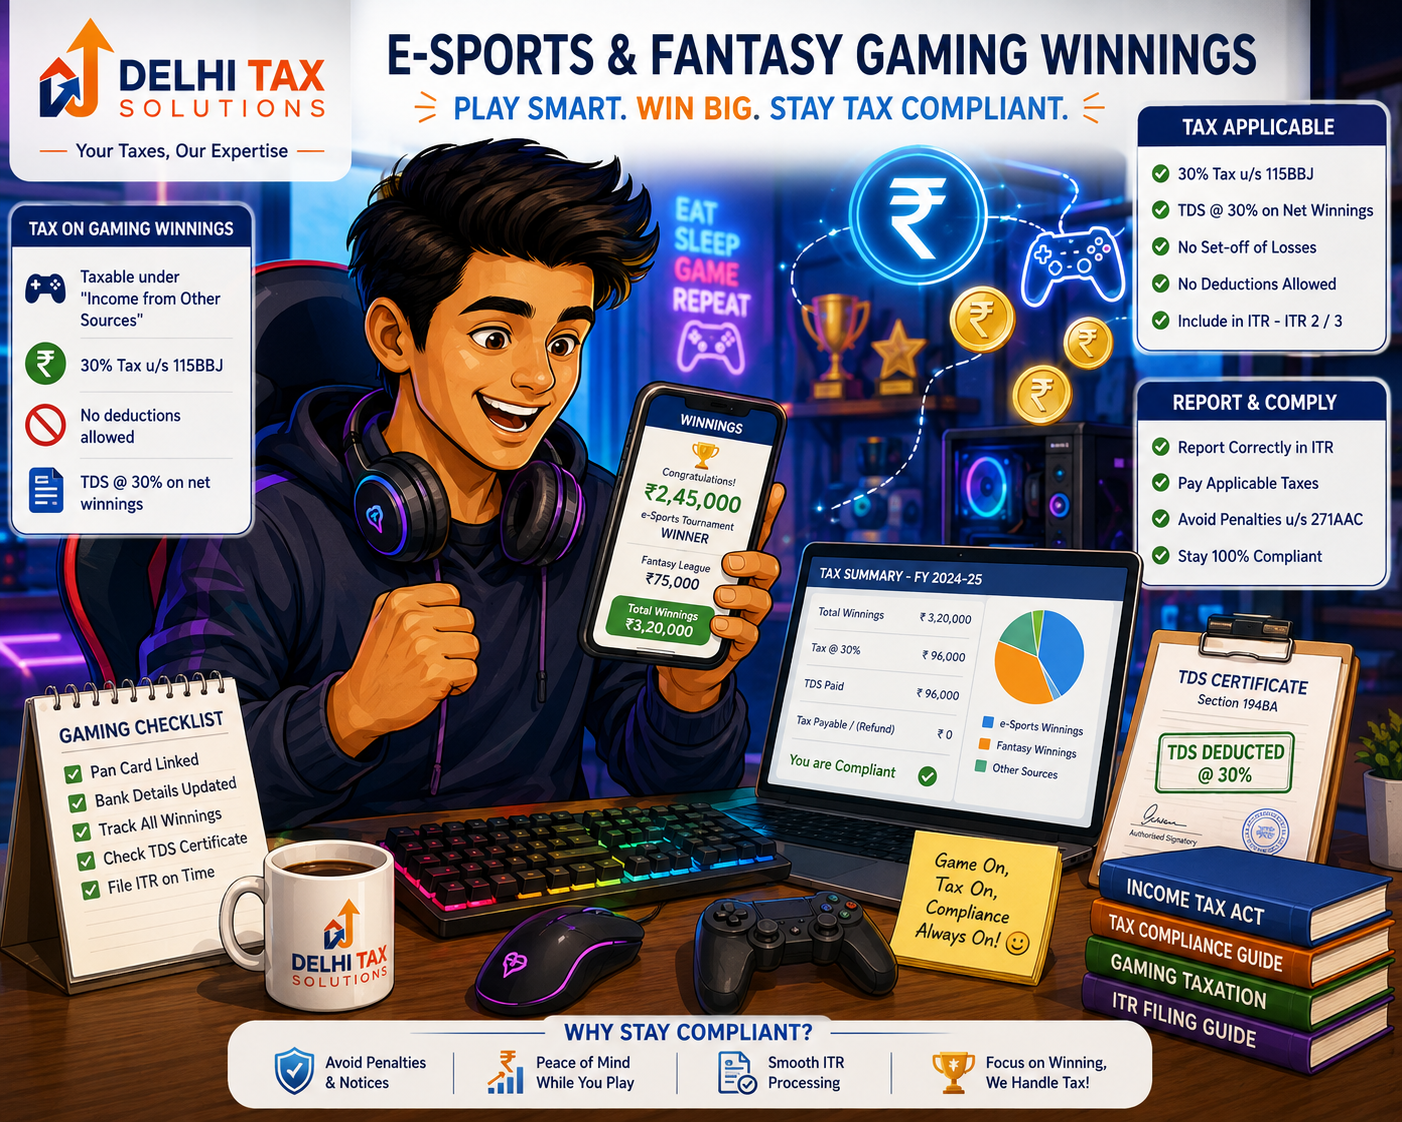
💡 Key Takeaways
- A flat 30% tax applies to all online gaming net winnings under Section 115BBJ.
- TDS under Section 194BA triggers on every withdrawal, with a ₹0 minimum threshold.
- The standard ₹3 Lakh basic exemption limit does not apply to gaming profits.
- Gaming losses cannot be set off against regular income or carried forward.
- Gross winnings must be reported in Schedule OS using Form ITR-2 or ITR-3.
India’s online real-money gaming sector processes billions of rupees annually, drawing intense scrutiny from the Central Board of Direct Taxes. Taxpayers earning money from fantasy sports, rummy, or e-sports must now navigate strict tax compliance. The primary rules surrounding TDS on online gaming winnings dictate exactly how much money actually hits your bank account after a victory.
This guide explains the precise mechanics of Section 115BBJ and Section 194BA of the Income Tax Act. You will learn the formula to calculate your net taxable amount and how to declare these earnings correctly in your annual returns. With the introduction of the Promotion and Regulation of Online Gaming Act in 2025, regulatory oversight has tightened significantly.
Ignorance of these laws triggers severe penalties. Gamers often assume small withdrawals escape the tax net, but the law states otherwise. Read on to master the rules, secure your winnings, and file your taxes flawlessly.
What is the rule for TDS on online gaming winnings?
The rule for TDS on online gaming winnings mandates a strict 30% tax deduction under Section 194BA of the Income Tax Act. Gaming platforms must deduct this tax at the time of user withdrawal or at the end of the financial year. Unlike traditional lotteries, there is no minimum threshold. Every rupee of net winnings is subject to this 30% deduction, ensuring immediate tax compliance before funds reach the gamer’s bank account.
Understanding Section 115BBJ and Section 194BA of the Income Tax Act
Tax Deducted at Source (TDS) ensures the government collects revenue instantly rather than waiting for annual tax filings. The government introduced two specific sections to tax the booming gaming industry effectively. Section 115BBJ dictates the tax rate, while Section 194BA governs the actual platform deduction process.
Section 115BBJ imposes a flat 30% tax on net winnings from online games. Gamers cannot claim basic exemption limits against this income. Earning less than the standard ₹3 Lakh exemption limit in FY 2025-26 does not protect your gaming profits. You also cannot deduct internet costs or hardware expenses against this income bracket.
Section 194BA places the compliance burden directly on gaming platforms. The Income Tax Department’s ITR-6 validation rules mandate reporting online gaming winnings separately under Schedule OS. Platforms must calculate the net winnings of every user and withhold 30% before processing a payout. The CBDT integrated specific tags for Section 194BA in the official e-Filing schema updates, forcing strict compliance.
The PROG Act impact
Under the Promotion and Regulation of Online Gaming (PROG) Act, 2025, platforms must differentiate between skill-based e-sports and real-money gaming. Only registered real-money platforms fall under the stringent 194BA online gaming TDS framework. Founders launching gaming startups must secure their Company Registration accurately to designate their platform type.
How to calculate online gaming tax net winnings?
Calculating exact profits determines the actual TDS liability for any gamer. Rule 133 of the Income Tax Rules outlines a specific formula for calculating online gaming tax net winnings. Platforms apply this formula at withdrawal and at the financial year-end (March 31).
The formula is: (Amount Withdrawn + Closing Balance) – (Opening Balance + Total Deposits). Non-taxable deposits include actual cash added by the user. Promotional bonuses or referral credits provided by the platform do not count as user deposits. Taxpayers running platforms must ensure their portal complies with TDS regulations before allowing withdrawals.
Example of Net Winnings Calculation
Assume a gamer starts FY 2025-26 with a ₹1,000 opening balance, deposits ₹5,000, and withdraws ₹4,000 in December. The closing balance on March 31 is ₹3,000. Net winnings equal (4,000 + 3,000) – (1,000 + 5,000) = ₹1,000. The platform deducts 30% TDS on this ₹1,000 profit.
| Component | Amount (₹) | Impact on Net Winnings Formula |
|---|---|---|
| Opening Balance | 1,000 | Deducted from total value |
| Total Deposits | 5,000 | Deducted from total value |
| Withdrawals | 4,000 | Added to total value |
| Closing Balance | 3,000 | Added to total value |
| Net Taxable Winnings | 1,000 | Subject to 30% TDS |
⚡ Quick Summary
Net winnings represent pure profit. You only pay tax on the actual money you win, not the capital you deposited into the gaming wallet.
Tax on lottery winnings India vs online gaming: Key differences
Many taxpayers confuse digital gaming rules with traditional betting laws. Both attract a 30% tax rate, but the compliance mechanisms differ significantly. Section 115BB covers traditional lotteries, crossword puzzles, and horse races.
The tax on lottery winnings India utilizes Section 194B for TDS deductions, providing a ₹10,000 threshold limit per financial year. Lottery winners receiving ₹9,000 face zero TDS, though the income itself remains taxable eventually.
Online gaming removed this threshold entirely starting in 2023. A gamer withdrawing ₹100 of pure profit immediately faces a ₹30 TDS cut. Managing your Income Tax properly requires understanding these distinct categories.
Operational compliance for platforms
Gaming operators must track real-time wallet balances across millions of users daily. They also face complex GST Registration requirements for handling user funds. A 28% Goods and Services Tax (GST) applies to the full face value of bets placed on real-money apps.
Does 194BA online gaming TDS apply to casual gamers and professionals?
Tax laws do not differentiate between casual weekend players and professional e-sports athletes. If you play real-money games, the TDS on online gaming winnings applies uniformly. Professional gamers often attempt to classify this income as business profits to claim expense deductions, but Section 115BBJ strictly overrides this.
Even if gaming is your full-time profession, the 30% tax is absolute and unadjustable. The Income Tax Act prohibits claiming internet bills or entry fees as business expenses against Section 115BBJ income. Our CA team at Delhi Tax Solutions frequently sees taxpayers attempting to claim losses incorrectly.
Setting off gaming losses
You cannot set off gaming losses against regular business income or salary. You also cannot carry forward gaming losses to the next financial year (AY 2026-27). You must report all gross winnings accurately in your Income Tax Return (ITR).
Filing ITR: Declaring your gaming and lottery earnings
Taxpayers must report gaming income under “Income from Other Sources”. Form ITR-2 or ITR-3 applies to individuals with gaming profits. Form ITR-1 (Sahaj) does not support Section 115BBJ income reporting.
You must disclose the exact TDS on online gaming winnings deducted by the platform. The platform issues a Form 16A detailing the tax withheld. This amount reflects in your Annual Information Statement (AIS) automatically. Always verify your Form 26AS before filing by the July 31 deadline.
Mismatches trigger automatic scrutiny notices. The Central Board of Direct Taxes requires precise compliance. If the TDS deducted exceeds your final tax liability because of other factors, you cannot claim a refund on the 30% tax paid on gaming net winnings itself. The tax on gaming is definitive and final.
The financial year 2025-26 demands strict adherence to gaming tax laws. Remember, a flat 30% tax applies to all net profits without basic exemption benefits. The removal of the TDS threshold means every profitable withdrawal triggers immediate tax deduction. Furthermore, gaming losses cannot offset other income or carry forward.
Talk to a Delhi Tax Solutions expert to get your ITR filed correctly before the July 31 deadline. Do not risk penalties for undeclared gaming profits. As the regulatory framework tightens under new IT rules, professional guidance ensures your winnings stay secure.
About this article: Researched using official government sources and Delhi Tax Solutions’ in-house tax advisory team. Last updated August 2026.
This article is for general informational purposes and is not a substitute for personalised professional tax advice.
Frequently Asked Questions (FAQs)
Q: What is the minimum threshold limit for TDS on online gaming winnings?
A: There is absolutely no minimum threshold limit for TDS on online gaming winnings under Section 194BA of the Income Tax Act. Prior to 2023, a ₹10,000 threshold existed, but the government removed it to widen the tax net. Now, even if your net winnings are just ₹100, the gaming platform must deduct a flat 30% tax before processing your withdrawal to your bank account.
Q: Can I claim my gaming losses against my regular business income in India?
A: No, you cannot claim or set off gaming losses against any other head of income, including salary, business profits, or house property. The Income Tax Act treats online gaming as a special speculative category under Section 115BBJ. Furthermore, you are not allowed to carry forward these losses to the next financial year (AY 2026-27). If you lose ₹5,000 in one app and win ₹10,000 in another, you cannot net them against each other across different platforms.
Q: How is the tax on lottery winnings India different from online gaming tax?
A: The tax on lottery winnings India falls under Section 115BB and utilizes Section 194B for TDS deductions, which specifically includes a ₹10,000 threshold limit. If you win ₹9,000 in a physical lottery, no TDS is deducted. Conversely, online gaming falls under Section 194BA and Section 115BBJ, which carry zero threshold. Every single rupee of net winnings from a digital gaming platform faces immediate 30% TDS upon withdrawal.
Q: Which ITR form should I use to declare 194BA online gaming TDS?
A: You must use either Form ITR-2 or Form ITR-3 to declare your 194BA online gaming TDS and associated winnings. Form ITR-1 (Sahaj) cannot be used if you have income under Section 115BBJ. You must report these earnings specifically under the “Income from Other Sources” (Schedule OS) section. Always ensure that the gaming income you declare perfectly matches the figures reflected in your Form 26AS and Annual Information Statement.
Q: Does the ₹3 Lakh basic exemption limit apply to online gaming tax net winnings?
A: No, the standard ₹3 Lakh basic exemption limit under the new tax regime (FY 2025-26) does not apply to online gaming tax net winnings. Section 115BBJ applies a strict, flat 30% tax rate on this specific income. Even if your total annual income from all sources is only ₹2 Lakhs, you still have to pay the 30% tax on whatever gaming profits you earned during that financial year.
