
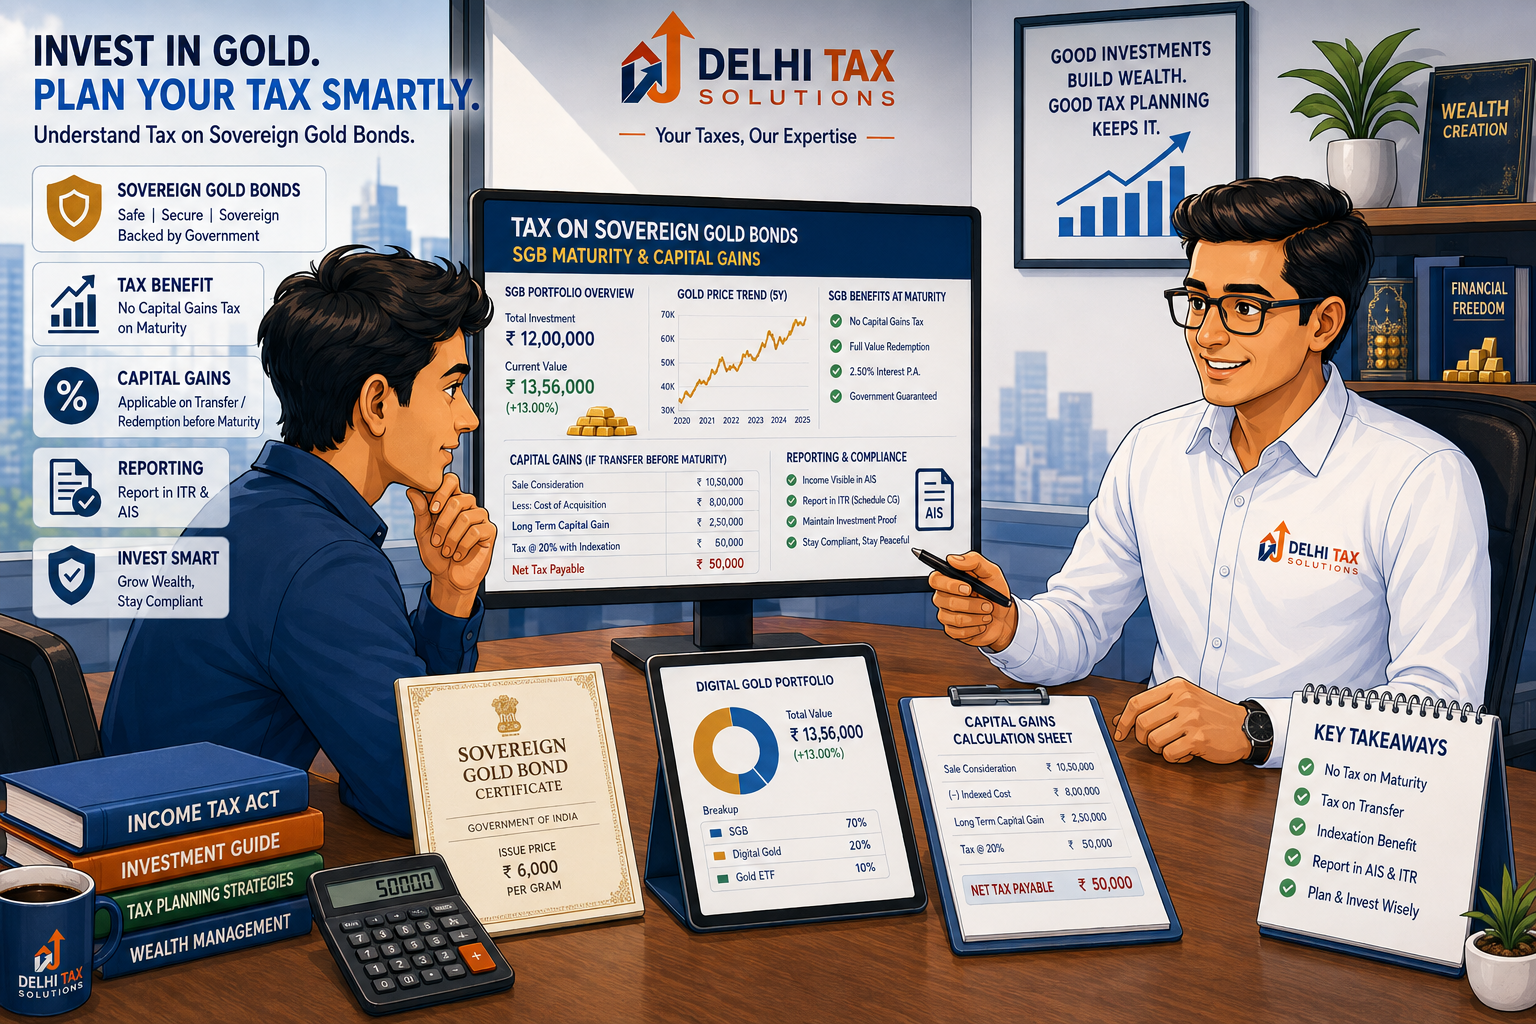
💡 Key Takeaways
- SGB maturity proceeds are fully exempt from capital gains tax for individual investors.
- Interest earned on Sovereign Gold Bonds is taxable under “Income from Other Sources.”
- Physical gold attracts Long Term Capital Gains (LTCG) tax upon sale after 24 months.
- Holding gold jewellery incurs specific tax rules upon sale based on acquisition and inflation indexing.
- Expert tax planning maximizes returns by selecting the most efficient gold investment vehicle.
Gold holds a revered status across Indian households, serving as a cultural anchor and a reliable store of wealth. Whether you keep gold as traditional jewellery, physical bars, or modern digital securities, every asset class carries distinct fiscal responsibilities. If you want to optimize your investment portfolio for the current Tax Year, understanding the nuances of the tax on sovereign gold bonds India is essential. Unlike holding physical bullion, Sovereign Gold Bonds (SGBs) provide unique statutory advantages that dramatically reduce your overall tax burden. Investors frequently choose SGBs to eliminate storage risks and locker fees while enjoying periodic interest payouts. However, navigating the intersection of capital gains, interest reporting, and compliance requires absolute precision.
Navigating these financial rules requires meticulous attention to detail. Missing a reporting deadline or misclassifying your investment returns can trigger unnecessary scrutiny from tax authorities. Based on cases handled by our CA team at Delhi Tax Solutions, investors often overlook how maturity redemptions differ from secondary market sales. This guide breaks down the statutory provisions, calculation methods, and reporting standards you need to master.
What Is the Tax on Sovereign Gold Bonds in India?
The tax on sovereign gold bonds India is specifically engineered by the central government to promote digital financial savings and curb physical gold imports. Sovereign Gold Bonds are government securities denominated in grams of gold, issued by the Reserve Bank of India on behalf of the Government of India. When you purchase these instruments, you receive a guaranteed fixed interest rate of 2.5% per annum, credited semi-annually to your registered bank account. This interest income is fully taxable under the head “Income from Other Sources” according to your applicable income tax slab rate. However, the core financial appeal of SGBs lies in their redemption mechanism. If you hold these bonds until their eight-year maturity, the capital gains realized by individuals are entirely tax-exempt. This provides a stark contrast to traditional physical gold investments.
How Does SGB Maturity Tax Exemption Benefit Investors?
The SGB maturity tax exemption represents one of the most powerful wealth-preserving provisions available to Indian taxpayers. Under Section 47(vii)(c) of the Income-tax Act, 1961, the redemption of SGBs by an individual upon maturity is explicitly excluded from being classified as a “transfer.” Consequently, zero capital gains tax applies when the government redeems your bond after eight years. This means the entire price appreciation in gold value remains completely untaxed in your hands. Compare this with selling physical gold bars, where you must calculate and pay capital gains tax regardless of how long you held them. By opting for SGBs, you eliminate capital gains leakage entirely at maturity. For business owners and entrepreneurs focusing on enterprise growth alongside personal wealth, coordinating these investments with proper Company Registration and corporate tax planning ensures comprehensive financial health.
How Does Physical Gold Capital Gains Tax Compare?
When you hold physical gold in the form of bars, coins, or ornaments, you operate under a completely different tax regime. The physical gold capital gains tax is triggered whenever you liquidate your physical holdings for a profit. If you hold physical gold for 24 months or less, any profit is treated as Short-Term Capital Gains (STCG) and added directly to your taxable income, taxed at your applicable slab rate. If you hold physical gold for more than 24 months, it qualifies as a Long-Term Capital Asset. According to recent guidelines published by the Income Tax Department, long-term gains on physical gold are subject to applicable LTCG tax rates. SGBs completely bypass this tax burden at maturity, making them vastly superior for long-term capital retention.
| Asset Category | Holding Period Rule | Tax Treatment at Exit |
|---|---|---|
| Sovereign Gold Bonds (Maturity) | Full 8-Year Tenure | 100% Tax-Exempt for Individuals |
| Physical Gold (Long-Term) | Exceeding 24 Months | LTCG Tax Applicable on Gains |
| SGBs (Secondary Market Sale) | Traded on Stock Exchange | STCG or LTCG Based on Holding Duration |
What Are the Applicable Gold Jewellery Tax Rules?
Managing family jewellery requires understanding specific gold jewellery tax rules under Indian tax law. Jewellery is treated as a capital asset, meaning its sale attracts capital gains tax. When you sell gold ornaments, the cost of acquisition is adjusted for inflation using the Cost Inflation Index (CII) if held for over 24 months. Furthermore, if you received the jewellery through a legal inheritance or will from family members, the original purchase cost incurred by the previous owner serves as your cost basis. Taxpayers must report these transactions accurately in their annual tax returns. For small business owners and freelancers managing operational cash flows, ensuring compliance with GST Registration Services and accurate personal asset reporting prevents discrepancies during tax audits.
How Does Overall Gold Investment Taxation Work? Proper ITR Filing
Comprehensive gold investment taxation demands structured record-keeping across all your financial instruments. Whether you hold mutual funds investing in gold, digital gold products, or sovereign bonds, your annual Income Tax Return (ITR) must reflect these holdings and any realized gains. If you trade SGBs on stock exchanges before maturity, you must compute your profits carefully. If sold within 12 months, gains are short-term and taxed at your slab rate; if sold after 12 months, they qualify for long-term capital gains tax with indexation benefits. According to official data from the Press Information Bureau, retail participation in digital government securities continues to expand rapidly. To maintain flawless compliance, business owners often pair their personal investment filings with valid MSME Udyam Registration and timely tax submissions.
What Are the Rules for Capital Gains on Gold Shares and Traded SGBs?
Investors frequently liquidate assets prematurely, making it vital to understand capital gains on gold shares and exchange-traded gold instruments. If you sell your SGB units on recognized stock exchanges like the NSE or BSE prior to the eight-year maturity mark, the statutory exemption no longer applies. Instead, the transaction is treated as a transfer of a capital asset. Holding the security for more than 12 months classifies the profit as Long-Term Capital Gains, while holding for 12 months or less attracts Short-Term Capital Gains tax. Proper documentation of contract notes and purchase invoices is mandatory. For food businesses and enterprises managing regulatory approvals alongside investments, maintaining an active FSSAI License alongside pristine tax records ensures total administrative security.
⚡ In a Nutshell
Sovereign Gold Bonds offer a 2.5% annual taxable interest payout alongside 100% tax-free capital gains at maturity for individuals, outperforming physical gold and traded shares when held for the full eight-year term.
Mastering the intricacies of gold taxation protects your hard-earned wealth from unexpected tax liabilities. Because tax regulations and reporting thresholds update frequently, relying on experienced professionals is vital. Our advisory team at Delhi Tax Solutions works closely with taxpayers to audit investment portfolios, compute accurate capital gains, and file compliant returns well before statutory deadlines.
Talk to a Delhi Tax Solutions expert today to get your investment capital gains and income tax returns filed with absolute precision and peace of mind.
About this article: Researched using official government sources and Delhi Tax Solutions’ in-house tax advisory team. Last updated August 2026.
This article is for general informational purposes and is not a substitute for personalised professional tax advice.
Frequently Asked Questions
Q: Is the interest on Sovereign Gold Bonds taxable? +
A: Yes. The interest earned on Sovereign Gold Bonds is taxable under the head “Income from Other Sources.” The interest should be included in your taxable income and reported in your annual income tax return according to the applicable tax rules.
Q: Are Sovereign Gold Bonds exempt from capital gains tax at maturity? +
A: Yes. For an individual investor, redemption of Sovereign Gold Bonds by the government on maturity is exempt from capital gains tax under the applicable provisions. This makes holding an SGB until its maturity different from selling it on the secondary market before maturity.
Q: How is physical gold taxed in India? +
A: Taxation of physical gold depends on the applicable holding-period rules at the time of sale. The profit from selling physical gold is generally treated as a capital gain, with the applicable short-term or long-term tax treatment depending on the period for which the asset was held.
Q: Do I need to declare my gold investments in my ITR? +
A: Taxable income arising from gold investments should be reported in the appropriate sections of your ITR. This can include SGB interest and taxable capital gains arising from the sale or transfer of gold-related investments. You should reconcile your records with the relevant tax statements before filing.
Q: What is the tax implication of selling SGBs before maturity? +
A: If an SGB is sold or transferred on the secondary market before maturity, the special maturity redemption exemption does not apply. The resulting profit is generally treated as a capital gain, and the applicable tax treatment depends on the holding period and the manner in which the SGB is transferred.
Q: Is gold jewellery taxable when it is sold? +
A: Yes. Gold jewellery is generally treated as a capital asset. When jewellery is sold for more than its applicable cost, the resulting profit may be taxable as a capital gain. The applicable tax treatment depends on the holding period and the relevant tax provisions in force for the year of sale.
Q: Are SGB interest payments received every year? +
A: Sovereign Gold Bonds generally carry a fixed interest component that is paid periodically during the tenure. The interest received is taxable and should be included in your income tax return under the appropriate head of income.
Q: What records should I keep for gold investment tax reporting? +
A: Keep purchase invoices, SGB holding statements, interest statements, demat records, sale contract notes and other documents showing the acquisition and sale of your gold investments. These records help establish the cost, holding period and taxable income when preparing your ITR.
