
? Key Takeaways
- Family pension is classified as ‘Income from Other Sources,’ not as salary income.
- Legal heirs are eligible for a standard deduction under Section 57(iia).
- The deduction is the lower of 1/3rd of the pension or ?15,000.
- ITR filing requirements depend on total income and source of family pension.
- Accurate documentation prevents tax notices regarding unreported pension receipts.
The passing of a loved one is a profoundly difficult time, and managing the subsequent financial transition—including understanding the tax on family pension received by legal heirs—can feel overwhelming. Many families mistakenly assume that because the deceased individual received their pension as salary, the family pension must be taxed similarly. This assumption is incorrect and often leads to improper ITR filings and potential tax notices. As a CA-led consultancy, Delhi Tax Solutions frequently assists bereaved families in correctly navigating these tax obligations. Understanding the nuances of how the Income Tax Department classifies this income is vital for remaining compliant while minimizing your tax burden during a period of transition.
How is Family Pension Taxed for Legal Heirs?
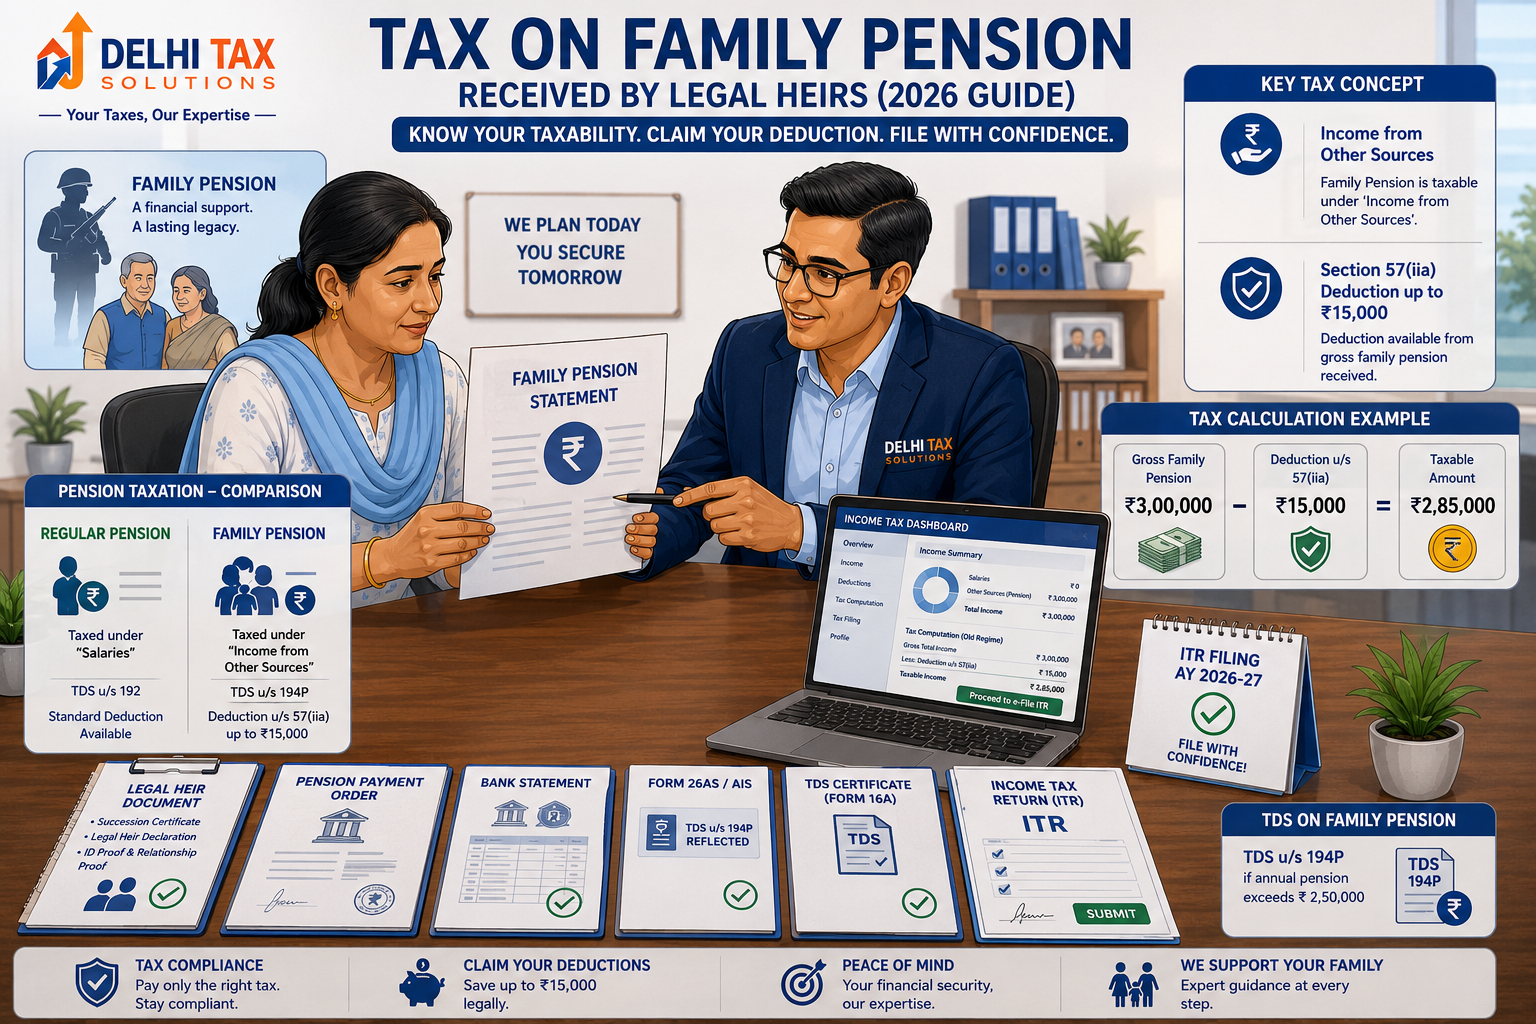
Family pension refers to the periodic payment made to the family of an employee after their death. In the eyes of the Income Tax Act, this money is not considered “Salary.” Because there is no employer-employee relationship between the payer (the government or employer) and the recipient (the legal heir), the income cannot be classified as salary. Instead, it is taxable under the head “Income from Other Sources.” This distinction is critical because it changes the available deductions and the manner in which the income is treated in your annual Income Tax Filing. Being taxed under “Other Sources” means the income is added to your total income from other avenues, such as interest or rental yields, and taxed according to your applicable slab rate.
Understanding the Standard Deduction Benefit
While family pension is taxable, the law provides a specific relief mechanism to reduce the tax incidence. Under Section 57(iia) of the Income Tax Act, legal heirs receiving family pension are entitled to a standard deduction. You can claim a deduction of one-third of the total family pension received or ?15,000, whichever is lower. For example, if you receive a family pension of ?3,00,000, one-third of this amount is ?1,00,000. Since ?15,000 is the lower figure, you will deduct ?15,000 and pay tax on the remaining ?2,85,000. This deduction is a flat statutory benefit and does not require proof of specific expenses. It is an essential step to lower your tax liability before applying slab rates. According to the Income Tax Department, this deduction is available to all legal heirs regardless of their employment status.
Family Pension vs Regular Pension Taxation
Distinguishing between the pension the deceased received and the family pension you receive is essential. Regular pension (received by the employee during their lifetime) is taxed as “Salaries.” In contrast, family pension received by a legal heir after the employee’s death is taxable as “Income from Other Sources.”
| Feature | Regular Pension | Family Pension |
|---|---|---|
| Tax Head | Salaries | Income from Other Sources |
| Deduction Available | Standard Deduction (?50,000) | Section 57(iia) (Up to ?15,000) |
| Employer Link | Yes | No |
| Taxable Entity | The Employee | The Legal Heir |
? In a Nutshell
If you are receiving pension because you are a dependent of a deceased employee, it is Family Pension. Always treat it as “Income from Other Sources” and remember to claim your ?15,000 standard deduction under Section 57(iia) when computing your taxable income.
Step-by-Step Guide to Filing ITR for Family Pension
Filing your return with family pension requires careful categorization. If you are only reporting family pension and interest income, you may qualify for ITR-1. However, if your financial profile is more complex, ITR-2 may be required. First, verify the total family pension received during the financial year using the Annual Information Statement (AIS) available on the tax portal. Second, calculate the taxable portion by subtracting the ?15,000 standard deduction. Third, report this net amount under the “Income from Other Sources” section of your ITR form. Failure to report this correctly is a common compliance error that our team at Delhi Tax Solutions frequently addresses during TDS audits. If you also manage other business assets, such as through a Company Registration or LLP, ensure these income streams are kept distinct in your filings.
Compliance and Common Pitfalls to Avoid
One of the most frequent mistakes legal heirs make is failing to disclose family pension because they believe it is “gift money” or “already taxed.” While some pension funds might deduct tax at source (TDS), it is your responsibility to report the gross amount and claim the credit. If you receive a Reserve Bank of India-regulated pension or a government-sourced pension, ensure the TDS certificates are downloaded and matched against your Form 26AS. Another area of confusion involves property assets. If the deceased left behind rental income or assets subject to Property Tax, ensure these are transferred to the legal heir’s PAN correctly to avoid future disputes. Misreporting these streams often invites scrutiny. It is always better to proactively declare income than to handle a notice later.
Expert Perspective on Succession Planning
The taxation of family pension is only one piece of the broader succession puzzle. As per recent updates from the Press Information Bureau, financial inclusion and the simplification of inheritance norms remain a government priority. However, the onus of compliance rests with the taxpayer. Our advisory team often suggests that clients not only focus on the taxability of the pension but also on the long-term management of inherited assets. If your family income has crossed the taxable threshold due to the pension, consider GST Registration if you are simultaneously running a business, or seek specific ITR advice to structure your finances efficiently. Tax planning for legal heirs requires a comprehensive view of all income sources, not just the pension receipt. Professional guidance ensures you don’t overpay and keeps your compliance history clean.
About this article: Researched using official government sources and Delhi Tax Solutions’ in-house tax advisory team. Last updated August 2026.
Frequently Asked Questions (FAQs)
Q: Is family pension taxable in the hands of the legal heir?
A: Yes, family pension is fully taxable in the hands of the legal heir who receives it. Even though it is a form of support for the family, the Income Tax Act treats it as income. It must be reported in your annual Income Tax Return (ITR), specifically under the head “Income from Other Sources,” and you must pay tax on it based on your applicable income tax slab rates.
Q: Under which head of income is family pension taxable?
A: Family pension is taxable under the head “Income from Other Sources.” It is not classified as “Salary” because there is no employer-employee relationship between the family member and the entity paying the pension. Because it falls under “Other Sources,” you are eligible for a standard deduction under Section 57(iia) of the Income Tax Act, which is not available if it were classified as salary income.
Q: How much standard deduction is available on family pension?
A: Under Section 57(iia) of the Income Tax Act, legal heirs can claim a standard deduction on family pension received. The deduction amount is the lower of two values: either 33.33% (one-third) of the total family pension amount received during the financial year, or a flat maximum limit of ?15,000. This deduction is subtracted from the gross pension amount to determine your net taxable income.
Q: Do I need to report family pension in my ITR?
A: Yes, you are legally obligated to report family pension in your Income Tax Return (ITR). Even if tax has been deducted at source (TDS) by the pension provider, you must disclose the gross amount, claim the standard deduction under Section 57(iia), and calculate your final tax liability. Failing to report this income can lead to automated tax notices due to mismatches between your reported income and the bank’s information statement.
Q: Is there a difference between government and private sector family pension taxation?
A: From an Income Tax Act perspective, there is no difference in the tax treatment of family pension received from the government versus the private sector. Both are taxable under “Income from Other Sources,” and both are eligible for the standard deduction of up to ?15,000 under Section 57(iia). The only difference may be in the TDS procedures and the administrative documentation required, but the underlying tax liability remains identical for the legal heir.
