
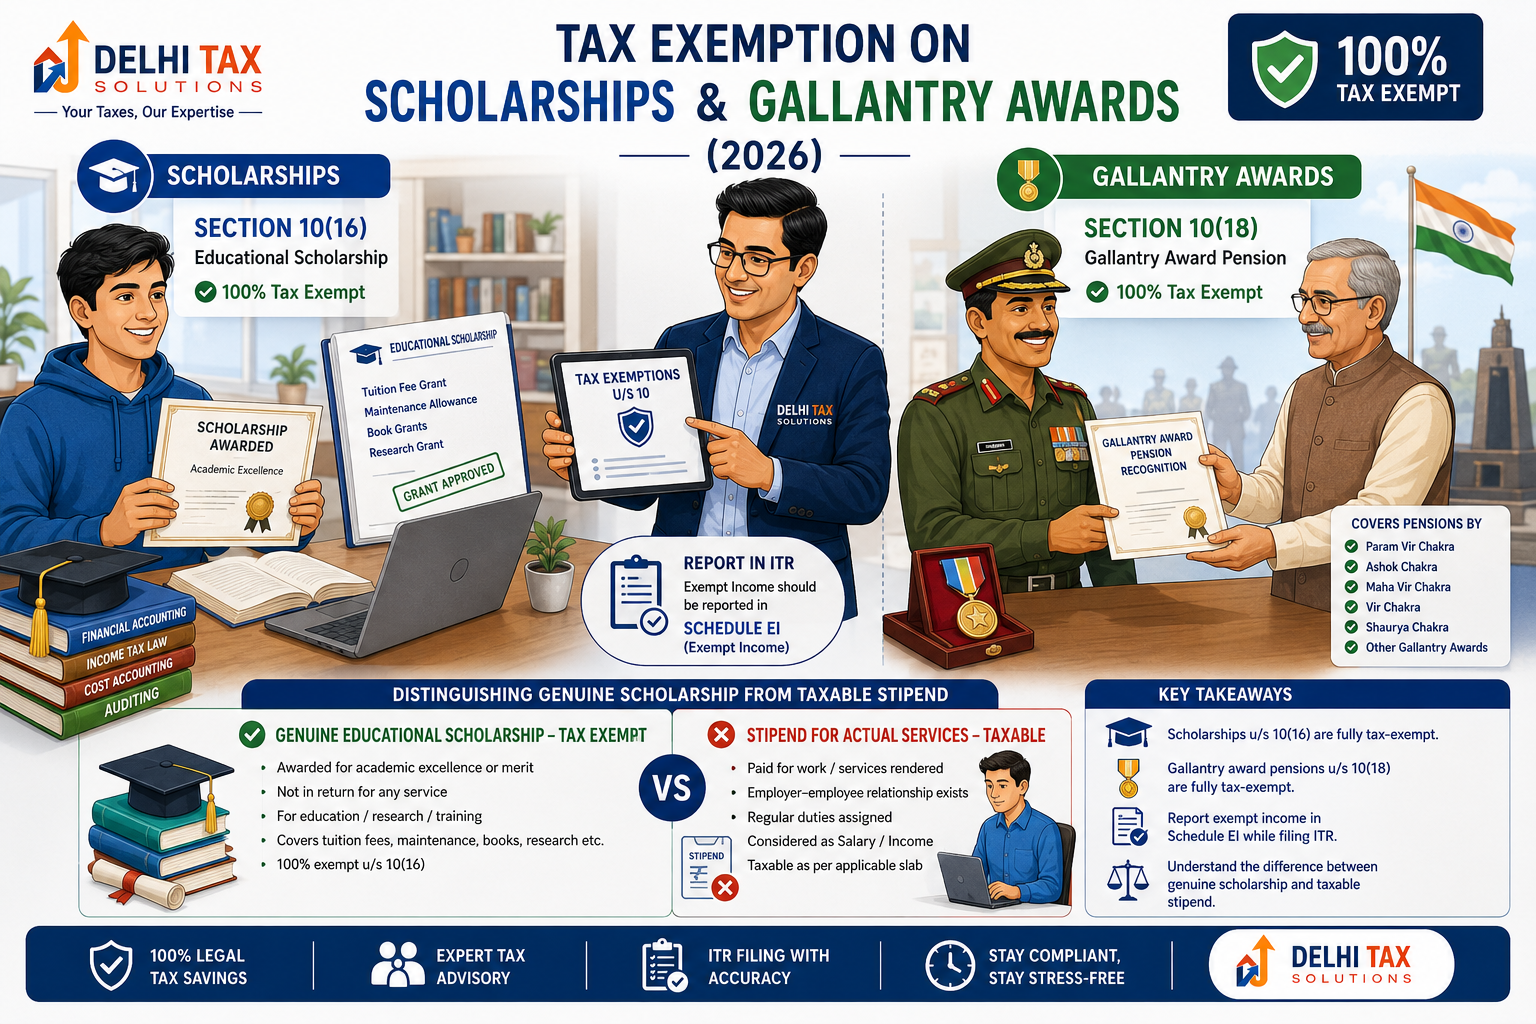
💡 Key Takeaways
- Scholarships granted specifically to meet the cost of education are 100% tax-free under Section 10(16).
- There is no statutory maximum limit on the educational scholarship amount you can receive tax-free.
- Pensions and family pensions awarded to notified gallantry award winners are entirely exempt under Section 10(18).
- If a scholarship is actually disguised salary for research services, it becomes fully taxable.
- You must declare all tax-free income under Schedule EI when filing your annual income tax return.
Navigating the nuances of Indian tax law often reveals generous provisions designed to support specific demographics. Students pursuing higher education and brave military personnel often receive financial grants, pensions, or awards from the government and private institutions. Beneficiaries frequently panic, assuming these incoming funds will push them into high tax brackets. Understanding the exact tax exemption on scholarships and gallantry awards is crucial for families trying to manage their finances efficiently. The Income Tax Act ensures that money meant for education or honoring extraordinary national service remains entirely untouched by tax authorities. Our advisory team at Delhi Tax Solutions routinely helps clients report these exact exemptions properly during Income Tax Filing. Let us decode the specific sections that guarantee this tax-free income India allows.
What Is the Exemption on Scholarships and Awards?
Under the Indian Income Tax Act, the tax exemption on scholarships and gallantry awards provides absolute relief to specific recipients. Section 10(16) fully exempts any scholarship granted to a student to meet the cost of education, regardless of the amount. Similarly, Section 10(18) provides a 100% tax exemption on the pension and family pension received by individuals who have been honored with notified gallantry awards, such as the Param Vir Chakra. Taxpayers must simply report these amounts as exempt income on their annual returns.
The Educational Scholarship Exemption Section
How Section 10(16) Works in Practice
The educational scholarship exemption section operates under Section 10(16) of the Income Tax Act. The law states that any scholarship granted to a person to meet the cost of education is entirely exempt from tax. This applies whether the funds come from the government, a university, or a private trust. There is no monetary ceiling on this exemption. If a student receives a ₹15 Lakh post-matric scholarship tax grant to study abroad, the entire ₹15 Lakh remains completely tax-free.
Coverage for Higher Education Tax Benefits
This exemption covers school students, undergraduates, and PhD scholars receiving stipends. The core requirement is that the money must facilitate education. According to guidelines often referenced by the Income Tax Department, it does not matter if the student manages to save a portion of the scholarship money. As long as the primary intent of the grant was educational support, the saved amount does not suddenly become taxable.
Is Scholarship Taxable Income in Any Scenario?
When Scholarships Become Taxable
Many taxpayers ask, is scholarship taxable income under specific conditions? Yes, if the “scholarship” is actually compensation in disguise. If a hospital pays a junior resident doctor a monthly stipend to perform regular medical duties, the department treats this as taxable salary. The funds are paid for services rendered, not purely for educational advancement. True Section 10(16) scholarship funds require no commercial service in return.
Avoiding TDS Deductions on Educational Grants
Sometimes, institutions mistakenly deduct tax on stipends before paying the student. If an educational trust incorrectly applies a 10% deduction on your scholarship, you must file a return to claim that money back. Managing these errors requires strict adherence to proper TDS Compliance protocols. You will need a formal certificate from the issuing university clarifying that the payment was an educational grant, not professional fees.
⚡ In a Nutshell
If you receive money purely to fund your studies, it is tax-free. If you receive money in exchange for performing a job or providing a service (even as a student), that income is fully taxable.
Understanding the Gallantry Award Tax Exemption
Provisions Under Section 10(18)
The government honors military bravery with specific financial protections. The gallantry award tax exemption is governed by Section 10(18) gallantry awards clauses. It completely exempts the pension received by an individual who has been awarded a notified gallantry award. This includes the Param Vir Chakra tax exemption, Maha Vir Chakra, and Vir Chakra. If the awardee passes away, the family pension received by their legal heirs remains entirely tax-free.
Notified Awards and Official Recognition
Not every military medal qualifies for this specific tax relief. The exemption strictly applies to awards formally notified by the Central Government in the official gazette. The Press Information Bureau periodically releases updates whenever new civilian or military honors are added to the tax-exempt list. The pension of gallantry award winners provides absolute financial security for the families of those who have served the nation with supreme distinction.
| Exemption Category | Applicable Section | Nature of Exemption | Maximum Tax-Free Limit |
|---|---|---|---|
| Educational Scholarships | Section 10(16) | Funds granted to meet the cost of education. | No statutory limit. Fully exempt. |
| Gallantry Award Pension | Section 10(18) | Pension paid to notified award winners. | No statutory limit. Fully exempt. |
| Family Pension (Gallantry) | Section 10(18) | Pension paid to legal heirs of the awardee. | No statutory limit. Fully exempt. |
| Disguised Salary Stipends | Taxable as Salary | Payments made for services rendered. | Taxable at normal slab rates. |
Reporting Exempt Income During Your Annual ITR
Using the Schedule EI Framework
Receiving tax-free money does not excuse you from reporting it to the government. When you execute your annual tax filing, you must declare the tax exemption on scholarships and gallantry awards under ‘Schedule EI’ (Exempt Income). Failing to report substantial scholarship inflows can trigger automated scrutiny because the deposits will reflect in your bank statements. The Reserve Bank of India monitors high-value incoming remittances, especially international fellowships, ensuring all foreign capital flows are accounted for.
Documenting Your Tax-Free Status
Taxpayers must maintain pristine records to substantiate their exempt claims. Keep your university admission letters, official scholarship sanction documents, and gazette notifications for gallantry awards safely filed away. If the tax department issues a notice asking you to explain large bank deposits, these documents serve as your primary defense. If you hold significant personal real estate alongside this exempt income, synchronizing your Property Tax records with your ITR prevents unnecessary net-worth discrepancies.
Corporate Roles in Educational Scholarship Funding
Corporate Social Responsibility (CSR) Grants
Many students receive their Section 10(16) benefits directly from private corporations rather than universities. Companies often distribute educational grants as part of their mandatory CSR obligations. According to directives from the Ministry of Corporate Affairs, businesses must allocate a percentage of their net profits to social initiatives. Students receiving these corporate grants enjoy the exact same tax-free status as those receiving government funds.
Setting Up Educational Trusts
Entrepreneurs who wish to establish formal scholarship programs must structure their entities correctly. Creating an educational trust requires specific documentation, separate from a standard Company Registration process. These trusts must register under Section 12AB of the Income Tax Act to issue valid, tax-exempt scholarships to students legally.
Securing a tax exemption on scholarships and gallantry awards provides massive financial relief to deserving students and decorated veterans. You simply need to ensure that the nature of your grant strictly aligns with the definitions provided under Section 10(16) and Section 10(18). Never attempt to disguise professional service fees as a tax-free scholarship, as this invites severe penalties during assessment. Talk to a Delhi Tax Solutions expert to get your exempt income reported flawlessly within Schedule EI. Securing professional CA guidance guarantees your tax-free income remains entirely protected from departmental disputes.
About this article: Researched using official government sources and Delhi Tax Solutions’ in-house tax advisory team. Last updated August 2026.
Frequently Asked Questions (FAQs)
Q: What is the tax exemption on scholarships and gallantry awards?
A: The tax exemption on scholarships and gallantry awards allows specific individuals to receive funds entirely tax-free. Under Section 10(16), any scholarship granted to meet the cost of education is 100% exempt from income tax. Under Section 10(18), the pension and family pension paid to individuals awarded notified gallantry awards are also fully exempt from any tax liability.
Q: Is scholarship taxable income in India?
A: No, a genuine scholarship is not taxable income in India. If the money is granted specifically to meet educational expenses, it is fully exempt under Section 10(16). However, if the stipend is actually paid in exchange for rendering professional services or performing a job (like a medical residency salary), the tax department will classify it as taxable income.
Q: How do I claim the educational scholarship exemption section benefits?
A: You do not need to submit any specific forms during the year to claim the educational scholarship exemption section benefits. You simply receive the funds tax-free. However, when you file your annual Income Tax Return (ITR), you must declare the total scholarship amount received under ‘Schedule EI’ (Exempt Income) to ensure full statutory compliance with the tax department.
Q: Who qualifies for the gallantry award tax exemption?
A: The gallantry award tax exemption strictly applies to individuals who have received bravery awards formally notified by the Central Government, such as the Param Vir Chakra, Maha Vir Chakra, or Vir Chakra. Section 10(18) ensures that the pension received by these decorated individuals, as well as the family pension received by their legal heirs, is completely tax-free.
Q: Do I need to report tax-free income during ITR filing?
A: Yes, you are legally required to report all your tax-free income during ITR filing. Even though the money from a scholarship or a gallantry pension is not taxed, it must be disclosed transparently in Schedule EI of your tax return. Failing to report significant exempt income can trigger automated notices if the tax department questions large bank deposits.
