
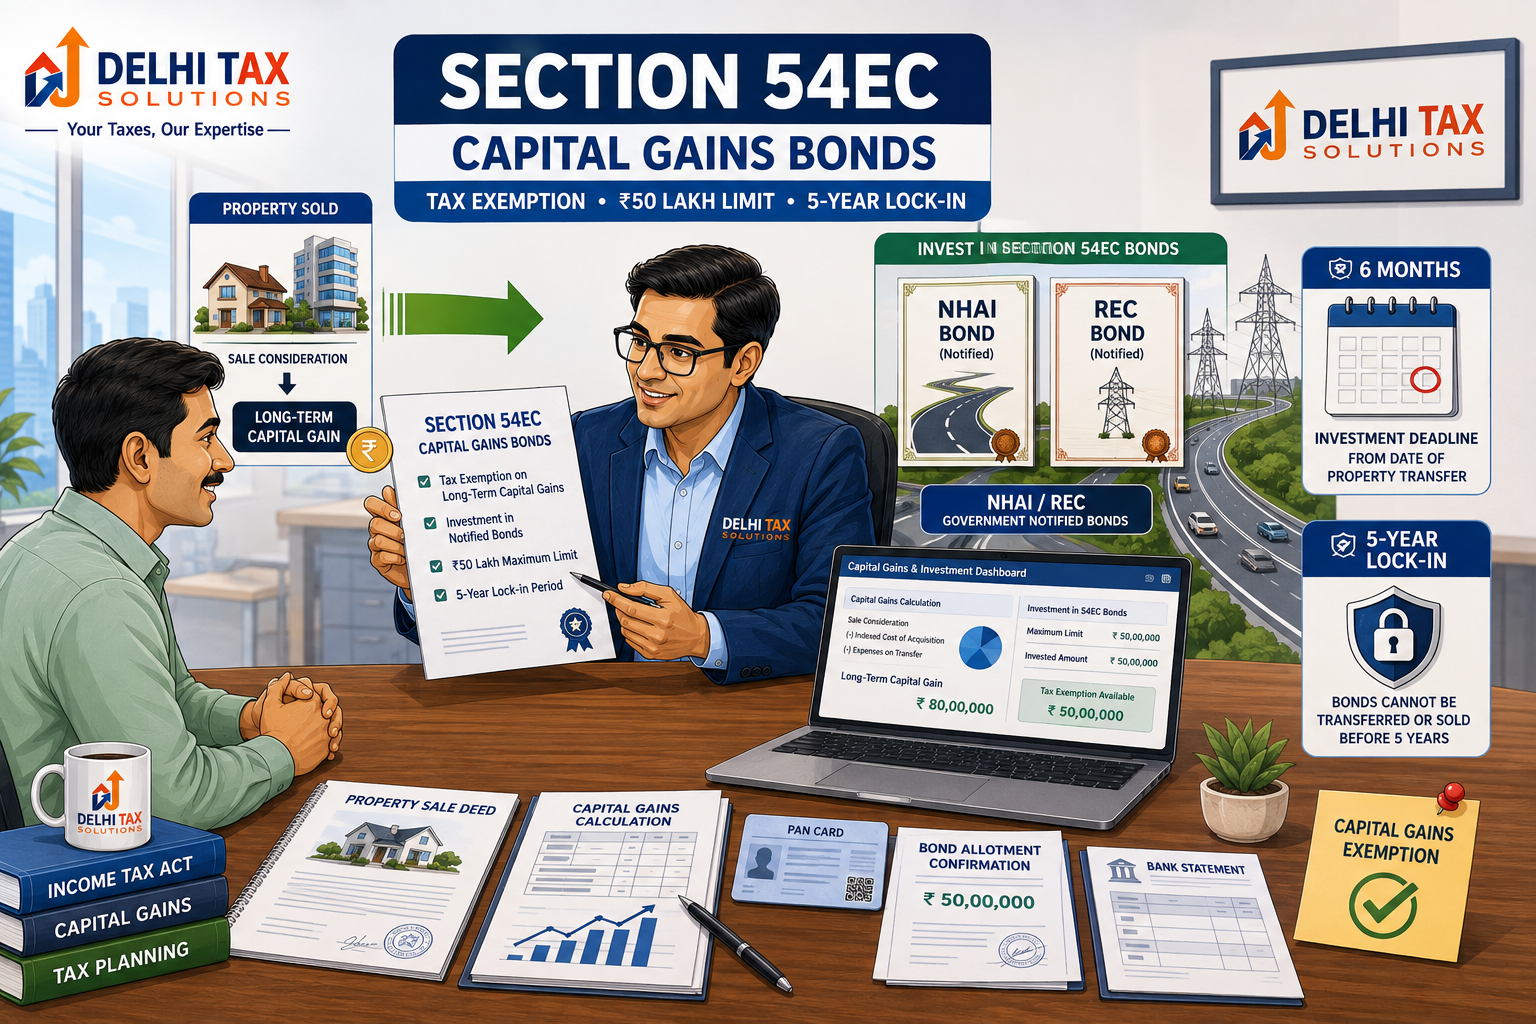
? Key Takeaways
- Section 54EC allows complete tax exemption on long-term capital gains derived from selling land or buildings.
- The maximum 54EC bonds investment limit is capped at ?50 lakhs per financial year per taxpayer.
- Investors must maintain a mandatory 54EC lock in period of 5 years to preserve tax benefits.
- Eligible investments are restricted to notified infrastructure bonds issued by institutions like NHAI and REC.
- Reinvestment into these bonds must be completed within 6 months from the date of property transfer.
Selling residential or commercial real estate in India often triggers substantial tax liabilities. When property owners realize significant capital profits, navigating tax regulations becomes critical. Utilizing Section 54EC capital gains bonds offers a secure, government-backed route to shelter profits from heavy taxation. Taxpayers across Delhi NCR frequently pair real estate transactions with professional Income Tax filing, meticulous Property Tax reviews, corporate Company Registration structures, and statutory TDS compliance.
Official tax compliance guidelines published by the Income Tax Department outline exact requirements for claiming exemptions. Policy briefings released by the Press Information Bureau highlight how infrastructure funding channels protect long-term investor capital. This authoritative guide examines investment caps, lock-in rules, and strategic compliance steps.
What are Section 54EC capital gains bonds and how do they work?
Section 54EC capital gains bonds are specialized fixed-income instruments designed to offer tax shelter on long-term capital gains arising from the transfer of land, buildings, or both. When a taxpayer sells immovable property after holding it for more than 24 months, profits qualify as long-term capital gains. By investing the capital gains amount into notified bonds within a statutory window of six months, individuals can claim full or proportionate tax exemptions under Section 54EC of the Income-tax Act, reducing their tax outflow while supporting critical national infrastructure development.
What is the investment limit and timeline for Section 54EC bonds?
The 54EC bonds investment limit is strictly capped at ?50 lakhs per financial year for any single taxpayer. Regulatory frameworks overseen by the Ministry of Corporate Affairs specify that even if a property sale generates capital gains exceeding ?50 lakhs, the maximum exemption claim through these bonds cannot surpass this threshold. Based on cases handled by our CA team at Delhi Tax Solutions, taxpayers must execute bond purchases within six months from the property transfer date or before the ITR filing due date, whichever is earlier.
Annual ceiling cap
The ?50 lakh ceiling applies strictly per financial year, meaning split transactions across April can sometimes leverage dual-year caps.
Six-month strict window
Failing to complete the bond subscription within six months from the sale date permanently forfeits the Section 54EC tax exemption.
Asymmetric fiscal overlap
If a property is sold in January, the six-month window spans across two financial years, enabling strategic allocation up to the ?50 lakh limit in each year.
Which issuers provide NHAI REC capital gains bonds?
Eligible instruments for tax exemption are restricted to notified issues from premier public sector undertakings like NHAI REC capital gains bonds. Financial advisories regulated by the Reserve Bank of India confirm that National Highways Authority of India (NHAI) and Rural Electrification Corporation (REC) issue these AAA-rated bonds. These secure instruments carry sovereign backing, ensuring high capital safety alongside moderate fixed coupon interest rates, which are fully taxable as per the investor’s income slab.
NHAI infrastructure funding
Bonds issued by NHAI channel capital directly into national highway expansion projects across India with robust government backing.
REC power sector support
Rural Electrification Corporation bonds finance power transmission and distribution networks, combining secure yields with statutory tax shields.
Interest income taxation
While the capital gains are sheltered from tax, the annual interest earned on these bonds is added to taxable income and taxed accordingly.
What is the mandatory lock-in period and liquidity rule?
The 54EC lock in period is strictly set at 5 years from the date of bond acquisition. According to statutory tax guidelines, investors cannot sell, transfer, pledge, or take loans against these bonds during this five-year window. If an investor attempts to prematurely transfer or redeem the bonds before the completion of 5 years, the previously exempted capital gains immediately become taxable in the year of such default.
Five-year asset lock
Capital remains locked for 60 months, ensuring long-term commitment to infrastructure projects managed by authorized public sector entities.
Consequences of premature transfer
Any unauthorized pledge or early exit revokes the tax exemption retroactively, triggering immediate tax liability plus applicable interest.
Death of the investor
In unfortunate cases of investor demise during the lock-in term, transmission of bonds to legal heirs is permitted without forfeiting tax benefits.
| Parameter | Section 54EC Bonds | Section 54 Residential Property | Capital Gains Account Scheme (CGAS) |
|---|---|---|---|
| Eligible Asset Sold | Land or Building (Long-Term) | Residential House Property | Any Long-Term Capital Asset |
| Maximum Investment Limit | ?50 Lakhs per Financial Year | No monetary cap specified | Equal to actual capital gains amount |
| Lock-in Period | 5 Years (Mandatory) | 3 Years from purchase date | Until funds are utilized (Max 3 years) |
| Reinvestment Window | Within 6 Months of sale | 1 year before or 2 years after sale | Before ITR filing due date |
? Quick Summary
Section 54EC bonds provide a secure way to save capital gains tax up to ?50 lakhs per year by locking funds in NHAI or REC bonds for 5 years.
How to execute capital tax saving and avoid common pitfalls?
Securing exemption under section 54ec capital gains requires precise documentation and timely execution during annual tax filings. Property sellers must ensure that bond applications cite correct PAN details and match sale deeds accurately. Furthermore, maintaining bank statements proving fund transfers directly from the capital gains account prevents scrutiny during tax assessments. Leveraging professional consultancy ensures that investments comply perfectly with changing regulatory notifications.
Accurate PAN mapping
Ensuring that bond certificates reflect the exact PAN and name as appearing in income tax records avoids processing delays.
Audit trail maintenance
Preserving sale deeds, bank statements, and bond allotment letters substantiates legitimacy during tax scrutiny or automated e-assessment notices.
Talk to a Delhi Tax Solutions expert to get your property capital gains exemptions and ITR filings managed accurately today.
About this article: Researched using official government sources and Delhi Tax Solutions’ in-house tax advisory team. Last updated August 2026.
This article is for general informational purposes and is not a substitute for personalised professional tax advice.
Frequently Asked Questions (FAQs)
Q: What is the maximum investment limit for Section 54EC capital gains bonds?
A: The maximum investment limit in Section 54EC capital gains bonds is capped at ?50 lakhs per financial year per taxpayer. Even if your long-term capital gains from selling land or buildings exceed this amount, the maximum tax exemption you can claim through these bonds cannot surpass the ?50 lakh threshold in a single fiscal year.
Q: What is the lock-in period for NHAI and REC capital gains bonds under Section 54EC?
A: The mandatory lock-in period for Section 54EC capital gains bonds issued by institutions like NHAI and REC is 5 years. Investors cannot sell, transfer, pledge, or take loans against these bonds during this 60-month window, failing which the previously claimed tax exemption becomes revocable and taxable.
Q: Which bonds are eligible for tax exemption under Section 54EC of the Income-tax Act?
A: Tax exemption under Section 54EC is restricted exclusively to long-term capital gains bonds notified by the central government and issued by designated public sector undertakings such as the National Highways Authority of India (NHAI) and the Rural Electrification Corporation (REC).
Q: Is the interest earned on Section 54EC capital gains bonds fully taxable?
A: While the capital gains invested into Section 54EC bonds are exempt from tax up to ?50 lakhs, the annual interest income earned on these bonds is fully taxable. This interest is added to your total annual income and taxed according to your applicable income tax slab rates for that financial year.
Q: Within how many months must I invest in 54EC bonds after selling property?
A: Taxpayers must invest their long-term capital gains into notified Section 54EC bonds within a strict statutory window of 6 months from the date of property transfer. Additionally, this investment must be completed before the filing of the income tax return for that assessment year to successfully claim the exemption.
