
? Key Takeaways
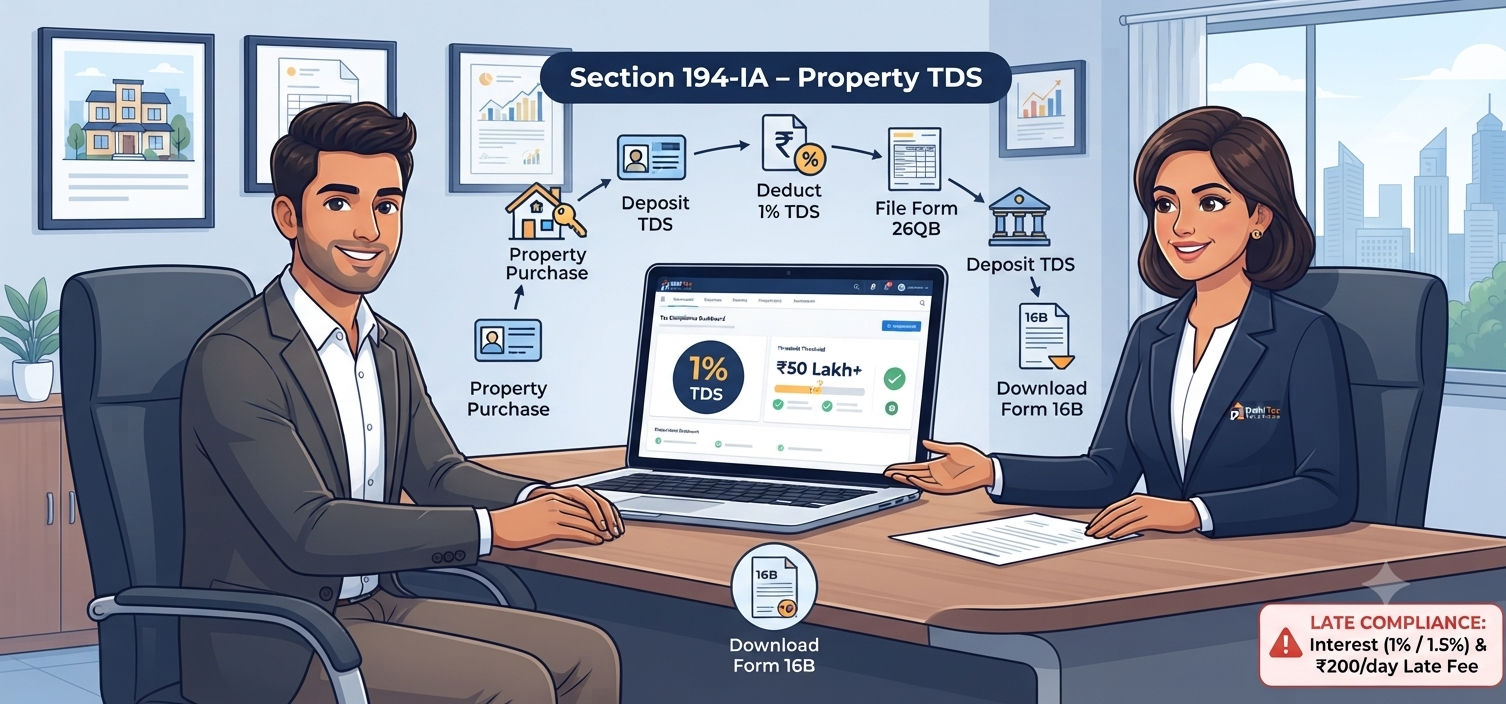
- Section 194-IA requires residential property buyers to deduct 1 percent TDS on property purchases exceeding ?50,00,000.
- The buyer must deposit the deducted TDS and file Form 26QB within 30 days from the end of the deduction month.
- A Tax Deduction Account Number (TAN) is not mandatory for the buyer; individual PAN details suffice.
- Failing to deposit TDS on time attracts severe monthly interest penalties and statutory late filing fees under Section 234E.
- Form 16B must be downloaded from the TRACES portal and issued to the seller as proof of tax payment.
Purchasing residential or commercial real estate is a major financial milestone for individuals and families across India. However, completing a real estate transaction involves strict direct tax compliance, particularly for buyers responsible for withholding tax at source. Mastering Section 194IA TDS on property purchase procedures is essential to avoid statutory penalties and ensure seamless property registration. Under Indian income tax laws, the burden of deducting and depositing tax shifts directly to the purchaser during property settlements.
Navigating these tax obligations requires aligning real estate transactions with official government regulations. Guidelines published by the Income Tax Department outline the exact procedures for withholding tax and filing electronic statements. Property buyers operating across Delhi NCR must manage these compliance steps alongside routine Income Tax filings, Corporate Registration processes, and TDS management.
This authoritative advisory guide breaks down statutory monetary thresholds, TDS on property Form 26QB filing steps, buyer TDS obligation property rules, and penalty structures for late payments.
What is Section 194-IA and how does property TDS apply to buyers?
Section 194-IA of the Income-tax Act mandates that any person buying immovable property (other than rural agricultural land) must deduct tax at source (TDS) at the rate of 1 percent from the sale consideration paid to the resident seller. According to policy updates released by the Press Information Bureau, this statutory provision was introduced to curb tax evasion and track high-value capital transactions across the real estate sector. The buyer deducts this 1 percent amount directly from the payment made to the seller and deposits it with the government using the seller’s PAN.
What are the monetary thresholds for TDS on property above threshold?
Applying TDS on property above threshold rules requires monitoring the exact sale consideration or stamp duty value of the immovable property. Regulatory frameworks monitored by the Ministry of Corporate Affairs establish that TDS under Section 194-IA applies only when the total sale consideration equals or exceeds ?50,00,000 (50 Lakhs). If the property value is below ?50,00,000, no TDS deduction is required. Furthermore, this threshold applies per property transaction, and if there are multiple buyers or sellers, the aggregate sale consideration is evaluated against the 50-lakh limit.
Inclusion of all charges
The ?50,00,000 threshold includes all incidental charges such as club membership fees, car parking fees, water and electricity connection charges, and maintenance deposits bundled into the agreement.
Exclusion of agricultural land
Transactions involving rural agricultural land situated outside specified municipal limits are completely exempt from Section 194-IA tax deduction requirements.
How does the buyer TDS obligation property framework operate?
Fulfilling the buyer TDS obligation property requirements requires strict adherence to statutory timelines and documentation protocols. Regulatory circulars monitored by the Reserve Bank of India and tax authorities specify that the buyer does not need to obtain a Tax Deduction Account Number (TAN) to deposit property TDS; quoting the buyer’s and seller’s PAN is entirely sufficient. However, the buyer assumes full legal responsibility for deducting the tax at the time of making payment or crediting the seller’s account, whichever occurs earlier.
Instalment payment rules
If the purchase consideration is paid in multiple instalments, 1 percent TDS must be deducted proportionally from every individual payment made to the seller.
Non-resident sellers
If the property seller is a Non-Resident Indian (NRI), Section 194-IA does not apply; instead, TDS must be deducted under Section 195 at higher capital gains rates, requiring a lower deduction certificate.
| Compliance Parameter | Statutory Rule / Requirement | Applicable Provision |
|---|---|---|
| Property Value Threshold | Sale consideration must be ?50,00,000 or more | Section 194-IA(1) |
| Tax Deduction Rate | 1 percent of total sale consideration or stamp duty value | Section 194-IA(1) proviso |
| Deposit & Filing Deadline | Within 30 days from the end of the month in which TDS was deducted | Rule 30 / Form 26QB |
| Proof of Tax Payment | Form 16B certificate to be downloaded and issued to the seller | TRACES Portal |
? Quick Summary
For properties valued at ?50 Lakhs or more, buyers must deduct 1% TDS, deposit it within 30 days via Form 26QB, and issue Form 16B.
What is the step-by-step process for filing TDS on property Form 26QB?
Executing the Section 194-IA compliance steps involves generating and submitting TDS on property Form 26QB through the official income tax e-filing portal. Based on cases handled by our CA team at Delhi Tax Solutions, buyers frequently encounter payment hurdles if property details or PAN information are entered incorrectly. Following a structured procedure ensures timely deposit and prevents transaction delays during sub-registrar office registration and GST Registration evaluations for commercial units.
Step 1: Gather party details
Collect accurate PAN cards, addresses, and contact details of both buyer(s) and seller(s), alongside property deed specifics and payment particulars.
Step 2: Submit Form 26QB online
Log into the e-filing portal, navigate to e-file tax e-payment services, fill out Form 26QB with consideration details, and complete net banking or debit card payment.
Step 3: Download Form 16B
After successful payment processing, access the TRACES portal after approximately 5 to 7 days to download Form 16B and hand it over to the property seller.
What are the penalties for missing property TDS payment deadlines?
Failing to comply with property TDS timelines invites stringent penal consequences under the Income-tax Act. If a buyer fails to deduct TDS, a penal interest of 1 percent per month is levied from the date tax was deductible until the actual date of deduction. Furthermore, if the deducted tax is not deposited with the government within the mandated 30-day window, an interest penalty of 1.5 percent per month applies from the date of deduction until the date of deposit. Additionally, a statutory late fee of ?200 per day under Section 234E is levied for late filing of Form 26QB.
Cumulative financial impact
Delayed filings accumulate steep interest charges and late fees, complicating property mutation and financial audits.
Prosecution risks
Willful failure to deposit withheld government tax can lead to severe legal prosecution and recovery proceedings under Section 276B.
Talk to a Delhi Tax Solutions expert to get your property TDS filings and compliance documentation managed seamlessly today.
About this article: Researched using official government sources and Delhi Tax Solutions’ in-house tax advisory team. Last updated August 2026.
This article is for general informational purposes and is not a substitute for personalised professional tax advice.
Frequently Asked Questions (FAQs)
Q: What is the threshold limit for deducting TDS on property purchase under Section 194-IA?
A: Under Section 194-IA of the Income-tax Act, tax at source must be deducted by the buyer only when the total sale consideration of the immovable property equals or exceeds ?50,00,000 (50 Lakhs). If the transaction value is below this threshold, no TDS deduction is mandated by law. This limit applies to the aggregate consideration paid for residential and commercial properties, excluding rural agricultural land.
Q: What is the applicable TDS rate on property purchases in India?
A: The standard TDS rate for property purchases under Section 194-IA is 1 percent of the total sale consideration or stamp duty value, whichever is higher. This tax must be deducted by the buyer at the time of making payment to a resident seller. However, if the seller fails to provide a valid PAN card, the applicable TDS rate spikes to 20 percent under Section 206AA.
Q: How does a buyer file Form 26QB and deposit property TDS online?
A: The buyer must file Form 26QB online through the official Income Tax e-filing portal by providing property details, PAN information of both buyer and seller, and payment particulars. The tax can be deposited online via net banking or debit cards within 30 days from the end of the month in which the deduction was made, after which Form 16B is generated on TRACES.
Q: What are the penalties for late deduction or late deposit of property TDS?
A: Failing to deduct TDS attracts an interest penalty of 1 percent per month, while failing to deposit deducted tax within the 30-day deadline attracts 1.5 percent monthly interest. Furthermore, a statutory late fee of ?200 per day under Section 234E is levied for every day Form 26QB remains unfiled, making timely compliance critical for buyers.
Q: Is a TAN mandatory for the buyer when deducting TDS on immovable property?
A: A Tax Deduction Account Number (TAN) is not mandatory for an individual buyer purchasing residential or commercial property under Section 194-IA. The buyer can execute the entire TDS deduction and Form 26QB filing process successfully by quoting their own Permanent Account Number (PAN) and the seller’s PAN without needing to register for a TAN.
