
💡 Key Takeaways: Refund of Tax Wrongfully Collected (Section 77)
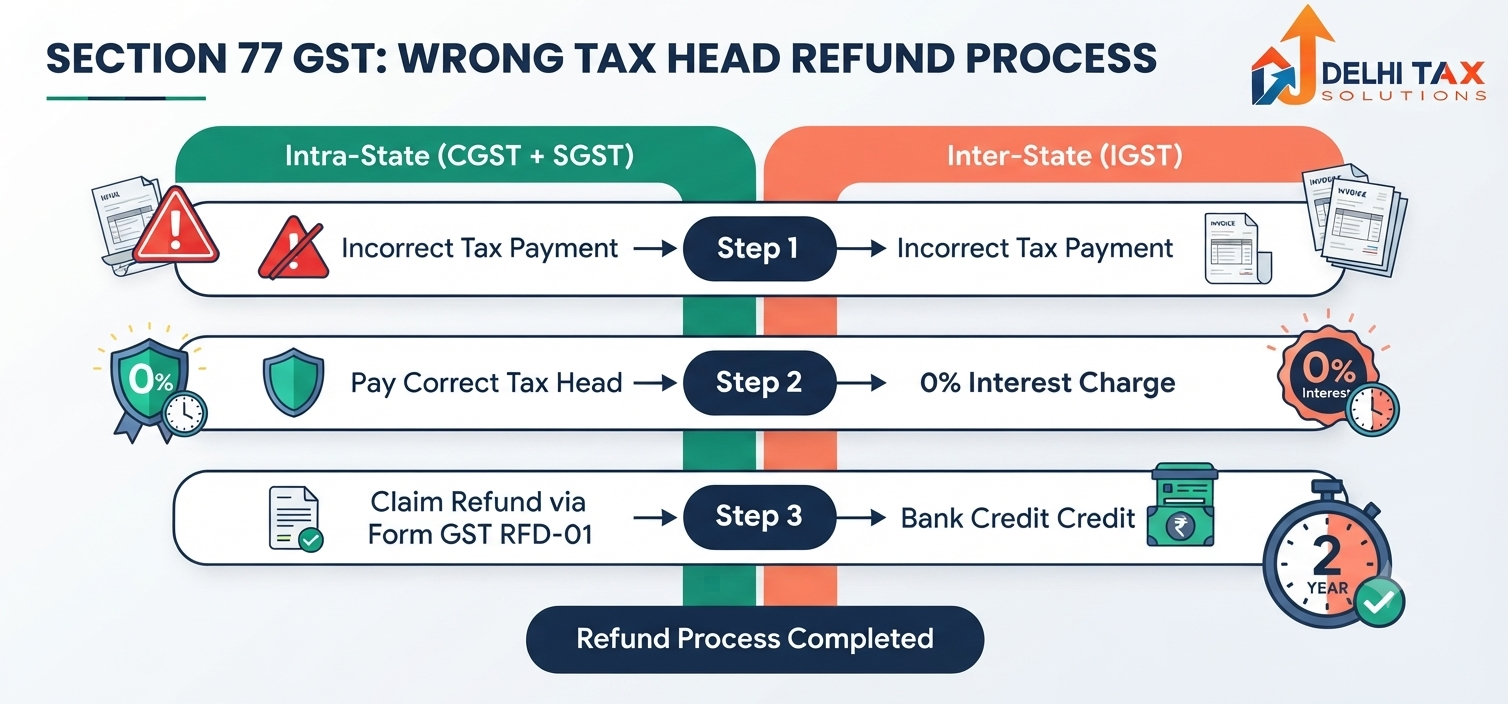
- Section 77 of CGST Act & Section 19 of IGST Act protect taxpayers who accidentally pay tax under the wrong head (e.g., paid CGST+SGST instead of IGST, or vice versa).
- Zero Interest Penalty: Under Section 77(2) and Section 19(2), you do NOT have to pay any interest when paying the correct tax head later.
- Two-Step Remedy: Pay the correct tax head first, and then claim a 100% refund of the wrongfully paid tax head via Form GST RFD-01.
- 2-Year Time Limit (Rule 89(1A)): Refund application must be filed within 2 years from the date of payment of the correct tax.
- Direct adjustment between tax heads is not permissible on the GST portal; payment of the correct tax head is a mandatory prerequisite to claiming the refund.
In the GST regime, determining the correct Place of Supply can sometimes be complex. A wrong determination leads to charging CGST + SGST instead of IGST (Intra-state error) or IGST instead of CGST + SGST (Inter-state error). When this happens, taxpayers often panic, worrying about double tax liability and severe interest penalties.
Fortunately, the lawmakers anticipated this situation. Section 77 of the CGST Act, 2017 (read alongside Section 19 of the IGST Act, 2017) provides a legal mechanism to rectify such errors seamlessly without imposing interest penalties.
Understanding the Two Error Scenarios
Section 77 and Section 19 cover two specific scenarios where tax is paid under an incorrect tax head due to a misclassification of the supply type:
Scenario A: Paid CGST + SGST instead of IGST
A taxable person treats a transaction as an Intra-State supply and pays CGST + SGST. Later, upon audit, officer scrutiny, or self-assessment, it is held that the transaction was actually an Inter-State supply attracting IGST.
Scenario B: Paid IGST instead of CGST + SGST
A taxable person treats a transaction as an Inter-State supply and pays IGST. Later, it is determined that the transaction was actually an Intra-State supply attracting CGST + SGST.
Comparison: Section 77 CGST Act vs Section 19 IGST Act
| Feature | Section 77 CGST Act | Section 19 IGST Act |
|---|---|---|
| Initial Wrong Tax Paid | CGST + SGST (Paid as Intra-state) | IGST (Paid as Inter-state) |
| Actual Correct Tax Payable | IGST (Actually Inter-state) | CGST + SGST (Actually Intra-state) |
| Interest on Correct Tax | NIL (No interest charged) | NIL (No interest charged) |
| Refund Eligibility | 100% Refund of CGST + SGST paid | 100% Refund of IGST paid |
| Refund Form | Form GST RFD-01 | Form GST RFD-01 |
The No-Interest Protection: Section 77(2) & Section 19(2)
Normally, under Section 50 of the CGST Act, delayed tax payments attract interest at 18% per annum. However, Section 77(2) explicitly grants immunity from interest in cases of wrong tax head payments.
🛡️ Statutory Immunity from Interest
Section 77(2) states: “A registered person who has paid central tax and State tax on a transaction considered by him to be an intra-State supply, but which is subsequently held to be an inter-State supply, shall not be required to pay any interest on the amount of integrated tax payable.”
This means even if you pay the correct tax head after 1 or 2 years, the tax authorities cannot charge interest on the correct tax payment, provided the wrong tax head was paid on time!
Time Limit for Filing Refund under Rule 89(1A)
Prior to September 2021, there was ambiguity regarding when the 2-year time limit (statutory limitation period) for claiming this refund begins. To resolve this, the government introduced Rule 89(1A) via Notification No. 35/2021-Central Tax.
📅 How the 2-Year Limitation Clock Operates
The 2-year period for claiming a refund under Section 77 / Section 19 is counted from the DATE OF PAYMENT OF THE CORRECT TAX HEAD (and NOT from the original invoice or GSTR-3B filing date).
Step-by-Step Procedure to Rectify and Claim Refund
Follow this exact 4-step workflow to rectify tax head errors and recover your money:
- Step 1: Identify the Error: Verify the original supply details, customer GSTIN/state code, and Place of Supply rules.
- Step 2: Pay the Correct Tax Head: Discharge the correct tax liability (IGST or CGST+SGST) through electronic cash/credit ledger in your current month’s GSTR-3B return.
- Step 3: Log in to GST Portal: Navigate to Services > Refunds > Application for Refund.
- Step 4: File RFD-01: Select the refund category “Excess tax paid through GSTR-3B” or “Tax paid on an intra-State supply which is subsequently held to be inter-State supply and vice versa”. Upload relevant invoice details and payment proof of the correct tax head.
⚠️ Crucial Practical Insight
You cannot automatically adjust the wrong tax head against the correct tax head on the portal. You MUST pay the correct tax first out-of-pocket or via ITC, and then file the refund application for the wrongfully paid tax.
Common Mistakes to Avoid
- Attempting Direct Ledger Transfer: Trying to transfer balance using Form PMT-09 between different liability heads for past finalized returns is not permitted.
- Delaying Correct Tax Payment: Postponing the payment of the correct tax head unnecessarily delays the start of your 2-year refund limitation clock.
- Not Preserving Payment Proofs: Ensure you keep copies of both original GSTR-3B returns and the return showing the correct tax payment for officer verification.
Need Help Resolving Wrong GST Tax Head Payments?
Faced with tax officer notices for inter-state vs intra-state errors, or finding it difficult to file Section 77 refund claims? Our team of seasoned GST professionals ensures smooth rectification, complete interest immunity, and timely refund recovery.
Contact Delhi Tax Solutions today for expert legal guidance and hassle-free GST refund assistance!
Frequently Asked Questions (FAQs)
+ Q: Do I have to pay interest when paying the correct tax head under Section 77?
A: No. Section 77(2) of the CGST Act and Section 19(2) of the IGST Act explicitly state that no interest is required to be paid on the correct tax head if tax was previously paid under the wrong tax head.
+ Q: What is the time limit for claiming a refund under Section 77?
A: Under Rule 89(1A) of CGST Rules, the refund application in Form GST RFD-01 must be filed within 2 years from the date of payment of tax under the correct head.
+ Q: Can I adjust the wrongfully paid CGST/SGST directly against IGST liability using Form PMT-09?
A: No. Form PMT-09 can only transfer unutilized balances available in the Electronic Cash Ledger. It cannot adjust or reallocate taxes already paid toward liabilities in finalized GSTR-3B returns. You must pay the correct tax first and file a refund for the wrong tax.
+ Q: Which refund category should I select on the GST portal for Section 77 refunds?
A: On the GST portal, under Services > Refunds > Application for Refund, select the category “Tax paid on an intra-State supply which is subsequently held to be inter-State supply and vice versa”.
+ Q: What happens if the tax officer demands interest on the delayed payment of the correct tax?
A: You can submit a formal reply citing Section 77(2) of the CGST Act and Section 19(2) of the IGST Act, along with Circular No. 162/18/2021-GST, which explicitly clarifies statutory immunity from interest in such cases.
About this article: Based on Section 77 of CGST Act, 2017, Section 19 of IGST Act, 2017, Rule 89(1A), and Circular No. 162/18/2021-GST.
Disclaimer: This article is for educational purposes only and should not be considered legal tax advice.
