
💡 Key Takeaways: Form GST PMT-03
- What it is: Form GST PMT-03 is a statutory order passed by a Proper Officer to re-credit a rejected GST refund amount back to the taxpayer’s Electronic Credit or Cash Ledger.
- Why it matters: When you file a refund claim (RFD-01), the portal automatically debits your ledger. If the refund is rejected, PMT-03 restores that balance so you don’t lose the money.
- Governing Rule: The process is governed by Rule 86(4) and Rule 87(11) of the CGST Rules, 2017.
- Action Required: Taxpayers do not file PMT-03; the tax officer issues it. However, taxpayers must track their portal to ensure the officer hasn’t forgotten to issue the re-credit order after a rejection.
Filing a GST refund can be an anxious process for businesses, particularly because the moment you submit Form GST RFD-01, the requested refund amount is immediately debited (deducted) from your Electronic Credit Ledger or Electronic Cash Ledger. But what happens if the tax officer scrutinizes your application and decides to reject your claim, either fully or partially?
Is your money gone forever? The simple answer is no. To restore your deducted balance, the GST portal relies on a specific procedural mechanism: Form GST PMT-03.
The Lifecycle of a Debited Ledger Balance
To understand the importance of PMT-03, you must first understand the journey of your ledger balance during a refund claim:
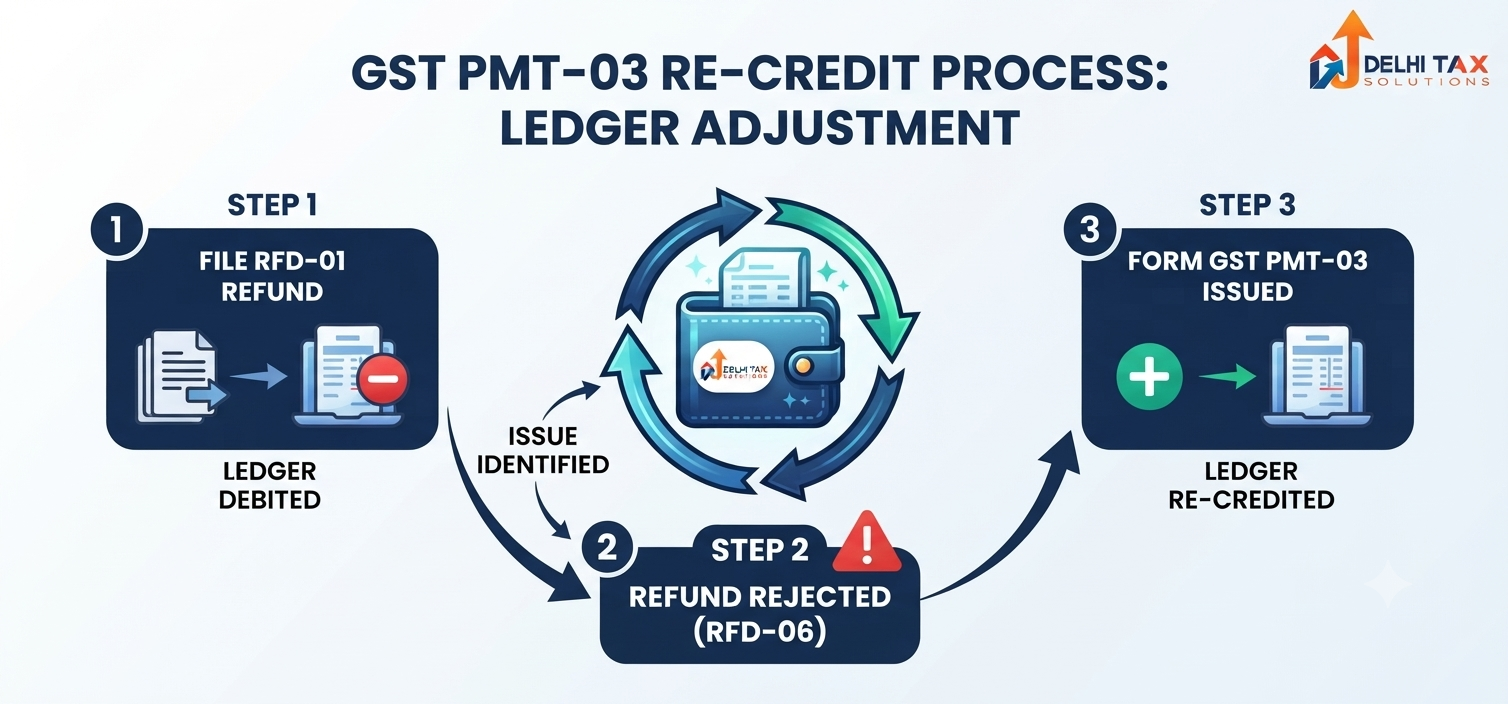
🔄 The Debit & Credit Cycle
Step 1 (Debit): Taxpayer files RFD-01. The portal auto-debits the Electronic Credit/Cash Ledger.
Step 2 (Rejection): The Proper Officer issues a rejection order in Form GST RFD-06.
Step 3 (Re-Credit): The Proper Officer immediately issues an order in Form GST PMT-03, which commands the portal to add the rejected amount back into the taxpayer’s ledger.
When is PMT-03 Issued?
According to Rule 86(4) of the CGST Rules, Form GST PMT-03 is issued in the following scenarios:
- Full Rejection: Your entire refund claim is deemed ineligible and rejected via RFD-06. The full debited amount is re-credited.
- Partial Rejection: You claimed ₹100,000. The officer sanctions ₹80,000 but rejects ₹20,000. PMT-03 will be issued to re-credit exactly ₹20,000 to your ledger.
- Deficiency Memo (RFD-03): If an application is found incomplete, the officer issues a Deficiency Memo. Upon issuance, the portal should automatically re-credit the amount to the ledger. If it fails technically, PMT-03 may be used.
Who Generates PMT-03?
A common misconception among taxpayers is searching for a way to file PMT-03 on the GST portal. Taxpayers cannot file PMT-03.
PMT-03 is an administrative order. It is generated and authorized digitally by the jurisdictional Proper Officer who handled your refund case. Once the officer signs and issues PMT-03, the GSTN portal’s backend processes the command and updates your ledger automatically.
The Practical Hurdle: Officer Negligence
While the law states that PMT-03 should be issued simultaneously with the rejection order (RFD-06), practical ground reality is often different.
⚠️ What if PMT-03 is NOT issued?
Often, tax officers issue the rejection order (RFD-06) and close the file, forgetting to initiate PMT-03. In such cases, your refund is rejected, AND your ledger remains depleted. Your working capital becomes stuck in a technical void.
How to solve this: If you receive a rejection order but do not see a corresponding credit in your Electronic Ledger within 24-48 hours, you must immediately file a written grievance or physical representation to the jurisdictional officer requesting the issuance of Form GST PMT-03.
Difference Between PMT-03 and PMT-03A
In 2022, the CBIC introduced a new form called PMT-03A via Notification No. 14/2022. It is important not to confuse the two:
| Feature | Form GST PMT-03 | Form GST PMT-03A |
|---|---|---|
| Primary Use Case | Re-credit of a refund that was rejected by the officer. | Re-credit when taxpayer pays back an erroneously granted refund via DRC-03. |
| Trigger Event | Issuance of RFD-06 (Rejection Order). | Payment of tax and interest via DRC-03 by the taxpayer. |
| Requirement from Taxpayer | None (Automatic post-rejection). | Must file a written request to the officer after making DRC-03 payment. |
Is Your Electronic Credit Ledger Balance Stuck?
Was your GST refund rejected, but the tax department hasn’t restored your debited ITC balance? Missing PMT-03 orders can lock up crucial working capital. Our GST experts can help you liaise with jurisdictional authorities and retrieve your rightful ledger balance.
Reach out to Delhi Tax Solutions today for swift resolution of pending GST refund and ledger disputes!
Frequently Asked Questions (FAQs)
+ Q: Can I file Form PMT-03 on the GST Portal?
A: No. PMT-03 is an official order that can only be generated and issued by the Proper Officer handling your refund case. Taxpayers can only view the re-credited amount in their Electronic Credit/Cash Ledger.
+ Q: How long does it take for PMT-03 to reflect in my ledger?
A: Once the officer digitally issues Form PMT-03, the re-credit should reflect in your Electronic Credit Ledger or Cash Ledger almost instantaneously or within 24 hours.
+ Q: What should I do if my refund is rejected but PMT-03 is not issued?
A: If the officer issued RFD-06 (Rejection) but forgot to issue PMT-03, you must draft a formal application to the jurisdictional Proper Officer requesting the immediate issuance of the PMT-03 order to re-credit your ledger.
+ Q: Does a Deficiency Memo (RFD-03) require a PMT-03 for re-credit?
A: Usually, the issuance of a Deficiency Memo (RFD-03) triggers an auto-re-credit of the debited amount to your ledger. However, if a technical glitch occurs and the auto-credit fails, the officer may issue PMT-03 to manually restore the balance.
About this article: Based on Rule 86(4) and Rule 87(11) of the CGST Rules, 2017, and relevant CBIC circulars. Updated for 2026.
Disclaimer: This article is for informational and educational purposes only and should not be considered legal or financial advice.
