
? Key Takeaways
- Income from let-out property begins with determining Gross Annual Value (GAV) based on rent and municipal valuation.
- Actual municipal taxes paid by the owner during the financial year are fully deductible from GAV.
- A flat 30 percent standard deduction is available on Net Annual Value for repairs and maintenance.
- Home loan interest under Section 24(b) can be claimed with no upper ceiling for fully let-out properties.
- Accurate reporting of rental income requires reconciling lease agreements with annual ITR filings.
Owning rental real estate in urban centers provides steady cash flow, but computing tax liabilities requires meticulous adherence to statutory guidelines. Mastering income from let out property calculation is essential for landlords and property investors wanting to optimize their tax outgo legally. Under the Income-tax Act, rental earnings are taxed under the specific head of “Income from House Property,” requiring property owners to compute Gross Annual Value, subtract municipal levies, and claim allowable deductions systematically.
Navigating these calculations requires aligning property revenue records with direct tax standards. Official guidelines published by the Income Tax Department dictate how rental receipts and deductions must be reported. Landlords operating in real estate markets across Delhi NCR must manage these computations alongside routine Income Tax filings, Company Registration procedures, and TDS obligations on commercial leases.
This authoritative advisory guide breaks down the step-by-step formula for determining Net Annual Value, claiming municipal tax deductions, applying standard deductions, and evaluating home loan interest benefits.
What is the step-by-step formula for income from let-out property calculation?
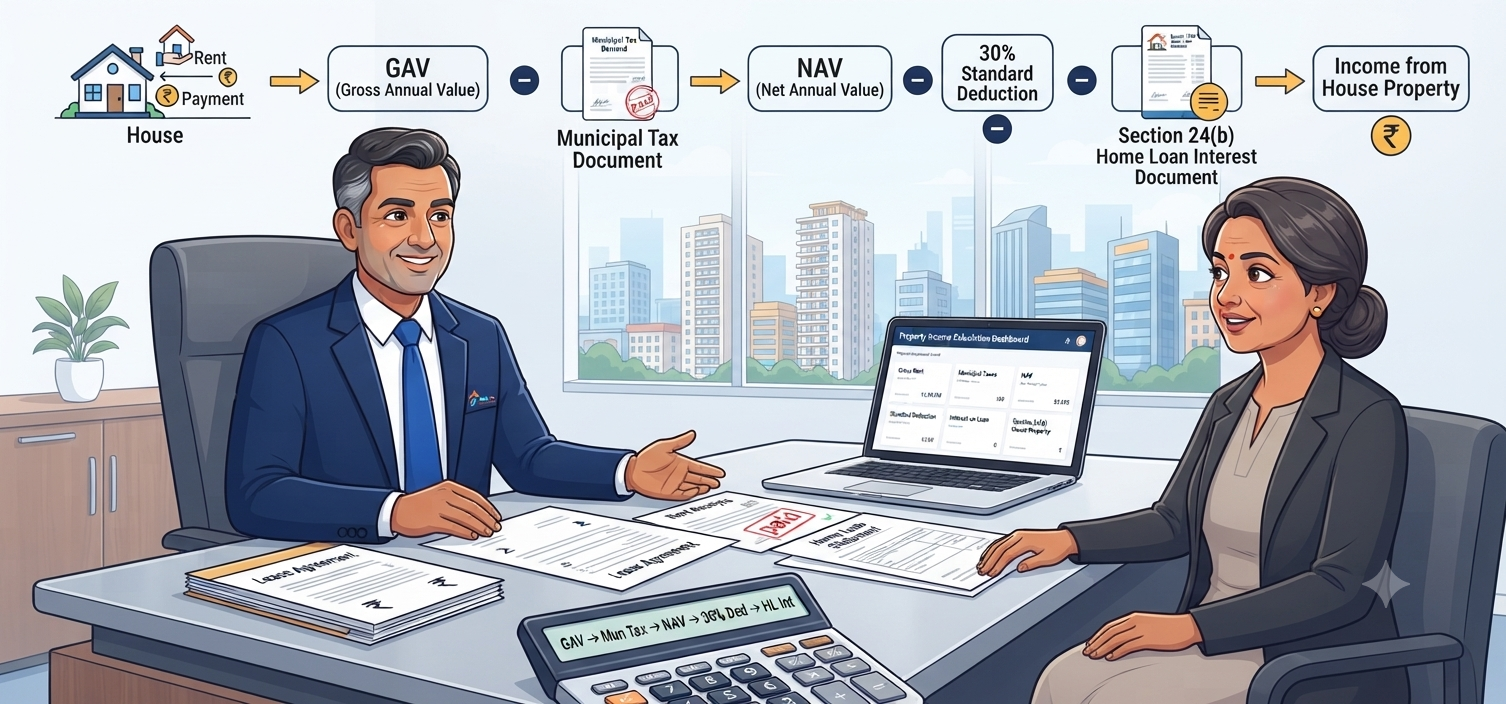
Calculating the income from a let-out property follows a precise statutory sequence defined under Section 23 of the Income-tax Act. According to policy advisories released by the Press Information Bureau, the computation starts by determining the Gross Annual Value (GAV) of the property, which is the higher of expected rent (municipal valuation or fair rent) and actual rent received, adjusted for vacancy periods. Once GAV is established, the property owner subtracts actual municipal taxes paid during the financial year to arrive at the Net Annual Value (NAV).
How does the 30 percent standard deduction apply to rental income?
Applying the 30 percent standard deduction rental income provision offers significant relief to property owners by automatically accounting for repair, maintenance, painting, and insurance costs. Regulatory frameworks monitored by the Ministry of Corporate Affairs establish that this flat 30 percent deduction is calculated directly on the Net Annual Value, regardless of whether the landlord actually spent money on repairs during the financial year.
Automatic statutory allowance
Landlords do not need to present bills, invoices, or receipts for repair work; the 30 percent deduction is granted unconditionally on NAV.
Exclusion of utility bills
If the rental agreement includes separate charges for electricity, water, or maintenance services, those specific utility components are excluded from rental income computations.
What are the rules for municipal tax deduction on rental property?
Claiming the municipal tax deduction rental property allowance requires satisfying specific conditions under Indian tax law. Regulatory circulars monitored by the Reserve Bank of India and tax authorities state that municipal taxes (such as house tax or property tax levied by civic bodies like MCD) are deductible only if they are actually paid by the owner during the relevant financial year. Taxes due but unpaid cannot be claimed.
Owner payment mandate
The municipal tax must be paid by the property owner; if the tenant pays the property tax directly, no deduction is allowed to the landlord.
Deduction timing rule
Even if municipal taxes pertain to previous financial years, they become deductible in the year in which the actual payment transaction is executed by the owner.
| Computation Stage | Statutory Formula / Rule | Applicable Tax Provision |
|---|---|---|
| Gross Annual Value (GAV) | Higher of Expected Rent vs. Actual Rent (adjusted for vacancy) | Section 23(1)(a) & (b) |
| Net Annual Value (NAV) | Gross Annual Value minus Actual Municipal Taxes Paid by Owner | Section 23(1) proviso |
| Standard Deduction | Flat 30% of Net Annual Value for repairs and maintenance | Section 24(a) |
| Home Loan Interest Deduction | Actual interest paid on capital borrowed (No upper limit for let-out) | Section 24(b) |
? Quick Summary
Subtract municipal taxes from GAV to get NAV, deduct 30% for maintenance, and subtract home loan interest to arrive at taxable house property income.
How is net annual value calculation performed for residential properties?
Executing the net annual value calculation requires comparing municipal valuation, fair rent, standard rent, and actual rent received. Based on cases handled by our CA team at Delhi Tax Solutions, property owners frequently overlook vacancy adjustments or unrealized rent deductions when filing annual tax returns. Proper documentation, including registered lease deeds and tenant PAN details for high-value rentals, is essential to substantiate these figures during tax assessments.
Accounting for vacancy periods
If a property remained vacant for a part of the year and actual rent dropped solely due to that vacancy, the lower actual rent is accepted as GAV.
Deducting unrealized rent
Uncollectible rent from defaulting tenants can be excluded from GAV, provided statutory conditions under Rule 4 of Income-tax Rules are strictly fulfilled.
How do home loan interest and other deductions impact tax liability?
Maximizing tax efficiency involves combining standard deductions with home loan interest benefits under Section 24(b). Unlike self-occupied properties where home loan interest is capped at ?2,00,000 per financial year, let-out properties allow landlords to claim the entire actual interest paid on borrowed capital without any monetary ceiling. Furthermore, pre-construction interest can be claimed in five equal installments starting from the year of completion, alongside required GST Registration compliance for commercial properties.
Uncapped interest deduction
The full amount of interest paid on home loans taken for purchasing, constructing, or repairing the let-out property is fully deductible from NAV.
Loss from house property
If total deductions (30 percent standard deduction plus home loan interest) exceed NAV, the resulting loss can be set off against other income heads up to ?2,00,000.
Talk to a Delhi Tax Solutions expert to get your property tax computations and ITR filings managed seamlessly today.
About this article: Researched using official government sources and Delhi Tax Solutions’ in-house tax advisory team. Last updated August 2026.
This article is for general informational purposes and is not a substitute for personalised professional tax advice.
Frequently Asked Questions (FAQs)
Q: How is income from let out property calculated under the Indian Income Tax Act?
A: Income from let-out property is calculated by first determining the Gross Annual Value (GAV) based on expected and actual rent. From GAV, actual municipal taxes paid by the owner during the year are subtracted to arrive at the Net Annual Value (NAV). Next, a flat 30 percent standard deduction and actual home loan interest under Section 24 are deducted to arrive at the final taxable house property income.
Q: Are municipal taxes fully deductible when computing rental property income?
A: Municipal taxes are fully deductible from the Gross Annual Value, but only on an actual payment basis. The tax payment must be made by the property owner during the relevant financial year. If municipal taxes are paid by the tenant, or if they remain unpaid at the end of the financial year, no deduction is permitted under tax law.
Q: How does the 30 percent standard deduction apply to residential and commercial rent?
A: The 30 percent standard deduction applies automatically to the Net Annual Value of both residential and commercial let-out properties. It is granted by law as a presumptive allowance for repairs, maintenance, and insurance, meaning landlords do not need to provide actual expense receipts or bills to claim this deduction.
Q: What is the maximum home loan interest deduction allowed on let-out properties?
A: Unlike self-occupied properties where home loan interest is capped at ?2,00,000 per financial year, let-out and commercial properties permit landlords to claim the entire actual interest paid on borrowed capital without any upper monetary ceiling, subject to proper loan documentation and property construction completion.
Q: How do landlords report unrealized rent and vacancy periods in annual ITR filings?
A: Landlords report vacancy periods and unrealized rent by adjusting the Gross Annual Value calculation. When a property remains vacant for part of the year or rent from a defaulting tenant cannot be realized, the statutory formula allows discounting those specific periods, provided legal conditions and tenant default documentation criteria are satisfied.
