
? Key Takeaways
- An HUF is treated as a distinct legal and financial person under Section 2(31).
- Forming an HUF provides an independent basic tax exemption limit and deductions.
- Creating an HUF requires a formal written deed, corpus, and bank account.
- Income splitting across family entities lowers cumulative tax liability effectively.
- Expert CA assistance ensures smooth setup and robust regulatory compliance.
Maximizing disposable income while maintaining strict statutory compliance requires strategic foresight, making HUF tax planning India one of the most effective tools available to Indian families. Under the Income Tax Act, a Hindu Undivided Family is recognized as a completely separate assessable entity distinct from its individual members. This unique legal status allows taxpayers to split their income streams, claim a separate basic exemption limit, and multiply available deductions under sections like 80C and 80D. For high-earning individuals, business owners, and professionals operating in Delhi/NCR, leveraging this structure can yield substantial annual savings. Our CA team at Delhi Tax Solutions frequently guides clients through establishing and structuring these family entities correctly.
Understanding HUF Separate Entity Income Tax
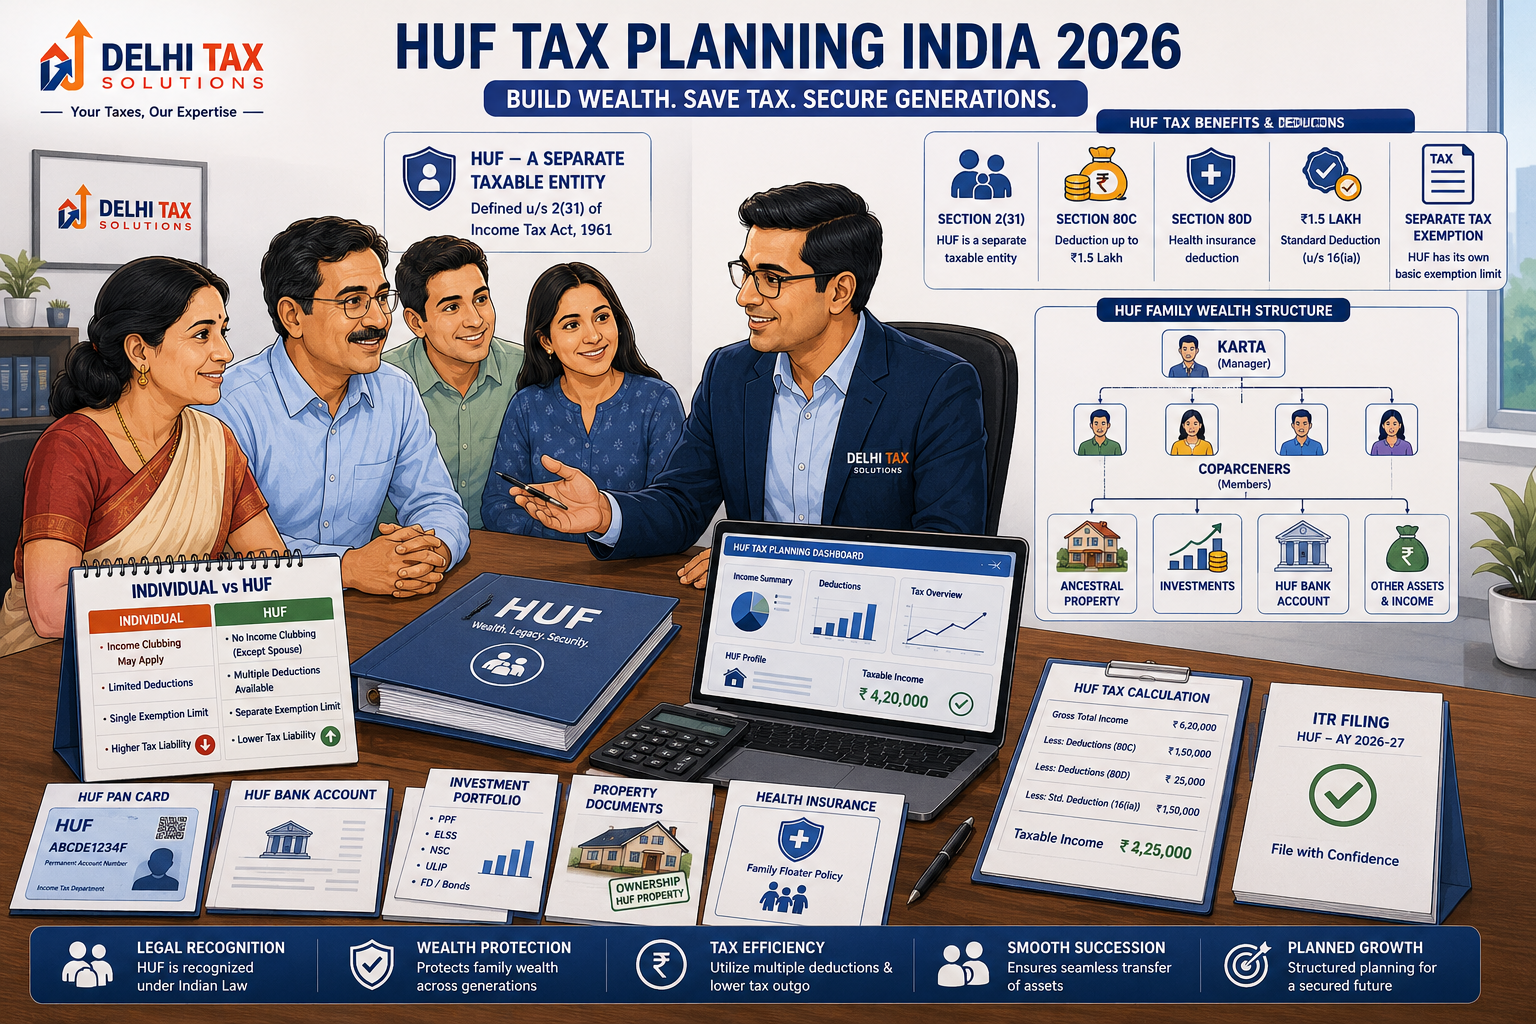
Under Section 2(31) of the Income Tax Act, an HUF is classified as a distinct “person” for taxation purposes. This means the family entity files its own independent tax return (ITR) using a dedicated Permanent Account Number. Because it is treated separately from individual members, an HUF enjoys its own tax slab rates and basic exemption threshold, mirroring individual taxpayers. When income from ancestral property, business ventures, or investments is channeled through this separate entity, it escapes higher personal slab rates. According to official data from the Income Tax Department, thousands of taxpayers utilize this framework annually to optimize their family’s cumulative financial posture without breaching any legal boundaries.
A Step-by-Step Guide on How to Create HUF
Setting up a valid Hindu Undivided Family requires adherence to traditional Hindu law combined with modern regulatory standards. First, an HUF comes into existence automatically upon marriage, but formal tax recognition requires a formal declaration. Second, you must draft a formal HUF deed on stamp paper, explicitly listing the Karta (manager, typically the eldest male or female family member), coparceners (family members with birth rights), and the initial corpus. Third, pool ancestral property, gifts, or family contributions to form the foundational corpus. Fourth, apply for a dedicated PAN card using the prescribed Form 49A. Finally, open a current or savings bank account in the name of the HUF to manage its financial transactions transparently. Proper documentation prevents future disputes during Income Tax Filing audits.
Securing and Managing Your Dedicated HUF PAN Card
Acquiring a dedicated HUF PAN card is the operational milestone that transforms a family arrangement into a functional tax-saving unit. To apply, the Karta must submit Form 49A along with an affidavit declaring the names of all coparceners, an HUF stamp or seal, and proof of address for the family business or residence. Once issued, this PAN allows the entity to buy mutual funds, open fixed deposits, execute property transactions, and manage business ventures independently. If your family operates commercial enterprises, integrating this structure alongside your regular compliance requirements—such as GST Registration—ensures seamless commercial operations across all business verticals without administrative bottlenecks.
Exploring Essential HUF Tax Benefits and Exemptions
The primary driver for establishing this entity is the extensive array of deductions available under Indian tax statutes. An HUF can independently claim deductions under Section 80C (up to ?1.5 lakh for PPF, ELSS, or life insurance), Section 80D for health insurance premiums, and even standard deductions on rental properties. Furthermore, property transfers must be handled carefully to avoid clubbing provisions under Section 64. Reviewing how individual brackets compare against family entities clarifies these advantages clearly.
| Tax Parameter | Individual Assessment | HUF Assessment |
|---|---|---|
| Legal Entity Status | Single natural person | Separate legal person under Sec 2(31) |
| Basic Exemption Limit | Applicable per individual slab | Separate, independent exemption slab |
| Deduction 80C Limit | ?1,50,000 maximum cap | Separate ?1,50,000 maximum cap |
| Property Ownership | Owned individually | Owned collectively by coparceners |
? In a Nutshell
An HUF acts as a secondary financial container. By diverting eligible family investments and rental yields into this entity, you effectively double your tax exemption limits and deduction caps within the bounds of Indian tax law.
Strategic Tax Saving Through HUF Formations
Effective execution of tax saving through HUF frameworks relies heavily on strategic asset allocation. For instance, if family members gift cash or ancestral property to the HUF, the income generated from those assets is assessed in the hands of the HUF rather than the individual donor, provided clubbing rules are navigated with CA guidance. Additionally, paying a reasonable salary to the Karta or coparceners for managing business assets owned by the HUF can be claimed as a business expense by the HUF, reducing its taxable profits. According to policy updates highlighted by the Press Information Bureau, structural tax simplifications continue to emphasize transparent disclosures. Proper planning also extends to real estate holdings, where Property Tax liabilities can be assigned to the entity holding the title deed.
Regulatory Compliance and Expert Advisory Insights
Maintaining an HUF demands rigorous record-keeping to satisfy statutory scrutiny from regulatory bodies. Every financial transaction—from capital infusion to investment returns—must flow exclusively through the official HUF bank account. Mixing personal funds with HUF funds is a critical compliance error that can void the entity’s separate tax status during scrutiny by the Ministry of Corporate Affairs or tax authorities. Furthermore, if your family venture expands into active commercial trading or manufacturing, ensure that all statutory registrations, including Company Registration or MSME documentation, are updated. For banking transactions and interest earnings, monitoring TDS certificates in Form 26AS ensures no tax credits are missed. As noted by our expert advisory team, consulting a qualified Chartered Accountant before executing asset transfers prevents costly litigation and ensures long-term wealth preservation.
About this article: Researched using official government sources and Delhi Tax Solutions’ in-house tax advisory team. Last updated August 2026.
Frequently Asked Questions (FAQs)
Q: Can a Hindu Undivided Family (HUF) have its own PAN card?
A: Yes, a Hindu Undivided Family is recognized as a distinct legal and assessable entity under Section 2(31) of the Income Tax Act, and it must obtain its own dedicated Permanent Account Number (PAN) card. The Karta of the HUF applies for this PAN by submitting Form 49A along with an affidavit and proof of the family’s joint status, allowing the entity to file separate tax returns, open bank accounts, and invest independently.
Q: How is a HUF created for tax planning purposes?
A: An HUF comes into existence automatically upon marriage as part of Hindu personal law, but establishing it for tax planning requires formal documentation. You must draft a written HUF deed on stamp paper specifying the Karta, coparceners, and initial corpus. This corpus can be formed using ancestral property or gifts from family members. Once the deed is executed, you apply for an HUF PAN card and open a dedicated bank account to commence operations.
Q: What are the tax benefits of forming an HUF in India?
A: Forming an HUF grants access to a completely separate basic tax exemption limit and independent deduction caps under sections like 80C (up to ?1.5 lakh) and 80D. By shifting eligible income streams—such as rental income from ancestral properties or investment returns—into the HUF, families can split their total income across multiple entities, thereby reducing their overall tax slab rate and cumulative annual tax outgo.
Q: Can property be transferred to an HUF to save tax?
A: Yes, property can be transferred to an HUF, but it must be executed carefully to comply with income tax laws. Ancestral property automatically belongs to the HUF. However, transferring self-acquired individual property to the HUF can attract clubbing of income provisions under Section 64 or gift tax rules if not structured correctly as a formal family settlement or registered gift deed, making professional CA guidance essential.
Q: Who can be the Karta of an HUF?
A: Traditionally, the eldest male member of the family acts as the Karta, managing the daily affairs and financial decisions of the Hindu Undivided Family. However, following landmark amendments to the Hindu Succession Act, female coparceners also hold equal rights, and legal precedents permit a female family member to act as the Karta of the HUF in the absence of senior male members or upon unanimous family consensus.
