
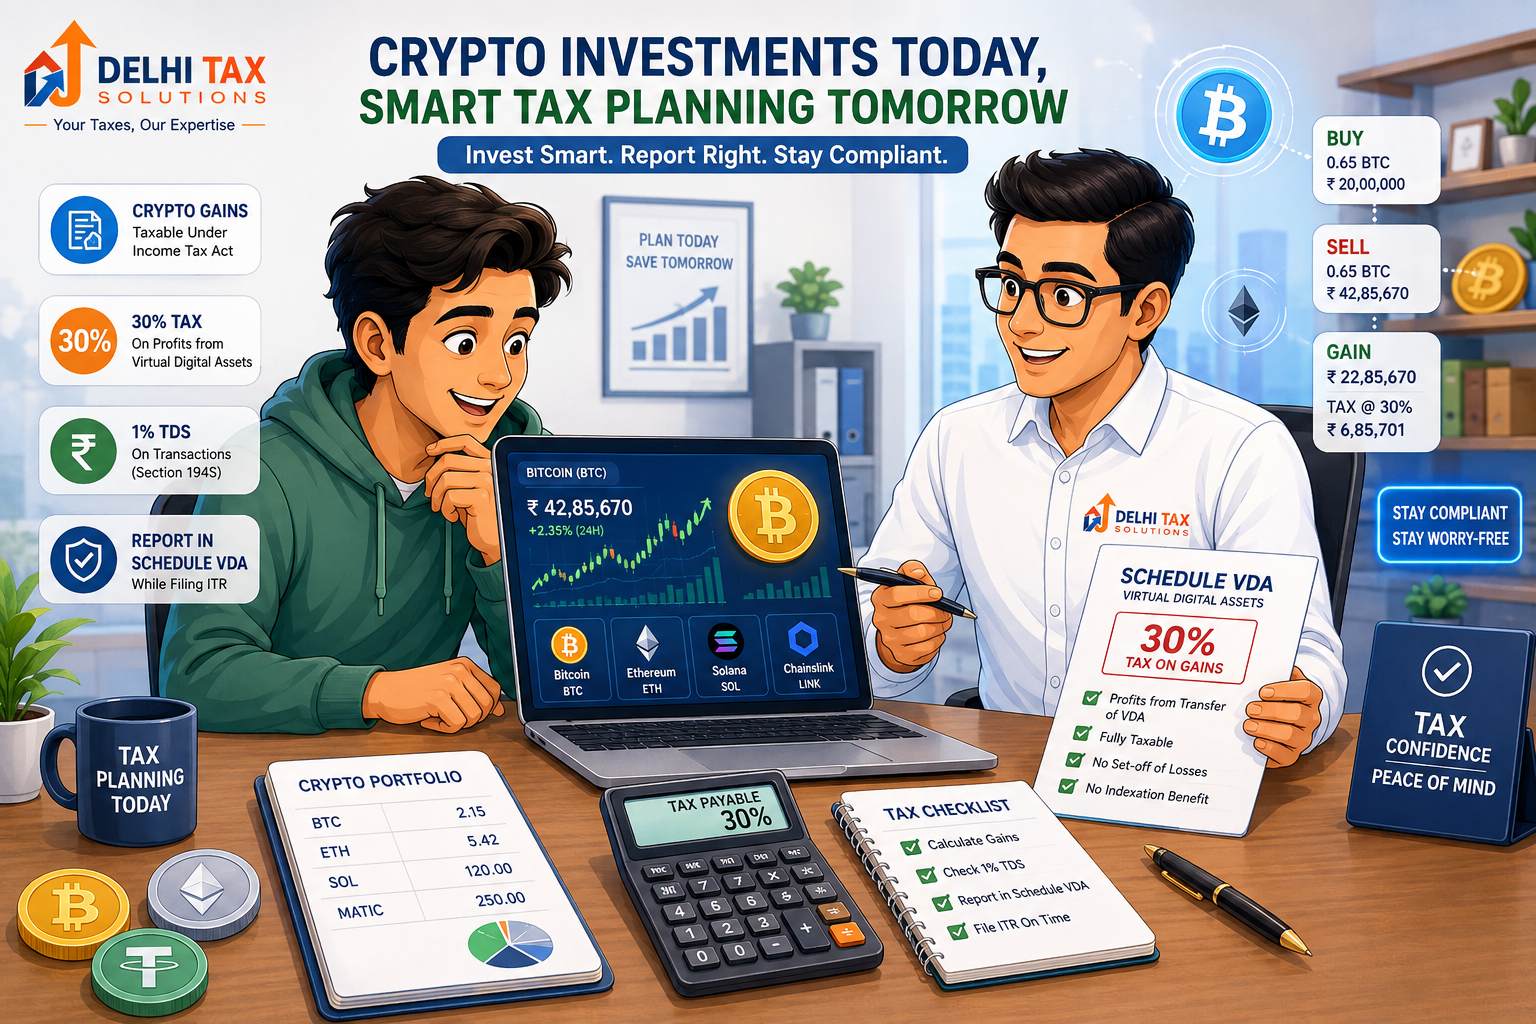
💡 Key Takeaways
- Mastering how to calculate crypto tax India ensures complete compliance under Section 115BBH of the Income Tax Act.
- All Virtual Digital Asset profits attract a flat 30% tax on VDA gains without basic exemption slab benefits.
- Tax law strictly prohibits setting off crypto losses against other crypto gains or business income.
- Exchanges deduct 1% TDS on transactions exceeding specific monetary thresholds during transfers.
- Expert Chartered Accountant filing prevents costly scrutiny notices from tax authorities.
Navigating the digital asset ecosystem across India requires strict financial tracking and accurate tax computation. When digital currency enthusiasts trade Bitcoin, Ethereum, or altcoins on domestic and international platforms, every profitable transaction triggers specific fiscal obligations. Understanding how to calculate crypto tax India is essential for avoiding aggressive scrutiny notices and heavy monetary penalties from tax administrators. Computing your liabilities correctly safeguards your investment portfolio and keeps your financial records pristine.
Operating within India’s evolving financial framework demands rigorous adherence to statutory guidelines introduced for Virtual Digital Assets. The Income Tax Department enforces clear regulations governing digital tokens, non-fungible tokens, and decentralized currencies. Knowing the precise mathematical formulas and reporting protocols ensures peace of mind during every annual filing cycle.
How to Calculate Crypto Tax in India and Determine VDA Liabilities?
Calculating crypto tax in India involves determining the net profit from each Virtual Digital Asset transfer by subtracting only the original acquisition cost from the sale consideration. Tax law prohibits deducting any other expenses, trading fees, or infrastructural overheads except the bare purchase price. Once the net taxable gain is established, a flat tax rate of 30 percent plus applicable surcharge and cess is levied directly on the profit without factoring in individual income tax slab rates.
What Is the Standard Formula for Cryptocurrency Tax Calculation?
Executing an accurate cryptocurrency tax calculation requires separating every individual trade and transaction throughout the financial year. Taxpayers cannot aggregate total portfolio losses against total profits because statutory provisions treat each coin transfer as an isolated taxable event. If you buy a token for ₹50,000 and sell it later for ₹80,000, your net taxable gain is precisely ₹30,000, attracting a flat tax of ₹9,000 plus applicable surcharges.
According to fiscal policy updates published by the Press Information Bureau, automated tracking systems monitor exchange data feeds to verify taxpayer disclosures. Ensuring complete transparency during your initial GST Registration and corporate filings prevents cross-departmental income discrepancies.
How Does the 30% Tax on VDA Gains Impact Retail Investors?
The imposition of a strict 30% tax on VDA gains under Section 115BBH of the Income-tax Act means that profits derived from digital assets are taxed at the highest marginal rate. Furthermore, taxpayers cannot utilize basic exemption thresholds against crypto earnings if their total income falls below taxable brackets. This rule ensures that even small-time retail participants owe tax on their digital profits regardless of other income exemptions.
Guidelines issued by the Income Tax Department mandate that all digital asset earnings must be reported in Schedule VDA of the income tax return. Maintaining verified corporate documentation through expert Company Registration structures protects corporate entities engaging in treasury crypto holdings.
What Are the Core Requirements for Crypto Tax Filing India?
Executing a seamless crypto tax filing India process requires compiling detailed transaction histories from every centralized and decentralized exchange used during the financial year. Taxpayers must report date-wise purchase prices, sale values, transfer fees, and TDS deducted at source on specific forms. Failing to disclose these earnings invites severe legal penalties and interest charges.
| Tax Parameter | Virtual Digital Assets (VDA) | Traditional Equity Shares |
|---|---|---|
| Flat Tax Rate | 30% Flat Rate (Section 115BBH) | 10% to 20% (Capital Gains) |
| Loss Set-Off Rule | Not Allowed (Cannot offset losses) | Allowed (Long/Short-term rules apply) |
| Deduction of Expenses | Only Acquisition Cost Allowed | Brokerage and Transfer Costs Allowed |
Official records from the Ministry of Corporate Affairs confirm that corporate balance sheets holding digital assets must adhere to strict accounting disclosure standards. Securing proper Business Licenses ensures that fintech startups operate within fully legal frameworks.
How Do VDA Tax Slab Rules and TDS Deductions Function?
Understanding VDA tax slab rules requires recognizing that digital earnings remain isolated from standard income slab benefits. In tandem with the 30 percent tax, Section 194S mandates a 1 percent Tax Deducted at Source on crypto transfers exceeding ₹10,000 in a financial year for specified individuals. This TDS acts as an advance tax credit that taxpayers can claim during their annual return filing.
⚡ In a Nutshell
Always track every individual crypto trade ledger to compute your 30% tax liability accurately without claiming disallowed trading loss offsets.
What Expert CAs Recommend for Accurate Crypto Tax Compliance
According to Delhi Tax Solutions’ in-house tax advisory team, successful crypto tax reporting depends on advanced portfolio reconciliation software and careful verification of Form 26AS and AIS statements. Integrating professional tax planning through Direct Tax Code frameworks ensures complete synchronization across all personal and corporate income streams.
Partnering with experienced Chartered Accountants eliminates calculation errors, secures correct TDS credit claims, and protects investors from departmental scrutiny notices.
Conclusion
Navigating cryptocurrency taxation in India requires meticulous record-keeping and strict adherence to statutory rules. Remember that computing profits without loss set-offs, paying the flat 30 percent levy, and reconciling 1 percent TDS certificates protect your finances from severe penalties. Do not let digital asset compliance become an overwhelming burden. Talk to a Delhi Tax Solutions expert to get your crypto tax calculations and ITR filing completed accurately by our expert CA team. Professional guidance ensures total financial security.
About this article: Researched using official government sources and Delhi Tax Solutions’ in-house tax advisory team. Last updated August 2026.
Frequently Asked Questions (FAQs)
+ Q: How do Indian taxpayers calculate and pay tax on crypto trading gains under Section 115BBH?
A: Indian taxpayers calculate crypto trading gains by subtracting the exact acquisition cost from the sale consideration for each individual Virtual Digital Asset transfer recorded on platforms linked via the official Income Tax Department portal. Statutory rules under Section 115BBH mandate a flat 30 percent tax rate plus applicable surcharge and cess on these net profits without allowing deductions for infrastructure or trading fee expenses. Taxpayers must report these earnings in Schedule VDA during annual return filing and pay any outstanding self-assessment tax before submission.
+ Q: Can investors set off losses incurred on one cryptocurrency against profits made on another in India?
A: No, Indian tax law strictly prohibits setting off losses incurred from the transfer of any Virtual Digital Asset against profits derived from another digital asset. If an investor records a net loss of ₹20,000 on Bitcoin trading and a net profit of ₹50,000 on Ethereum trading, tax must be paid on the full ₹50,000 profit. Furthermore, crypto losses cannot be carried forward to subsequent financial years or offset against normal business and capital gains income streams.
+ Q: What is the exact role and deduction rule for the 1% TDS deducted on crypto transfers?
A: Under Section 194S of the Income-tax Act, domestic cryptocurrency exchanges and buyers are required to deduct 1 percent Tax Deducted at Source on consideration paid for transferring Virtual Digital Assets when transaction values exceed ₹10,000 in a financial year (or ₹50,000 for specified individuals). This deducted amount reflects directly in the taxpayer’s Form 26AS and Annual Information Statement. Taxpayers can claim this 1 percent TDS as a credit to offset their final 30 percent VDA tax liability when filing their annual income tax returns.
+ Q: Which ITR form must taxpayers use to report cryptocurrency and Virtual Digital Asset earnings in India?
A: Taxpayers earning capital gains or casual income from cryptocurrency transactions must file their returns using ITR-2 or ITR-3 depending on whether their digital asset activities constitute capital investments or regular business income. The return must include a dedicated Schedule VDA where investors disclose detailed transactional heads including date of acquisition, date of transfer, sale consideration, cost of acquisition, and net taxable income computed for each digital asset held during the financial year.
+ Q: What are the legal penalties for failing to report crypto income during annual tax return filing?
A: Failing to report cryptocurrency income or concealing Virtual Digital Asset profits during annual tax return filing attracts stringent penalties under the Income-tax Act. Tax authorities can levy a 50 percent penalty on under-reported or concealed tax amounts alongside mandatory interest charges under Sections 234A, 234B, and 234C. Persistent non-compliance or willful tax evasion can also trigger prosecution proceedings and rigorous imprisonment terms ranging from three months up to seven years under statutory anti-evasion laws.
