
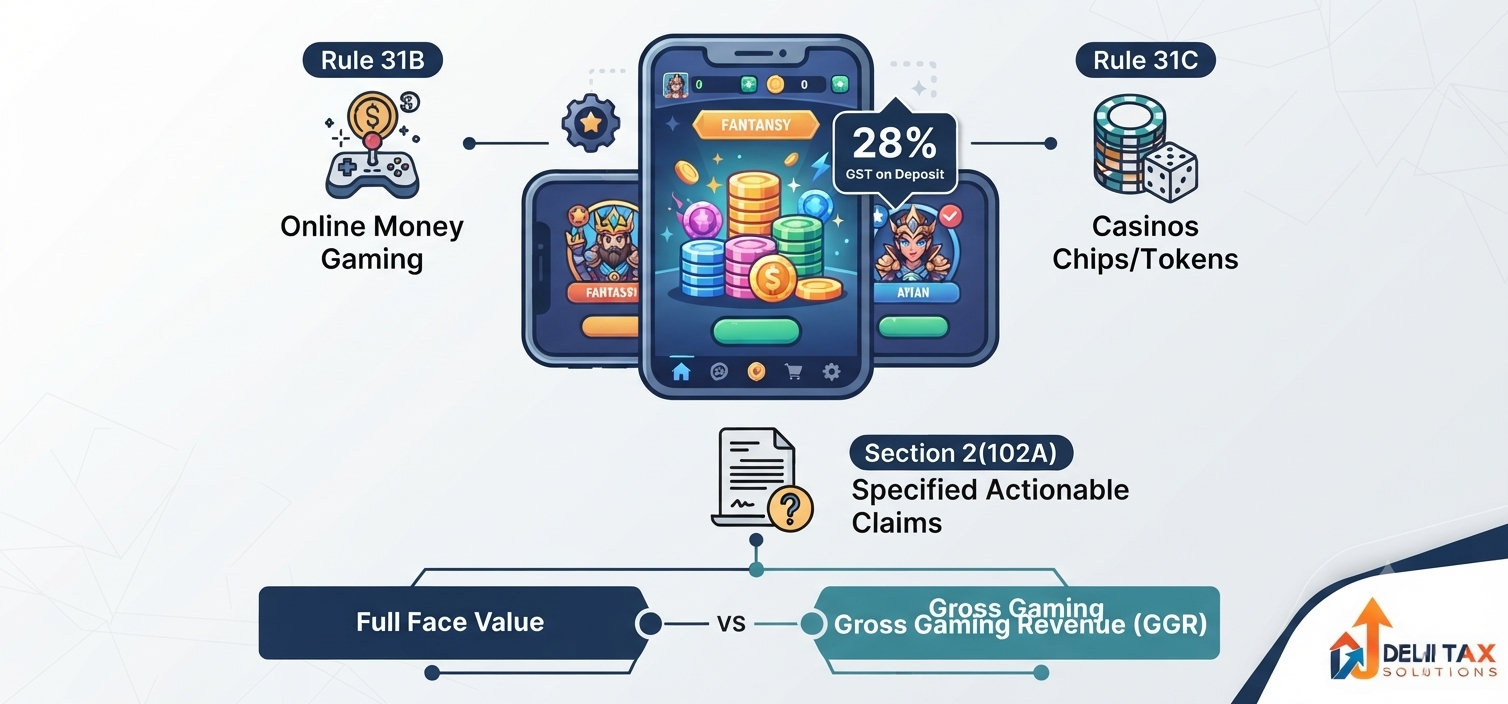
💡 Key Takeaways: GST on Online Gaming & Casinos
- 28% Uniform Tax Rate: GST is applicable at a flat rate of 28% on the entire entry amount deposited by players in online money gaming and casinos.
- Full Face Value vs Platform Fee: Unlike earlier practices where companies paid 18% GST on platform fees (Gross Gaming Revenue), tax is now calculated on the initial deposit amount without deducting platform charges or prize pools.
- Legal Amending Definitions: Amendments to the CGST Act introduced Section 2(80A) for “Specified Actionable Claim” and Section 2(102A) for “Online Money Gaming.”
- Valuation Rules 31B & 31C: Rule 31B governs valuation for online money gaming deposits, while Rule 31C prescribes valuation for tokens and chips purchased in casinos.
- Offshore Platforms Mandate: Foreign online gaming platforms serving Indian players must register under simplified IGST mechanisms or face domain blocking under Section 14A of the IGST Act.
The online gaming industry in India has experienced exponential growth over recent years, transitioning from casual leisure to high-stakes fantasy sports, online rummy, and virtual card tournaments. To establish tax parity across betting, gambling, horse racing, and digital staking platforms, the GST Council enacted comprehensive legislative changes. Similar to regulatory frameworks established for other independent digital services such as those detailed in our GST Guide for Freelancers & Consultants, online gaming now follows strict statutory compliance norms.
The core shift lies in moving away from taxing merely the platform service fee to levying GST on the entire initial entry deposit. In this detailed guide, we break down the statutory definitions, valuation rules, and tax compliance framework governing online gaming GST.
Key Statutory Definitions Under CGST Act
To eliminate ambiguity regarding whether a game is based on skill or chance, statutory amendments redefined actionable claims and money gaming under the Central Goods and Services Tax Act, 2017.
1. Specified Actionable Claim — Section 2(80A)
Actionable claims were historically excluded from GST under Schedule III, except for lottery, betting, and gambling. Section 2(80A) created a unified category called “specified actionable claims,” which explicitly includes:
- Betting and gambling
- Casinos
- Horse racing
- Lottery
- Online money gaming
2. Online Gaming & Online Money Gaming — Section 2(102A)
Online Gaming means offering a game on the internet or an electronic network. However, Online Money Gaming specifically refers to games where players pay or deposit money (or virtual digital assets) with the expectation of winning cash or rewards, irrespective of whether the outcome depends on skill, chance, or a combination of both.
Valuation Methodology: Rules 31B and 31C Explained
The calculation of taxable value in gaming platforms was a key point of dispute between industry operators and revenue authorities. To standardize valuation, the Central Board of Indirect Taxes and Customs inserted Rules 31B and 31C into the CGST Rules.
| Provision | Applicability | Taxable Value Formula | Key Deduction Rules |
|---|---|---|---|
| Rule 31B | Online Money Gaming | Total monetary amount (or Virtual Digital Assets) deposited by player into wallet. | No GST reduction if player refunds or does not play deposited money. Re-invested winnings are NOT taxed again. |
| Rule 31C | Casinos (Physical & Online) | Total amount paid to purchase tokens, chips, coins, or entry tickets. | Unused chips refunded back to player do not qualify for retrospective GST deductions. |
Official tax notifications and operational circulars detailing these valuation standards are regularly updated on the official Central Board of Indirect Taxes and Customs (CBIC) portal.
How 28% GST Works: Practical Example
To understand the monetary impact of Rule 31B on players and platform operators, consider the following deposit scenario:
- Deposit Amount: A player deposits ₹1,000 into an online fantasy sports app wallet.
- Tax Burden: Since 28% GST applies to the initial deposit, the taxable base value is ₹781.25, and the 28% GST component equals ₹218.75 (or if ₹1,000 is base deposit, total payable is ₹1,280).
- Gameplay Winnings: If the player wins ₹5,000 and re-stakes those winnings into a second contest without withdrawing to a bank account, no additional GST is levied on the ₹5,000 prize reinvestment.
This entry-point taxation model ensures that tax is collected once at deposit, protecting players from compounding tax on every individual contest round within the platform.
Compliance Rules for Offshore Gaming Platforms
To ensure a level playing field between domestic platforms and foreign gaming websites, Section 14A was inserted into the Integrated Goods and Services Tax (IGST) Act.
Mandatory Registration & Point of Contact
Any offshore online money gaming entity offering services to individuals located in India must:
- Obtain mandatory GST registration under the Single Web-Based Entity scheme on the GST Portal.
- Pay 28% IGST on all player deposits sourced from India.
- Appoint a designated representative in India for tax administration and compliance.
Failure to comply with these provisions empowers the central government to block public access to non-compliant foreign websites and applications under Section 69A of the Information Technology Act.
💡 Navigating GST Valuation & Gaming Compliance?
Structuring gaming deposit flows, managing Rule 31B/31C calculations, and handling show-cause notices regarding historical tax periods require specialized indirect tax advice.
Get experienced legal guidance, tax structuring, and audit support from expert Chartered Accountants and Advocates at Delhi Tax Solutions. Contact our litigation team to safeguard your digital gaming business.
Frequently Asked Questions (FAQs)
+ Q: What is the GST rate on online money gaming?
A: Online money gaming, fantasy sports, and physical or virtual casino tokens are taxed at a flat rate of 28% GST on the full value of the deposit made by the player.
+ Q: Is GST charged on every game round or only on deposits?
A: GST is charged only once at the entry point when a player deposits money into the platform wallet. Subsequent games played using contest winnings without withdrawing do not attract fresh GST.
+ Q: What is the difference between Rule 31B and Rule 31C?
A: Rule 31B prescribes the valuation method for online money gaming deposits, whereas Rule 31C prescribes the valuation for purchasing chips, tokens, or entry tickets in physical and online casinos.
+ Q: Are games of skill exempt from 28% GST?
A: No. The statutory definition under Section 2(102A) applies 28% GST to online money gaming regardless of whether the outcome depends on skill, chance, or both.
About this article: Based on Section 2(80A), Section 2(102A), Rule 31B, Rule 31C of CGST Act, and Section 14A of IGST Act. Updated for 2026.
Disclaimer: This article is intended for educational and informational purposes only and does not constitute formal legal or tax advisory opinions.
