
💡 Key Takeaways
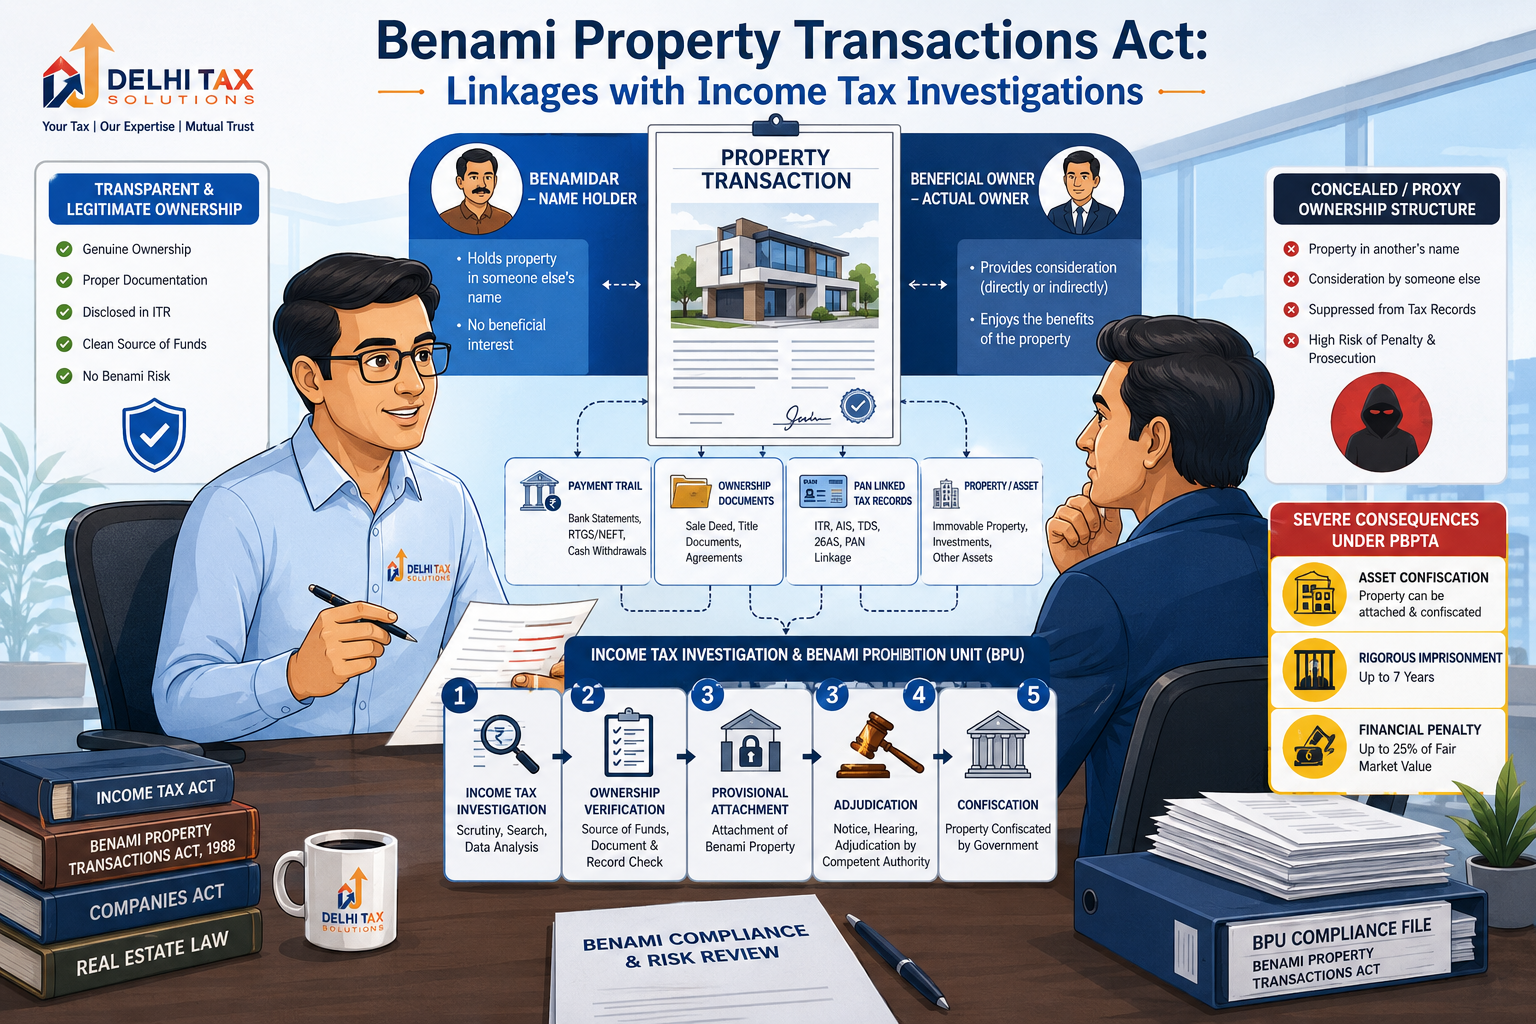
- The Prohibition of Benami Property Transactions Act (PBPTA) targets properties held under fictitious names or by non-true owners to mask wealth.
- Income Tax Department Investigation Units operate as the primary investigative agency executing benami probes and asset attachments.
- Consequences include rigorous imprisonment up to 7 years, confiscation of property without compensation, and heavy financial fines.
- Key distinctions exist between the Benami Act and regular income tax proceedings, notably focusing on ownership concealment rather than tax evasion alone.
- Structuring transparent asset ownership is crucial during Income Tax Filing and corporate structuring.
In the framework of Indian economic law, maintaining absolute transparency in asset ownership is paramount. For decades, the acquisition of real estate and financial assets using fictitious names or proxy holders—commonly known as benami transactions—was utilized to conceal unaccounted wealth. To dismantle this parallel economy, the Prohibition of Benami Property Transactions Act (PBPTA) empowers authorities with sweeping enforcement powers. Crucially, these anti-benami operations are closely integrated with Income Tax Department investigations. Understanding the Benami Property Transactions Act income tax linkages is essential for high-net-worth individuals, investors, and business owners managing complex Company Registration portfolios.
What Is a Benami Transaction? Core Statutory Definitions
The Benamidar vs. The Beneficial Owner
Under the PBPTA, a benami transaction is broadly defined as any arrangement where a property is transferred to, or held by, one person (the benamidar), while the consideration for it has been provided or paid by another person (the beneficial owner). Key elements include:
- The Benamidar: The ostensible holder or proxy whose name appears on the title deed, bank account, or share certificate, but who holds no genuine beneficial interest.
- The Beneficial Owner: The actual mastermind who finances the acquisition and exercises control, while hiding behind the proxy to evade detection.
Exceptions Under the Law
The statute carves out specific exceptions where holding property in another person’s name is legally permissible. These include a Hindu Undivided Family (HUF) holding property in the name of a karta or family member for the benefit of the family, or a person purchasing property in the name of their spouse or children using known sources of income. However, if the funding source cannot be established, the transaction immediately falls under scrutiny.
The Operational Nexus: How Income Tax Probes Trigger Benami Actions
The Role of Investigation Wings
Many taxpayers mistakenly believe that benami proceedings are handled by a separate judicial body. In practice, the Income Tax Department Investigation Directorate functions as the primary investigative agency for the Benami Prohibition Units (BPUs). During routine search and seizure operations, survey actions, or data analysis of high-value transactions via the Compliance Portal, tax authorities frequently uncover assets registered under employees, distant relatives, or shell companies.
From Tax Scrutiny to Benami Attachment
When an assessment officer or search team discovers that a taxpayer owns properties far exceeding their declared income and routed through third-party proxies, the case is referred to the BPU. The Initiating Officer can then issue a provisional attachment notice under the PBPTA, freezing the asset for up to 90 days pending formal adjudication. Business operations handling commercial properties and Property Tax filings must ensure that asset ownership strictly matches corporate balance sheets.
⚡ Key Distinction
While income tax assessments focus on unearthing undisclosed income and levying tax/penalties, the Benami Act focuses on the confiscation of the asset itself and criminal prosecution.
Penalties, Confiscation, and Prosecution
Severe Legal Consequences
The penalties under the PBPTA are exceptionally stringent compared to standard tax defaults. Once an adjudicating authority confirms that a property is benami, the consequences include:
- Confiscation of Property: The Central Government acquires the property without any payment of compensation or refund of consideration.
- Rigorous Imprisonment: Persons entering into benami transactions to thwart revenue recovery or conceal assets face imprisonment ranging from 1 year up to 7 years.
- Financial Fines: Heavy monetary penalties amounting to up to 25% of the fair market value of the benami property can be levied.
- Prosecution for False Information: Furnishing false information to authorities during benami investigations attracts additional imprisonment terms of up to 5 years.
Corporate Governance and Compliance
Corporate entities must exercise extreme diligence. Utilizing subsidiary structures, nominee directors, or intricate share-holding layers without clear commercial rationale can trigger joint investigations by tax authorities and corporate regulators. Ensuring robust TDS Compliance and clean financial ledgers prevents unnecessary suspicion.
| Aspect / Legal Feature | Income Tax Act (Black Money / Evasion) | Benami Property Transactions Act (PBPTA) |
|---|---|---|
| Primary Focus | Tax evasion, undisclosed income, and unpaid taxes. | Concealment of asset ownership via proxy holders. |
| Enforcing Authority | Income Tax Assessment & Investigation Wing. | Benami Prohibition Units (BPUs) of the IT Department. |
| Core Penalty | Tax demand, 100%–300% penalty on tax evaded, interest. | Confiscation of asset + up to 7 years rigorous imprisonment. |
| Compensation | Tax is calculated on income; balance funds remain with taxpayer. | Complete forfeiture of the property to the Central Government. |
Safeguarding Assets and Professional Advisory
Maintaining Transparent Documentation
To insulate yourself from benami investigations, absolute transparency is vital. Every asset purchase—whether residential real estate, commercial land, or equity holdings—must be backed by verifiable banking channels, clear gift deeds, or documented loan agreements. Official releases by the Press Information Bureau frequently highlight the government’s crackdown on shell companies and benami asset holders. Furthermore, apex bodies like the Reserve Bank of India and the Ministry of Corporate Affairs maintain stringent frameworks regarding beneficial ownership disclosures (such as Beneficial Ownership registers for companies).
Expert CA Advisory
Navigating the complex interface between income tax investigations and anti-benami legislation requires seasoned professional guidance. If you are structuring corporate investments, dealing with family property settlements, or responding to inquiries from the Income Tax Department, expert support is indispensable. Talk to a Delhi Tax Solutions expert today. Our certified Chartered Accountants and legal advisors will audit your asset holdings, verify beneficial ownership disclosures, and protect your enterprise from severe regulatory liabilities.
Understanding the strict parameters of the Benami Property Transactions Act income tax framework ensures that your wealth accumulation remains lawful, transparent, and secure. Connect with Delhi Tax Solutions to secure professional compliance guidance and achieve absolute peace of mind.
About this article: Researched using official government sources and Delhi Tax Solutions’ in-house tax advisory team. Last updated August 2026.
Frequently Asked Questions (FAQs)
Q: What is the Prohibition of Benami Property Transactions Act (PBPTA)?
A: The PBPTA is a comprehensive Indian statute enacted to prohibit benami transactions—arrangements where property is held in the name of one person while being financed by another—enabling the government to confiscate such properties and penalize offenders.
Q: Who is considered a “benamidar” and who is the “beneficial owner”?
A: A benamidar is the ostensible or proxy holder whose name appears on the property documents. The beneficial owner is the actual person who finances the acquisition and exercises effective control while concealing their identity behind the proxy.
Q: How does the Income Tax Department uncover benami properties during investigations?
A: The Income Tax Department uncovers benami assets through search and seizure operations, survey actions, data analytics from the Annual Information Statement (AIS), and information gathered by Benami Prohibition Units (BPUs) investigating disproportionate asset holdings.
Q: What are the legal penalties and imprisonment terms for benami transactions?
A: Penalties under the PBPTA include the outright confiscation of the property without compensation, rigorous imprisonment ranging from 1 to 7 years for the beneficial owner and abettors, and heavy financial fines up to 25% of the fair market value of the property.
Q: How does benami law differ from regular income tax black money proceedings?
A: Regular income tax proceedings focus on calculating tax liability and levying monetary penalties on undisclosed income. In contrast, the Benami Act targets the concealment of ownership identity, resulting in the complete confiscation of the physical asset by the government alongside criminal imprisonment.
