
? Key Takeaways
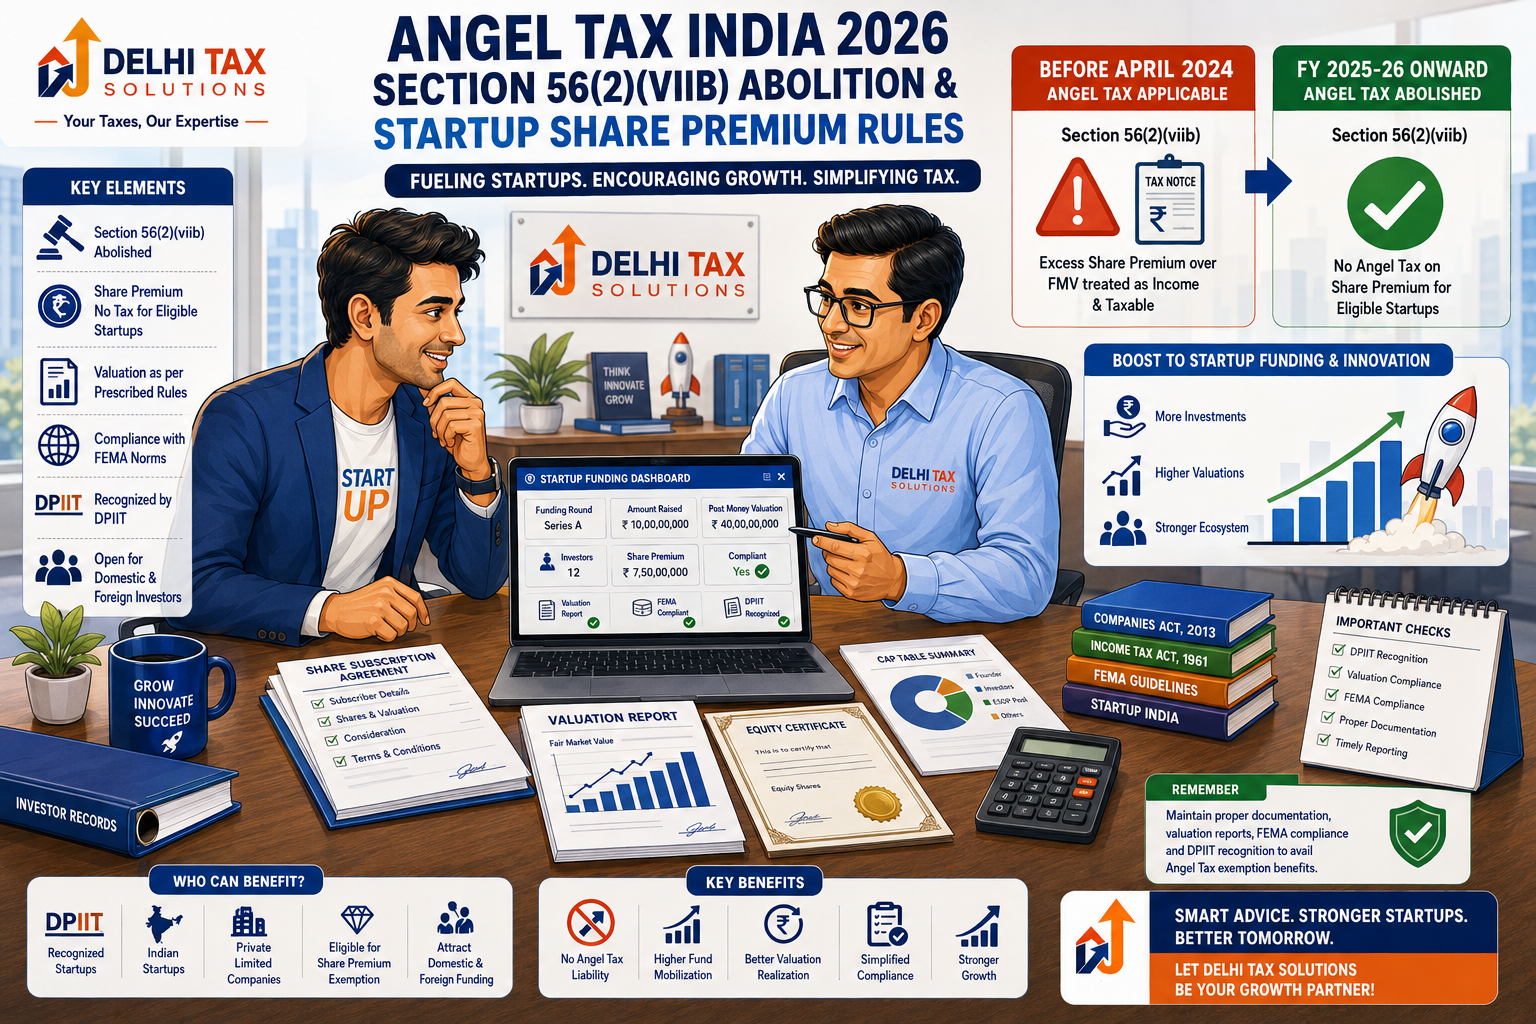
- Angel tax under Section 56(2)(viib) was officially abolished for all investor classes starting FY 2024-25.
- New fundraising rounds in 2026 face no income tax liability on share premiums exceeding fair market value.
- Historical funding rounds completed prior to April 2024 still require robust documentation and defensive filings.
- Valuation standards remain vital for foreign exchange regulations, company law, and employee stock options.
- Professional corporate tax planning protects emerging enterprises from legacy scrutiny notices and audit disputes.
Securing venture capital and early-stage funding is a milestone moment for emerging enterprises scaling across commercial hubs like Delhi NCR. For over a decade, analyzing the legal nuances of angel tax India startups compliance remained a mandatory exercise for founders navigating complex share premium rules.
Originally enacted to curb the circulation of unaccounted money through inflated share valuations, the provision created severe hurdles for genuine businesses. With sweeping legislative updates reshaping corporate taxation, founders today operate in a vastly different regulatory landscape. Understanding these structural changes is essential for maintaining pristine corporate records.
This comprehensive advisory guide examines the complete abolition of the tax, historical scrutiny risks, and ongoing valuation requirements for businesses preparing financial filings for FY 2025-26.
What is the current tax status of angel investments for unlisted companies?
Angel tax, formally known as the levy under Section 56(2)(viib) of the Income-tax Act, 1961, was completely abolished for all classes of investors by the Finance (No. 2) Act, 2024, effective from April 1, 2024. Official guidelines published by the Income Tax Department confirm that closely held unlisted companies issuing shares at a premium above fair market value no longer face income tax liabilities on the excess amount. Structuring enterprise entities through proper Company Registration helps founders establish solid legal frameworks before onboarding institutional investors.
How did the historical angel tax exemption DPIIT framework operate?
Before its complete abolition, navigating the angel tax exemption DPIIT framework was the primary defense mechanism for qualifying startups. Policy directives released by the Press Information Bureau outline how recognized entities could secure immunity from tax scrutiny by fulfilling specific certification criteria set by the Ministry of Commerce and Industry.
Startups had to obtain formal recognition, maintain prescribed paid-up capital limits, and file specific exemption declarations. Corporate finance teams also had to balance these exemptions with recurring statutory duties such as TDS filings and GST Registration compliance mandates.
Securing DPIIT recognition
Eligible startups registered with the Department for Promotion of Industry and Internal Trade secured provisional protection against arbitrary share valuation adjustments.
Filing Form 2 declarations
Qualifying entities submitted structured declarations to tax authorities to claim statutory immunity from share premium additions under historical provisions.
What legal nuances defined Section 56(2)(viib) angel tax disputes?
Comprehending the mechanics of Section 56(2)(viib) angel tax litigation clarifies why industry stakeholders welcomed its legislative removal. Economic reports published by the Reserve Bank of India emphasize that unpredictable tax demands on capital infusions stifled entrepreneurial risk-taking and foreign direct investment flows.
When unlisted firms issued shares at prices exceeding calculated fair market value, the differential was taxed under income from other sources at steep corporate tax rates, creating severe cash flow distress for early-stage ventures.
Treating share premium as income
Historical provisions empowered tax officers to treat share premiums above fair value as taxable corporate income, triggering sudden tax demands.
Broadening scope to non-residents
Amendments introduced in 2023 extended these tax provisions to foreign investors, creating friction in cross-border venture capital transactions.
What are the ongoing angel tax valuation rules for companies?
Evaluating current angel tax valuation rules confirms that while tax penalties on share premiums are gone, professional valuation standards remain critical. Regulatory updates monitored by the Ministry of Corporate Affairs show that rigorous valuation methodologies are still mandated for foreign exchange controls, company law issuances, and employee stock options.
Founders must continue adhering to prescribed pricing mechanisms when allocating equity to domestic or international participants.
Applying Discounted Cash Flow models
Merchant bankers and chartered accountants utilize projected cash flow models to establish justifiable share values based on future business growth projections.
Utilizing Net Asset Value calculations
Balance-sheet-based NAV computations provide baseline valuation benchmarks required for specific statutory corporate law filings.
| Compliance Parameter | Historical Era (Up to March 2024) | Current Era (FY 2025-26 Onward) |
|---|---|---|
| Taxability of Share Premium | Taxed as income if price exceeded fair value | Completely abolished for all investor classes |
| Applicability to Foreign Investors | Included under scope from FY 2023-24 | Exempt from share premium tax provisions |
| Mandatory DPIIT Exemption Route | Required filing Form 2 to claim safety | Not required for current tax exemption |
| Relevance of Valuation Reports | Critical defense against tax scrutiny additions | Required for FEMA, Companies Act, and ESOPs |
? Quick Summary
Section 56(2)(viib) angel tax was abolished for all investors from April 2024, eliminating share premium tax risks while keeping valuation rules active for FEMA and company law.
How do historical funding rounds handle past tax scrutiny notices?
Addressing legacy assessment notices for past financial years requires careful archival documentation. According to tax advisory cases handled by our CA team at Income Tax filing divisions, older fundraising rounds completed before April 2024 remain subject to potential scrutiny under unamended historical laws.
Defending historical assessment proceedings
Founders facing inquiries for past rounds must present contemporaneous valuation reports, board resolutions, and proof of investor identity to resolve legacy disputes.
Preserving archival compliance files
Maintaining secure digital archives of past share subscription agreements and bank remittance records safeguards companies during multi-year tax audits.
Why expert CA guidance matters for startup equity compliance.
Navigating corporate equity transactions requires professional oversight to ensure seamless compliance with corporate law and statutory reporting standards. Our CA advisory team at Delhi Tax Solutions helps startup founders structure their funding rounds and maintain pristine documentation effortlessly.
Talk to a Delhi Tax Solutions expert to get your corporate tax filings and startup compliance reviews managed seamlessly today.
About this article: Researched using official government sources and Delhi Tax Solutions’ in-house tax advisory team. Last updated August 2026.
This article is for general informational purposes and is not a substitute for personalised professional tax advice.
Frequently Asked Questions (FAQs)
Q: What is the current tax status of angel investments for unlisted companies in India?
A: The current tax status is that angel tax under Section 56(2)(viib) was completely abolished for all classes of investors by the Finance (No. 2) Act, 2024, effective from April 1, 2024. Consequently, unlisted companies issuing shares at a premium above fair market value during FY 2025-26 and FY 2026-27 do not incur any income tax liability on the share premium received.
Q: How do historical funding rounds handle past Section 56(2)(viib) notices?
A: Historical funding rounds executed prior to April 1, 2024, remain legally governed by the tax laws applicable during those specific financial years. Companies facing scrutiny notices for older capital raises must rely on contemporaneous valuation reports, DPIIT exemption certificates, and robust investor verification records to defend past additions before tax authorities.
Q: Which valuation rules apply for corporate share issuances under Indian tax laws?
A: While income tax penalties on share premiums have been eliminated, professional valuation methodologies under Rule 11UA—such as Discounted Cash Flow and Net Asset Value methods—continue to play a vital role. These valuations remain mandatory for complying with Foreign Exchange Management Act pricing guidelines, company law issuances, and employee stock option pricing.
Q: What role does DPIIT recognition play for startups following tax rule changes?
A: DPIIT recognition is no longer required specifically for escaping angel tax liabilities because the provision itself has been abolished. However, maintaining DPIIT startup recognition remains highly advantageous for claiming tax holidays under Section 80-IAC, accessing self-certification benefits under labor laws, and participating in lucrative government procurement tenders.
Q: How should founders manage FEMA pricing and share premium documentation today?
A: Founders onboarding foreign institutional or angel investors must ensure that share issuance prices strictly comply with RBI and FEMA pricing guidelines. This requires obtaining certified valuation reports from qualified chartered accountants or merchant bankers, filing requisite Form FC-GPR filings, and maintaining transparent bank remittance trails to satisfy regulatory authorities.
