
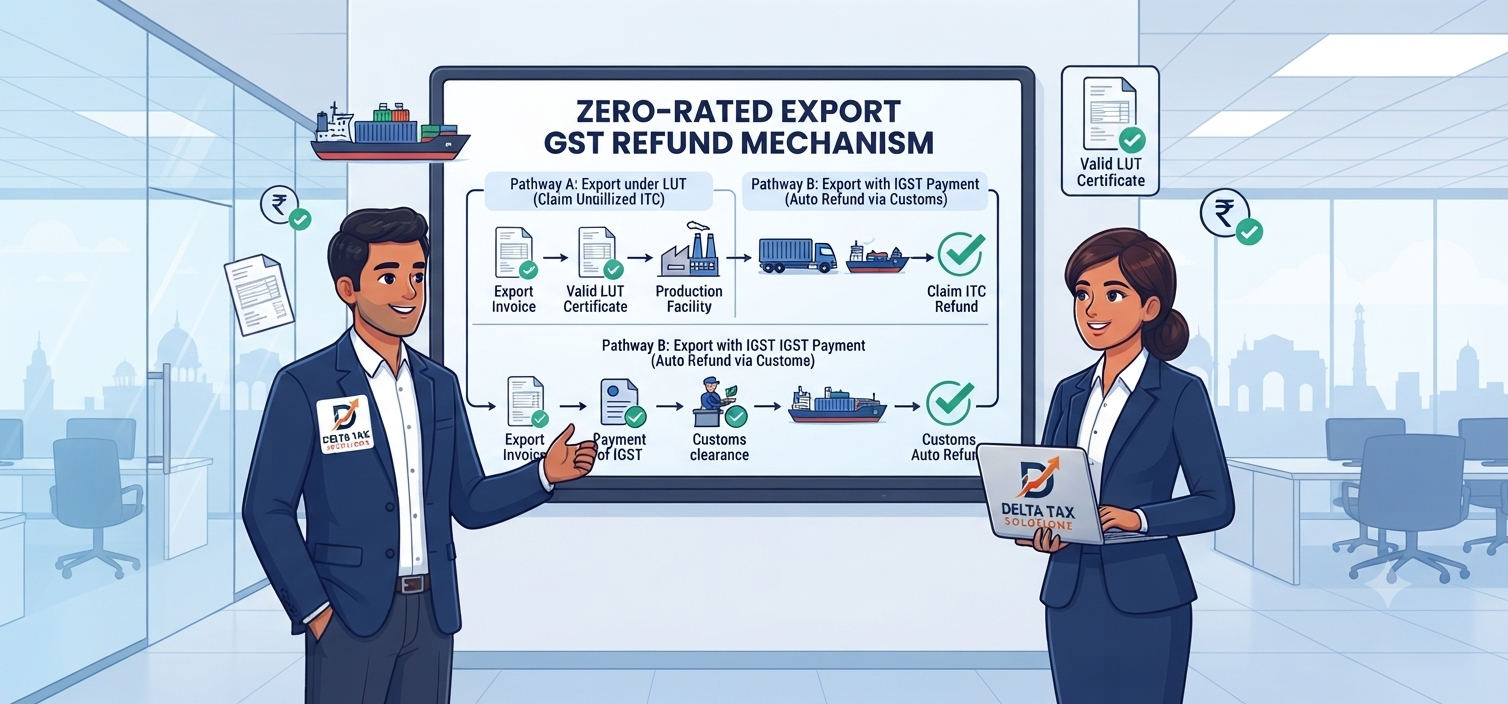
💡 Key Takeaways: Export Refund GST
- Exports of goods and services qualify as zero rated supplies under Section 16 of the IGST Act, meaning no tax burden is passed to foreign buyers.
- Exporters can claim an export refund gst through two distinct routes: Exporting under LUT GST (claiming unutilized ITC) or Exporting on payment of IGST (claiming tax refund).
- When exporting under LUT without payment of IGST, refund of unutilized Input Tax Credit (ITC) is calculated using the statutory formula under Rule 89(4) of CGST Rules.
- Filing a valid Letter of Undertaking (Form GST RFD-11) prior to exporting is mandatory to claim refund without paying upfront integrated tax.
- Provisional refund equal to 90% of the eligible claim is granted within 7 days of receiving Form RFD-02 acknowledgment for LUT exports.
Exporting goods and services from India is a cornerstone of economic growth, and the GST framework is specifically structured to ensure Indian exports remain globally competitive. Under GST law, exports are classified as zero rated supplies. This fundamental principle ensures that taxes paid on input materials or services do not become a cost burden for foreign trade.
However, many businesses struggle with selecting the right refund mechanism or navigating the mathematical adjustments required for an export refund gst claim. This guide breaks down the legal pathways, Rule 89(4) calculations, and the online procedure to claim your unutilized Input Tax Credit (ITC) seamlessly on the GST Common Portal.
Two Options for Claiming GST Refund on Exports
Section 16(3) of the IGST Act provides exporters with two distinct mechanisms to claim tax benefits on zero-rated exports:
| Feature | Option 1: Export under LUT/Bond | Option 2: Export on Payment of IGST |
|---|---|---|
| Upfront Tax Outflow | Zero (No tax paid on export invoice) | High (IGST paid using cash/credit) |
| Prerequisite Document | Filing Form GST RFD-11 (LUT GST) | Direct IGST Payment entry in GSTR-3B & GSTR-1 |
| Type of Refund Claimed | Refund of Unutilized Input Tax Credit (ITC) | Refund of Integrated Tax (IGST) paid |
| Filing & Processing Route | File Form GST RFD-01 on portal with Statement 3/3A | Automated processing via Customs ICEGATE system |
| Eligible Credit Scope | Inputs & Input Services (Capital Goods excluded) | Full IGST amount paid on export invoice |
Rule 89(4) Formula for Refund of Unutilized ITC
When you export goods or services without payment of tax under a Letter of Undertaking, your accumulated credit ledger holds unutilized ITC from domestic purchases. To claim this refund under Section 54(3), the portal applies the statutory mathematical formula prescribed under Rule 89(4) of the CGST Rules:
Where key variables are defined as follows:
- Turnover of Zero-Rated Supplies: Total value of zero-rated export supplies of goods and services made during the relevant period under LUT/Bond without payment of tax.
- Net ITC: Total input tax credit availed on inputs and input services during the tax period (excluding capital goods credit and ITC claimed under other specific refund sections).
- Adjusted Total Turnover: Sum of total turnover in the state/UT, excluding exempt supplies and non-zero-rated turnover.
Step-by-Step Procedure to Claim Export ITC Refund
Follow these steps on the GST Services Portal to file your application for unutilized credit refund:
1. Ensure Online Filing of Form GST RFD-11 (LUT)
Before executing any zero-rated exports without paying tax, navigate to Services → User Services → Furnish Letter of Undertaking (LUT). Complete Form RFD-11 for the current financial year. An ARN will be generated immediately.
2. File GSTR-1 & GSTR-3B Returns
Report all export invoices in Table 6A of Form GSTR-1 with “Export under LUT/Bond”. Ensure that shipping bill numbers, port codes, and invoice dates are entered accurately. File your corresponding GSTR-3B return for the period.
3. Prepare Offline Statement 3 / 3A Excel File
Download the Offline Tool for Refund on Exports. Enter invoice-wise shipping bill details, BRC/FIRC numbers (for export of services), FOB values, and taxable values. Validate and generate the JSON file.
4. Initiate Form GST RFD-01 Application
Log in to the GST portal, go to Services → Refunds → Application for Refund. Select “Refund of unutilized ITC on account of exports without payment of tax” and select the tax period. Upload the JSON file and auto-populate Net ITC and turnover details.
5. Verification, CA Certificate & DSC Submission
Verify bank details. If the claim exceeds ₹2 Lakhs, attach a Chartered Accountant certificate in Annexure 2 disproving unjust enrichment. Submit using Digital Signature Certificate (DSC) or EVC.
⚡ Fast-Track Processing for LUT Exporters
Under Section 54(6), taxpayers exporting goods/services under LUT GST are entitled to a 90% Provisional Refund within 7 days of receiving an online acknowledgment (Form RFD-02). The remaining 10% is disbursed after final verification within 60 days.
Maximize Your Export Refund with Delhi Tax Solutions
Errors in shipping bill numbers, mismatched FOB values, or incorrect Rule 89(4) calculations can lead to Deficiency Memos (RFD-03) and blocked working capital.
Our expert tax team specializes in end-to-end export refund management—from annual LUT filing and statement validation to officer liaising and CA certification. Partner with our team at Delhi Tax Solutions GST Services today.
Frequently Asked Questions (FAQs)
+ Q: Who is eligible to file a Letter of Undertaking (LUT GST)?
A: Any registered taxpayer exporting goods or services is eligible to file an LUT in Form GST RFD-11, provided they have not been prosecuted for an offense under GST law or existing laws involving tax evasion exceeding ₹2.5 Crores.
+ Q: Can I claim a refund on ITC accumulated on Capital Goods used for exports?
A: No. Under Rule 89(4), “Net ITC” for export refunds under LUT includes credit availed on inputs and input services only. Input tax credit on capital goods is strictly excluded from the refund formula.
+ Q: What is the time limit for receiving export realization for service exports?
A: For service exports to qualify as zero-rated, payment must be realized in convertible foreign exchange (or INR where permitted by RBI) within 1 year from the date of invoice (or as extended by RBI). FIRC or BRC documentation is mandatory.
+ Q: What happens if export proceeds are not realized within the prescribed RBI deadline?
A: Under Rule 96B, if export proceeds for goods or services are not realized within the time allowed under FEMA, the exporter must deposit the refunded GST amount along with interest within 30 days of the expiration of the deadline.
+ Q: Is a Chartered Accountant (CA) Certificate mandatory for export refunds under LUT?
A: If the total refund claim for a tax period exceeds ₹2 Lakhs, a CA/CMA certificate in Annexure 2 of Form GST RFD-01 is required to certify that the refund claim meets statutory parameters and does not involve unjust enrichment.
About this article: Authored using statutory provisions of Section 54 of CGST Act, Section 16 of IGST Act, and Rule 89(4) guidelines from Delhi Tax Solutions. Last updated September 2026.
Disclaimer: This blog post is for educational purposes and does not constitute formal legal or tax advisory opinion.
